
DOMO Capital Management, LLC on X
Huge double beat by $ALTO - expect some very positive commentary on the call. Excluding derivatives - EPS of $0.20 for the quarter!
Sector
Everything our editor has picked under this sector, best first.
182 stories
Huge double beat by $ALTO - expect some very positive commentary on the call. Excluding derivatives - EPS of $0.20 for the quarter!
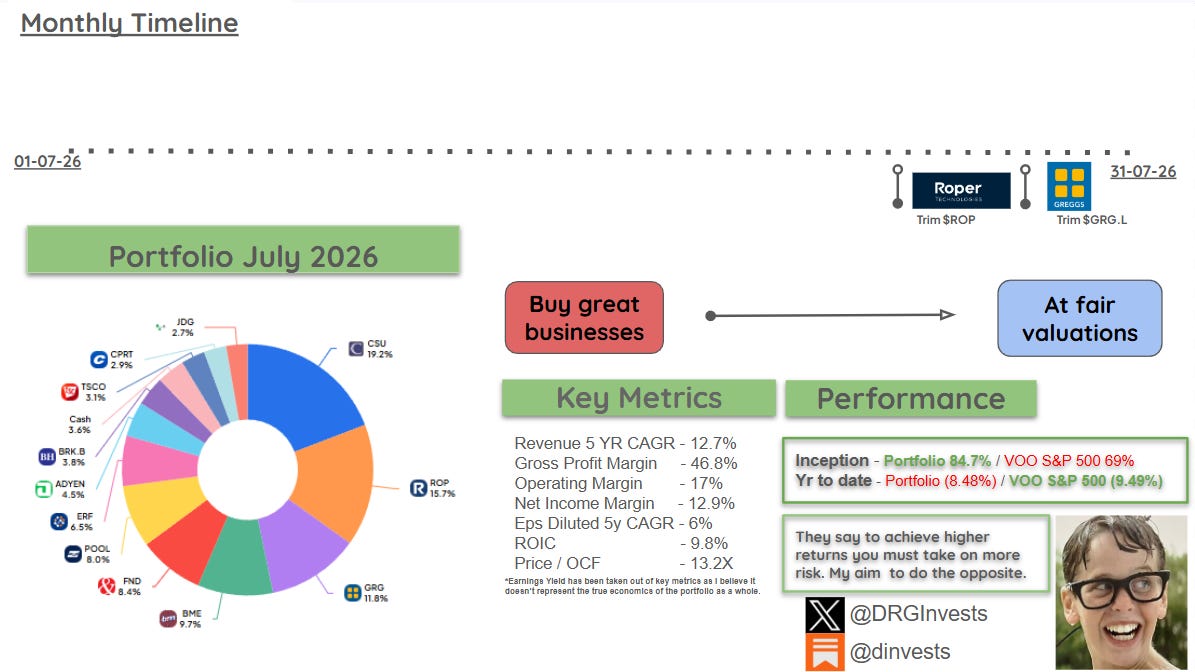
Portfolio update trimmed Greggs and Roper Technologies after earnings, with Roper raising guidance and Greggs reporting 7.2% revenue growth…
$SB #sugar looks like it is breaking out of this congestion. Mar27 contract below 👇 https://t.co/QMvIM6m2Ab
Tractor Supply cut FY26 guidance and plans to close 75 Petsense stores; Sazerac’s Brown-Forman bid was rejected as prediction markets…
Flowers Foods cut its dividend to fund $300 million of debt reduction by 2027 after the $795 million Simple Mills acquisition lifted…
@calleymeans @SecKennedy Looks like a tailwind for $UNFI
Never thought I'd be loading the boat again.... $ALTO
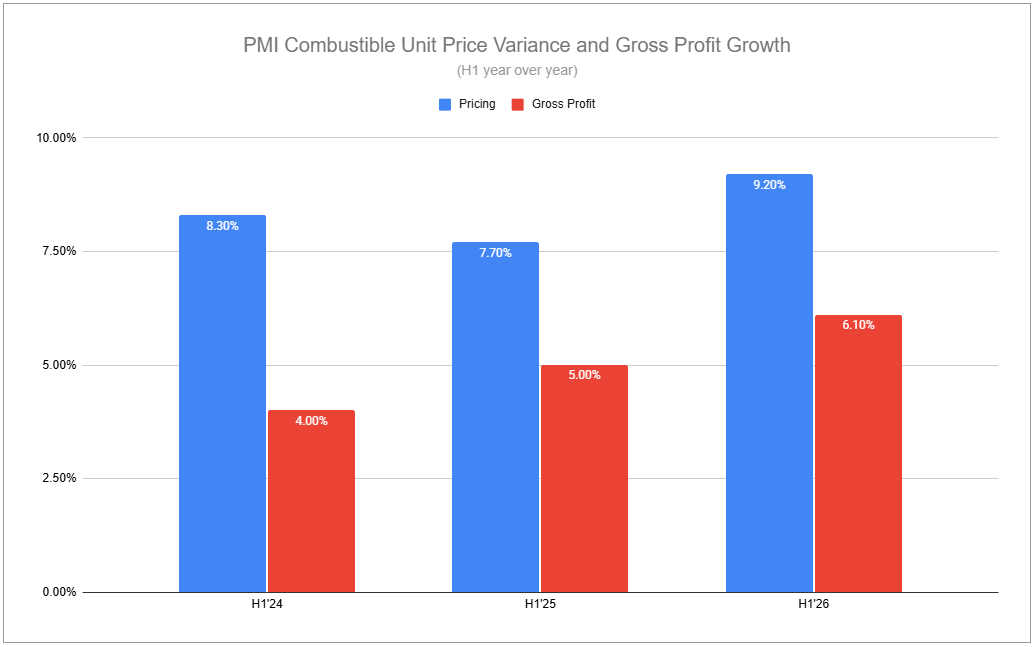
Philip Morris grew Q2 cigarette volumes 1.1%, revenue 9.8% and gross profit 11.5%, while IQOS retained Japan leadership despite…
@TidefallCapital I think macro beer is still deeply challenged, though I own a little bit of $TAP and $ABEV. I'm much more confident spirits will recover.
Philip Morris reported strong Q2 2026 trading, while U.S. ZYN growth barely increased. Shares rose 3.3% to a record high.
Yeah, $CPB bulls trying to hold the line on the 2002 and 1995 lows. They have some solid brands for sure, but the management is moronic, the board even worse, they have no clue on capital management, and the balance sheet is a disaster. Everything but the last point is an argument for this business to be sold. However, that leverage.... I guess someone can come in and eliminate the dividend which frees up $450MM in FCF. From there you can probably delever this biz 2-3 turns in a few years. Tough sledding, but there's a lot of wasted advertising across this company, that's for sure.
$ALTO 🤷♂️ https://t.co/67lkE1qWvP https://t.co/JDe6p8IL4U
New 52 week high for $GPRE...
Just had lunch with my son at Wendy's $WEN in Lee, NH. He had the Baconator, I had the spicy chicken sandwich. Both of us thought it was pretty darn good. Ample amount of chicken, decent bun, reasonably spicy. We both liked the fries as well. Restaurant was clean, service was quick.
Molson Coors trades at 6.2x free cash flow and offers a roughly 15% shareholder yield, but declining beer volumes could make it a value…
@calleymeans @SecKennedy Seems like a tailwind for Lifeway $LWAY
@orrdavid I don't own $WEN but I do see a powerful upside potential. Perhaps I am biased as it has been my favorite burger fast food restaurant for 35+ years (the only one my parents let us go to when I was a kid😂).
Molson Coors, a 7% portfolio position, is the world’s fourth-largest brewer with leading beer shares in Canada and the US through Coors and…
Wingstop generates most of its $697 million revenue from franchise royalties across a 3,153-restaurant, 98%-franchised system while…
@jonathanmaze Thanks for the insight! I don't live near a Caseys so could not conduct my own taste test but was overlaying wingstop locations on top of Caseys yesterday thinking this could be a growing problem for $WING especially undercut on $
Campbell's trades at 10-11x earnings and a 7% yield after shares fell over 50%, while 4x leverage, weaker volumes and margin pressure…
??? Two things can be true at the same time. In that you can have a slow down from weak international travel (administration) domestically, weak lower end consumer, glp, and inflation that is dragging down sales. And yet you can continue to invest in new store counts if the economics of your model are intact AND you have the balance sheet to continue to invest in your business. The competitors you cited besides macro have other issues impacting their ability to invest; PTLO has a serious balance sheet issue SG has an economic model problem... *turns out 18$ salads is a tough business*. Mcdonalds increased store openings in 2008 AND 2009 even as SSS growth was slowing every year 06-09....those investments worked out just fine because the model works. $SHAK SSS still going to print solidly positive for the year while most chains won't this year (and thats without the added store count). Shak has issues, all restaurants are tough and tough to scale and Rob and the cfo are far from Mcdonalds level of execution, but at 1x sales and a +20% restaurant margin model with 4m AUV theres a lot more room to the upside then the downside at current levels. I don't think they get to the dream target of 1500 stores, but that would be a 10x from here, whats the downside, at almost 1x current....30% maybe? I'll take that asymmetric set up. (Entered shares today)
$BGS LOLZ! Just priced $475M sr notes at 11.625% to refinance 5.25% 2027 sr notes. Way worse than I expected. Circling the drain! Mark it zero! https://t.co/lwXYgOO069
Newest out. Scandinavian Tobacco Group: What If? "Q1'26 note." $STG $PM $BTI $IMBBY $MO $HAYPP https://t.co/mJsE8iJhfY
