
Farmer on X
@GrumpierBTDay @humblebillionz Here's what $INFL holds: https://t.co/UBtdHLRgc8
Sector
Everything our editor has picked under this sector, best first.
169 stories
@GrumpierBTDay @humblebillionz Here's what $INFL holds: https://t.co/UBtdHLRgc8
need more $GLD $GC https://t.co/sC4KNVanQw
BP is investing $10 billion annually in oil and gas through 2027 as higher crude prices, LNG expansion and debt reduction support earnings,…
 The Asian Investor 6 clicks
And the global half is already moving. $ELMT bought 4.99% of Masan High-Tech Materials for $124.75M on Oct 1, and expects the Vietnamese supplier to stay its key refiner even after Springer comes online. The ~$100M Refining & Trading bucket covers Australia and Spain on top of that. https://t.co/lTme3cYw9M
Signet’s shrinking store base and unit volumes have been masked by gold prices, while declining service-plan sales threaten its main profit…
Crean Hill cost Magna Mining $MGMNF (TSX: $NICU) US$11.3M in November 2022, and a 2024 preliminary study put the mine’s after-tax NPV at US$137.0M. If R2, the high-grade zone Magna found at its Levack mine, is Magna’s copper and precious metals upside, Crean Hill is its biggest nickel exposure. Crean Hill’s 2024 PEA (preliminary economic assessment) outlined a 13-year, 2,200 tonnes/day underground mine that sells its ore to a third-party mill: → Resource: 18.4Mt indicated at 1.01% nickel, 0.87% copper, and 2.47g/t platinum, palladium, and gold. → Capital: US$34.2M for an advanced exploration phase (early underground work and bulk mining before full production) that earns US$11.6M of revenue, then US$19.6M before commercial production. → Economics: After-tax NPV (at an 8% discount rate) of US$137.0M and a 129% IRR, at $8.50/lb nickel, $4.00/lb copper, $900/oz platinum, $1,000/oz palladium, and $2,150/oz gold. Weighting each metal’s price change by its share of PEA revenue, I estimate Crean Hill’s revenue would be ~32% higher at Q2 2026 prices, even though nickel, 51% of PEA revenue, is the only metal below its PEA price. CEO Jason Jessup says the pre-feasibility study (PFS), due in the first half of October, will use “more realistic consensus metal prices for 2026” and update the capital costs. He expects the PFS to come in “generally in line” with the PEA, with “some additional costs.” Jessup also said in July that Crean Hill’s capital is “not going to be anywhere near $140 million.” Unlike McCreedy West, Magna’s producing mine, Crean Hill carries no precious metals stream. To fund the restarts, Magna now has ~US$124M of cash, most of it from Alpayana, a Peruvian mining group that bought 19.9% of the company in August.
Golar LNG’s fourth FLNG vessel targets 3.5MTPA capacity and a 2029 delivery, supporting projected adjusted EBITDA above $1 billion in…
Canterra Minerals increased Lundberg indicated tonnage 55% to 26.1Mt, with 226.2Kt of contained copper equivalent, supporting a Buchans…
Franco-Nevada bought 10.0 million Kenorland shares, a 12.4% stake, for C$22.2 million in a secondary transaction that issued no new shares.
Long $CANE https://t.co/TfTk3YWtNE
Half the gold, platinum, and palladium in ore from McCreedy West, the producing mine of Magna Mining $MGMNF (TSX: $NICU), goes to Franco-Nevada $FNV for $1,200 per gold-equivalent ounce, 29.0% of the average gold price in Q4 2025. Magna inherited the deal, a precious metals stream, when it bought McCreedy West from KGHM $KGHPF, the Polish copper giant. A stream is a deal where a financier pays a miner upfront for the right to buy part of its future metal at a discount to market. Magna’s stream gives Franco-Nevada 50% of the gold, platinum, and palladium in ore from McCreedy West and “certain areas” of Levack and Podolsky, until the deposits run out or 2048. Franco-Nevada pays 60% of the monthly average gold price per gold-equivalent ounce (platinum and palladium converted into gold) from McCreedy West, capped at $1,200/oz once gold tops $2,000. In Q2 2026, the stream cut net revenue by US$3.9M, so revenue would have been ~18% higher without the stream. CEO Jason Jessup called the stream “a bit of an overhang” on McCreedy West, and in April said its terms are “definitely open for discussion” with Franco-Nevada. The higher gold climbs, the more the stream costs Magna, and I wouldn’t count on Franco-Nevada softening the terms. Crean Hill, Magna’s permitted nickel mine, carries no Franco-Nevada stream, and Jessup says R2, the high-grade zone Magna found at its flagship Levack mine, has none either. At Q4 2025’s gold price, Magna kept 64.5% of the value of McCreedy West’s gold, platinum, and palladium (50% + 50% × 29.0%). That means a stream-free ounce from Crean Hill or R2 is worth 1.55x as much to Magna as one from McCreedy West (100% / 64.5%). The stream also covers two areas of Levack, including the Morrison deposit. Franco-Nevada’s filings set the price for its Sudbury streams at $400/oz, rising 1% a year from July 2011, and its later increases applied to McCreedy West only, so Levack’s price would’ve reached ~$460/oz by Q4 2025 ($400 × 1.01^14). So at Q4 2025’s gold price, Magna would keep 55.6% of the value of Levack’s streamed ounces (50% + 50% × ($460 / $4,141.90)), less than the 64.5% it kept at McCreedy West.
Alliance Resource Partners has 2026 coal sales fully contracted and is expanding oil and gas royalties through AllDale, supporting its 9.8%…
 Timur Mekhantev 4 clicks
Blue Lagoon (BLAGF) is cash flow positive from high-grade gold and silver at its Boulder Vein, with just 10% of its property explored.
 Patient Tech Investor 4 clicks
The hoist at Levack, the flagship mine of Magna Mining $MGMNF (TSX: $NICU), was designed to move 6,000 tons a day, ~5.5x the record Q2 pace at McCreedy West, its producing mine. Most of Levack’s infrastructure is already built. Magna expects to finish refurbishing the hoist and the loading pocket where ore enters the shaft before the end of 2026. Magna is engineering a new ramp from surface (a sloped tunnel trucks can drive down) for the shallower zones, with the shaft serving the deeper Morrison ore. By mid-2026, crews had tunneled into the Intermediate Orebody (IOB), and Magna says mining the drilled part of the IOB “could begin immediately upon a positive restart decision.” CEO Jason Jessup said in July there’s a “very strong possibility that before the end of the year, we will skip first ore,” meaning hoist the first ore up the shaft, with shipments building through H1 2027. In the same interview, he said Levack and Crean Hill, Magna’s permitted nickel mine, are “both working towards commercial production in 2028.” On scale, he expects Levack to produce “possibly two to even three times” McCreedy West’s payable metal, which would make McCreedy West “our smallest mine within the next couple of years.” Magna’s first resource estimate for Levack (its estimate of the metal in the ground) found: → Contact deposits: 5.9Mt indicated at 3.2% copper equivalent (CuEq, which converts every metal into copper at set prices), mostly less than 750 meters deep. → Morrison footwall: 178,000 tonnes indicated at 15.5% CuEq, with the deposit continuing below the deepest drilling. → Total: 6.1Mt indicated at 3.54% CuEq and 5.2Mt inferred at 3.59% CuEq. Indicated tonnes come from drill holes spaced closely enough to support a mine plan. Inferred tonnes rest on fewer, more widely spaced holes, so their size and grade could still change with more drilling. Jessup says “the bulk of the PEA tons will come from the contact nickel zones,” so nickel matters far more to Levack’s PEA (preliminary economic assessment) than to McCreedy West, where it’s 10.3% of metal revenue. The PEA was due in Q3. On September 17, Magna pushed the PEA and Crean Hill’s pre-feasibility study to the first half of October to account for Canada’s proposed Productivity Mega Deduction. The deduction would let miners write off Canadian development spending right away, instead of deducting 30% of the balance a year, so both studies’ after-tax returns should come out higher. Jessup said of the PEA on September 24, “essentially it’s all done,” and he sees a “very high probability” of a restart declaration shortly after the PEA comes out.
 BTU · long
Peabody Energy, ticker BTU, is a low-cost producer of thermal and metallurgical coal with mines in the United States and Australia.
McCreedy West had “a few weeks” of development (the tunnels that reach new ore) ahead of its miners and no stopes (the blocks of ore being mined) ready to go when Magna Mining $MGMNF (TSX: $NICU) took it over in March 2025. So Magna spent 2025 catching up and missed its H2 2025 grade guidance, shipping ore at 2.64% copper equivalent (CuEq, which converts every metal into copper at set prices) in Q3 and 3.41% in Q4, below the 2.9-3.4% and 3.8-4.4% it guided. 2026 has gone better. In Q2, McCreedy West set Magna-era records for tonnage (98,446 tons) and cash margin, and production costs fell to US$144/ton processed from US$156 in Q1. Through H1 2026, McCreedy West produced 8.62M payable pounds of CuEq (the metal the mill and smelter pay for after recoveries). It needs 7.4-9.4M lbs in H2 to land in the 16-18M lbs guidance range, so repeating H1 would put the year inside guidance. Costs are inside guidance too. H1 cash costs (operating costs plus smelting and refining charges, per payable pound) of US$3.63/lb sit within the US$3.40-3.80 range. All-in sustaining costs (AISC, which add sustaining capital and corporate overhead) of US$4.39/lb also sit within US$4.20-4.70. Both exclude the precious metals stream held by Franco-Nevada $FNV, which buys half the mine’s gold, platinum, and palladium at a discount. Magna says the stream adds US$0.78-0.92/lb at its 2026 budget prices. Magna’s first reserve estimate for McCreedy West, effective December 31, 2025, came to 987,000 tonnes of probable reserves, which Magna says supports three years of production at its 2026 mining rate. Three years sounds short, but CEO Jason Jessup says it’s “in line with the reserves that McCreedy West has operated with since being restarted in 2003 by FNX Mining,” and that Magna “could have extended” the reserves. McCreedy West’s Intermain nickel zone isn’t in the reserves or the guidance. Jessup wants nickel to hold “north of $8” per pound “for at least a quarter” before restarting it, and says Magna could be shipping Intermain nickel to Vale $VALE “within 8 to 12 weeks” of a decision. At ~$7.48/lb nickel, the Intermain restart waits.
Bernstein expects copper to run short from 2027, and the IEA says a new copper mine takes ~17 years to go from discovery to production. So I found a miner restarting old ones, with a CEO who restarted its flagship once before and says it could produce 2-3x today’s output. Its restart study is due in the first half of October, and a much richer discovery at the same mine isn’t in the study yet. That company is Magna Mining $MGMNF (TSX: $NICU), a copper miner in Sudbury, Ontario. After more than a century of mining, Sudbury has plenty of past-producing mines to restart. Per Magna’s September deck, Brazil’s Vale $VALE and Switzerland’s Glencore $GLNCY are the only other companies with significant property holdings in the Sudbury Basin, and they run the district’s two mills and two smelters. Magna has agreements to sell its ore to both, so its next restarts don’t need a new mill. Magna’s stock trades at CAD$2.45/share, down 9% y/y and 38% below its CAD$3.94 intraday high on January 29, 2026. Counting its convertible notes, in-the-money options, and share units as shares, and netting out its cash plus the ~US$5.1M from exercising the options, enterprise value is ~US$454M. That buys you McCreedy West, the producing mine that carried Magna to its first quarter of positive free cash flow (FCF) in Q2 2026. You also get Levack and Crean Hill, two past-producing mines with a preliminary economic assessment (PEA) and a pre-feasibility study (PFS), respectively, due in the first half of October. Notably, Magna’s leaders have run McCreedy West and Levack before. Both mines belonged to FNX Mining, a Canadian miner, before they passed to KGHM $KGHPF, the Polish copper giant that sold them to Magna. CEO Jason Jessup led the FNX team that restarted Levack, and chair Vern Baker was FNX’s VP of Operations. Jessup also says Magna doesn’t plan any more financings after Alpayana, a Peruvian mining group, invested US$99M in August. So Magna could triple or quadruple its output (McCreedy West plus 2-3x from Levack) without raising more money, and R2, the high-grade zone it found at Levack, would come on top of whatever the PEA shows. The question is whether CAD$2.45 is an early price for a multi-mine Sudbury producer, or a price that already assumes Levack restarts well before its numbers are public.
$STK $WDC The cure for high prices is high prices! Demand destruction, substitution, capacity additions, etc. The invisible hand (almost) never fails!
On timber companies $RYN and $WY. If the long end keeps going up. 6-7% which I think is definitely possible. Then timber companies will get crushed. But my overall thesis remains and is happening in real time: energy-driven inflation, fiscal deterioration, failed treasury buybacks, the Fed losing the long end. Right now the market is repricing duration before it reprices scarcity. This gap can run for decades. Equities were destroyed in real terms through 1973 and 1974. But hard assets won the decade. I’m praying both of these timber companies keep going down. Land is my favorite asset to own. You can see it. You can touch it. You can hunt on it. You can fish on it. And you can grow productive timber on it. Huge swaths of land have massive optionality. Let’s hope Scott “I am the house” Bessent continues to lose the bond market. I want to see a bloodbath here.
Constellium’s widening feedstock-to-end-price spread supports 2026 EBITDA guidance of $980M-$1.02B and free cash flow above $300M.
 Andres Veurink
Occidental Petroleum could benefit as declining shale inventories and high rates curb industry capex, tightening oil supply against demand…
 Gen Z Investor
Not good for corn / corn basis. Good for $ALTO $GPRE https://t.co/Vv0h05uhzy
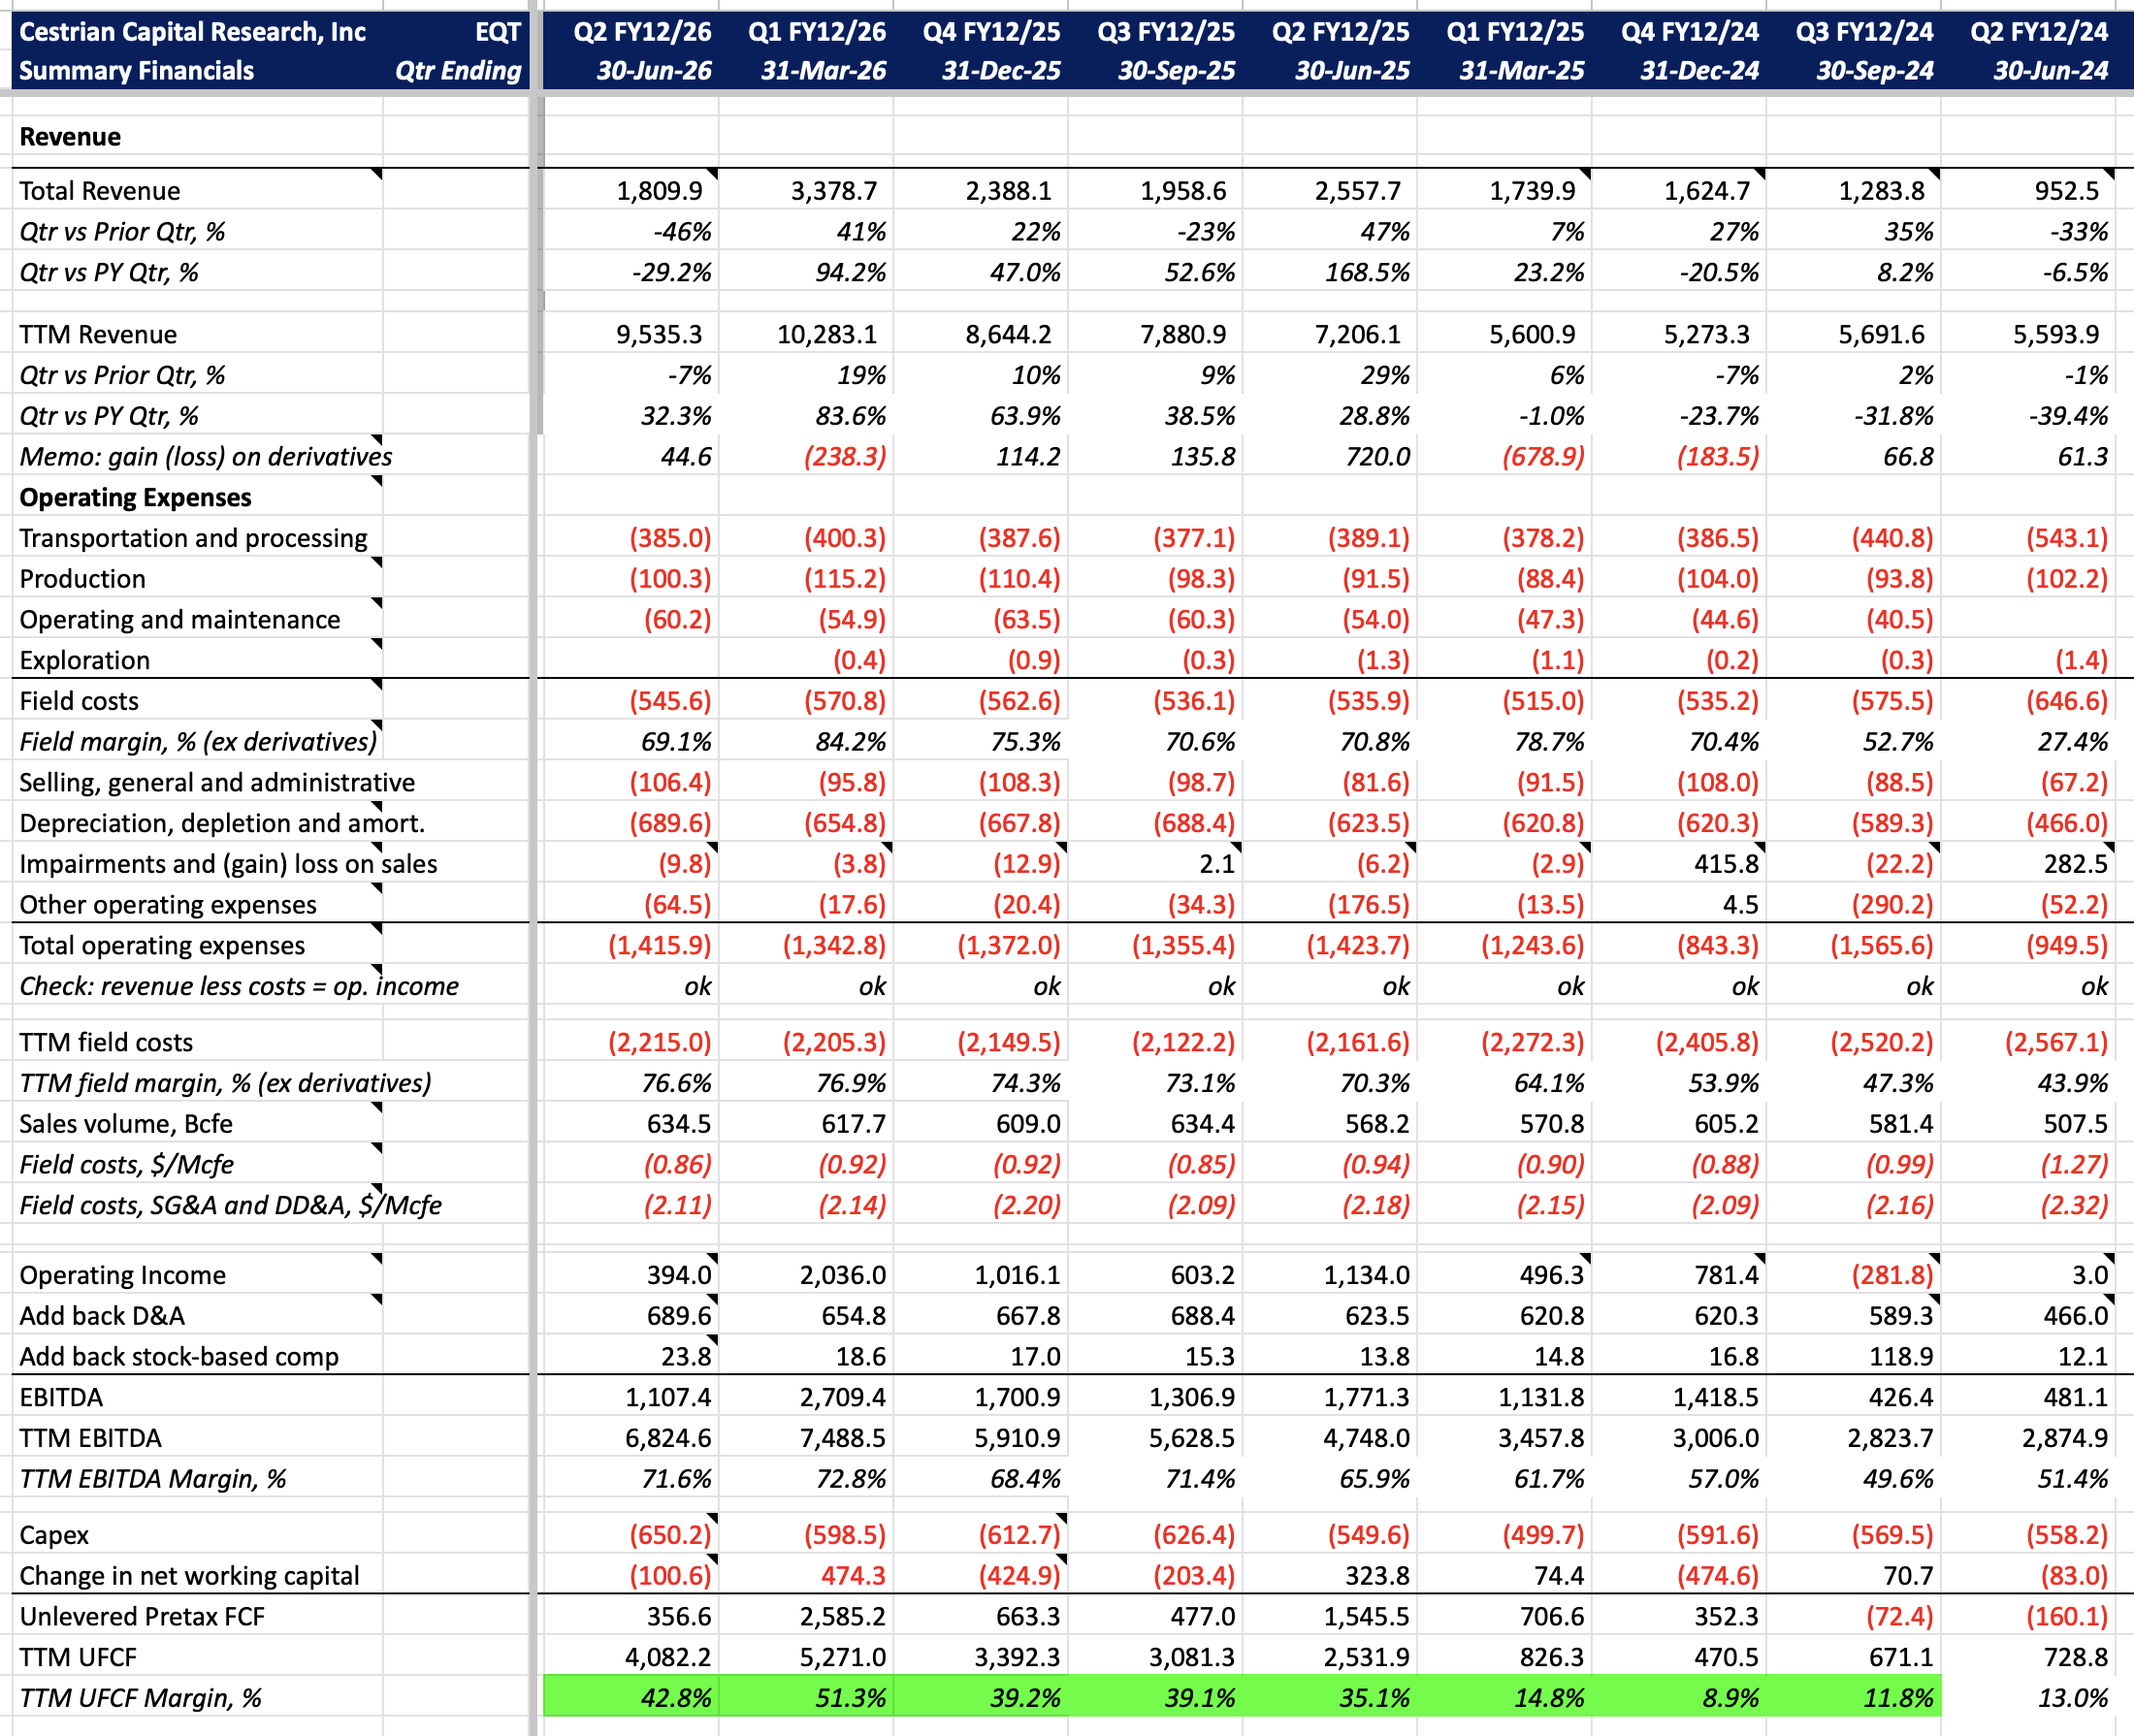
EQT remains tied to roughly $3 Henry Hub gas despite European prices near $23 per MMBtu, with US LNG export capacity limiting overseas…
POSCO Holdings trades at a 78.6% P/B discount as lithium, gas and trading profits reshape the steelmaker, while capex and lithium prices…
 Capital Connoisseur
