
Hunterbrook on X
NEW: An air permit application filed by an Atlas Energy Solutions ($AESI) subsidiary in Texas suggests OpenAI is the "leading frontier AI lab" backstopping its 283 MW power equipment and supporting infrastructure orders.
Friday, September 25
Everything we published on this day.
61 stories — the front page that day →
NEW: An air permit application filed by an Atlas Energy Solutions ($AESI) subsidiary in Texas suggests OpenAI is the "leading frontier AI lab" backstopping its 283 MW power equipment and supporting infrastructure orders.
People really need to stop thinking about 5% yields over 10 years or 30 years. Even the inflation of my $SUBWAY sandwich has gone up like 12% a year. Today it was like $20 after tax, when it used to be like $5… 12 years ago. The best way to keep up with inflation of the things that matter, like Sandwiches, is equities like $SPY.
@Biohazard3737 Don't forget to include the very relevant index constituent $PURR to the tally.
China’s datacenter fleet exceeds 24GW across 1,000 facilities, while Alibaba, Tencent and Baidu doubled capex to $20 billion in 2Q26 amid…
Intuit shares have fallen 60.2% year over year as customer acquisition slows, while management says AI is not the cause and expects growth…
Long Treasury yields hit 2007 highs after a weak $70 billion five-year auction, even as the Nasdaq set records and Meta detailed its Muse…
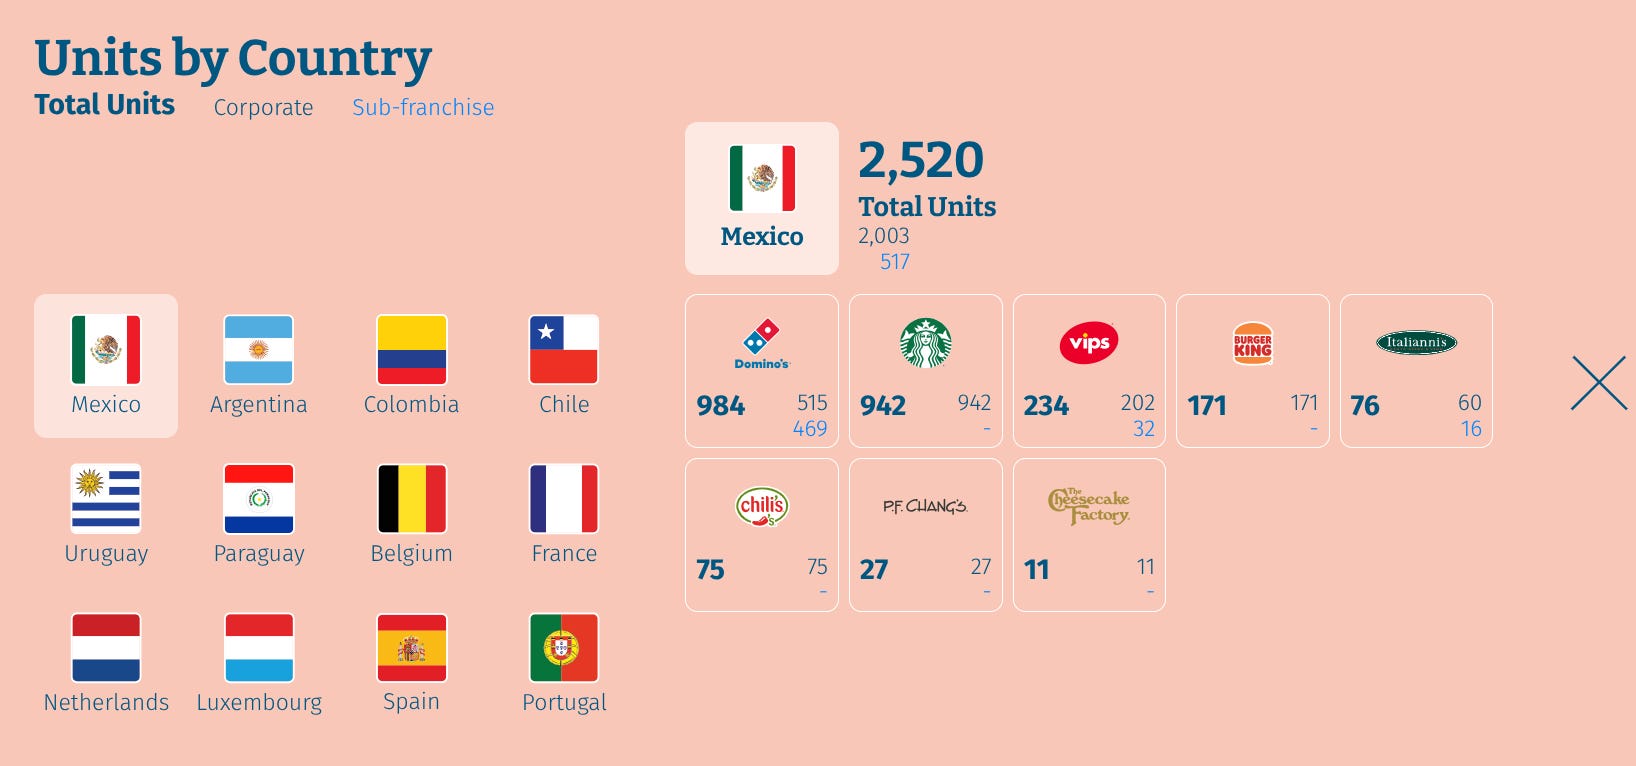
Alsea, Mexico’s Starbucks, Domino’s and Burger King franchise operator, trades at 5.4x EBITDA while funding remodels, Mexican expansion and…
U.S. Treasury yields are testing credit and equity markets, while the discussion also targets recent changes at Glass House (GLAS).
$BBGI
AI think it is more a question of pricing (LLPA grid) for a $FICO scored loan than predictive power and has been for some time. A FICO loan and a VS loan do not command the same price by mortgage buyers, resulting in absurd amounts of money left on the table for sellers of securitized mortgages, and a much higher mortgage for individual buyers
An example of $KSPI continuing to find ways to potentially grow in Kazakhstan.
@SW_Resurgo I dunno, I see lots of very real cases of people doing shit like this. Remember the guy who went all in on $PDD and then had a royal crash out?
@27XVII $CSHR for bitcoin etfs
$GDOT selling off past few days... Looks like deal will get delayed (again) from Q3 close to Q4 close Waiting on UT/AL/Fed approval... consent order likely making it longer than expected Perhaps some investors puking on delayed timeline + stub shares situation I'm still long
$CXW got a new President/CEO today.
$IEHC continuing to expand into new markets and earn new customers.
@srg444 Me looking at $MGM trading at $32 when Osaka asset is worth 💰
Buckley Capital @buckleycapital exited Dave after a 100%+ rally from its average cost — on valuation, despite calling it a great business — and substantially cut Root. The proceeds went to Celsius $CELH and Light & Wonder $LNW.AU, where the Fund calls the street's disbelief in management's $2.0bn 2028 adjusted EBITDA target irrational, implying 150%+ upside.
Why $RFIL today is not the same RFIL of a few years ago…
@WaterworldCapi1 $fds decent short, very big and liquid, not showing deterioration yet, still an opportunity to short into earnings revisions (if they happen)
@ACapitalLP $CODI ?
Energy Transfer's volume growth and data center demand support EBITDA above guidance, potential Q3 upgrades and distribution growth.
 White Star Research
Vista Energy's Q2 2026 production rose 32% and revenue 89% as Vaca Muerta acquisitions expand its Argentine export platform and cash…
 Alan Galecki 4 clicks
Reddit’s DCF values shares at $225, driven by international ARPU expansion from $2.2 to $8.3 by 2035 and 38% operating margins.
What are the most interesting “rumored deal” or “strategic alternatives” trades today? I’ll start: $FUN - 9/22, Jana pushing for sale $ONT - 8/5, strategic review $VITL - 9/17, rumored take private $CGX.CN - 9/23, strategic review/advisors hired $NFG - 9/16, strategic review (Seneca E&P assets)
Caught a nice move in $META as they have executed nicely on Muse. However, I’m curious to see Muse’s retention stats. Muse’s agentic capabilities still seem like a bit of a novelty to me, and sometimes more of a hassle to use than a value-add. $META has also aggressively re-targeted me with ads on my feed based on my Muse activity. While impressive from a business monetization point of view, it makes me leery to connect my email and other sensitive accounts.
Steve Eisman says AI companies are reviving Enron-era off-balance-sheet and circular financing, alongside concerns around Oracle and Blue…
@WaterworldCapi1 @madthunderdome $TLN - Josh Shapiro will privatize it.
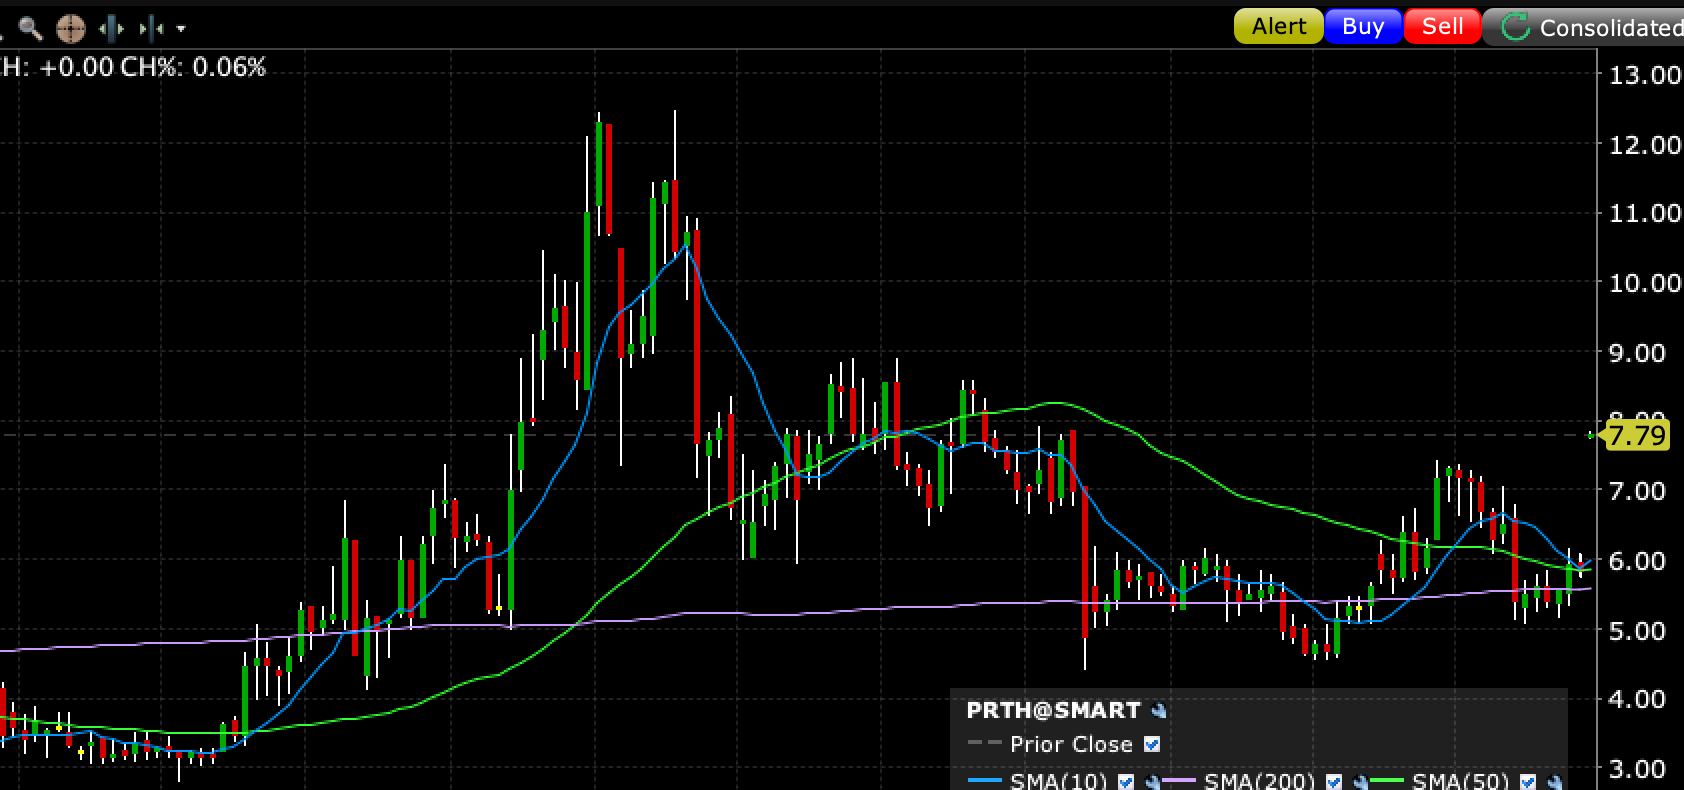
FGPR remains on track, PRTH's management buyout is set at $8.05, and microcap RAVE is described as cheap.
Why is $QURE down so much this week?
There was a small part of me that thought $CROX was going to rip yesterday after Alex Wang wore them at Meta Connect. Didn't happen. Makes me feel a little better about market froth levels
Turtle Creek tripled its shares in Colliers $CIGI, its largest detractor of 2026, taking it from a below-average weight to a top-five holding after a near-50% fall. It blames multiple compression rather than earnings, and the AI-disruption trade rather than the business: brokers still meet clients about office space, and human engineers still visit buildings and construction sites. Founder-CEO Jay Hennick, already a 12%+ owner, bought over $55m of stock on the open market during the decline.
$EVC
This is pretty interesting given betaville doubled down this week on the ft report from last month that NXPI was buying $AMBA
Oklo shares have fallen 77% since October 2025 as commercialization slips beyond 2027, revenue estimates fall and dilution continues.
 Ian Bezek 4 clicks
Remember during COVID, everyone upgraded their backyards and built pools and Leslie's decided to expand past 1,000 stores like this was all permanent? Well, it wasn't. And now now they're preparing to file for Chapter 11. Its lenders are equitizing and taking control of the business. The pandemic literally pulled forward years of pool spending. $LESL
Meta’s Muse reached 2.8 million downloads in two weeks, using AI agents to automate insurance shopping and erode customer inertia that…
Domino's Pizza Group trades at 11.68 times earnings with a 5.54% dividend yield, while half-year results point to an early UK turnaround.
 Philipp Brohl
And so will $AAPL $AMZN $GOOG, they will all attempt to protect their walled gardens. Nothing new or surprising there.
Along with our great guest speakers (outlined below), our Ideas & Networking Conference next Thursday, October 1st in NYC will feature a few investment ideas from yours truly. Over the years, we’ve highlighted some good ones, including: 2023 — $EFXT below $6, now $23+; $FPH below $3, now $4.65 2024 — Alphawave Semiconductor, subsequently acquired by $QCOM at a 70% premium; $MRAM below $6, now $18; $WBD below $9, now $30 2025 — Short $ORCL at $285 Plus, many more ideas along the way. We’re down to just a handful of seats for next week. Click below to register:
JPMorgan says oil prices are increasingly hard to model as market buffers weaken, prompting a scorecard ranking energy stocks by upside…
 Dilantha De Silva
I really like Liftoff $LFTO here. All of the ad tech businesses look too cheap.
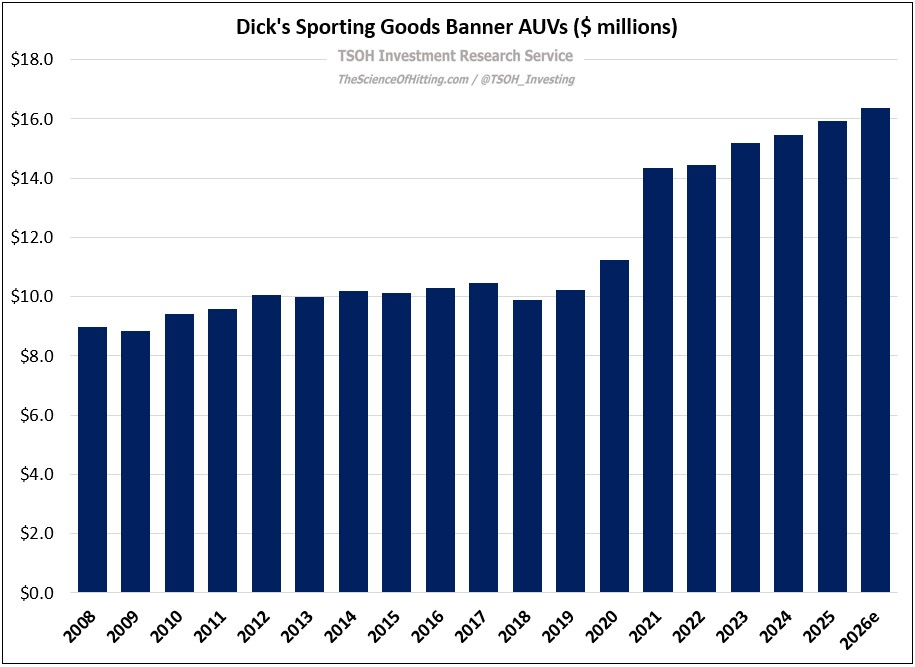
TSOH Weekly Roundup covers Ralph Lauren’s $1 billion distribution pullback, Peloton’s $2,195 foldable treadmill and $800 million…
Gee I love $AMC Apes.
The Howard Hughes Holdings Inc. ($HHH) 2026 Shareholder Meeting will take place next Wednesday September 30th at The Auditorium at 787 Seventh Ave in New York City. At the meeting, among other topics, we will discuss how we intend to accelerate the transformation of HHH to an insurance holding company by dramatically reducing the capital intensity of our Howard Hughes Communities real estate subsidiary, freeing up capital to be invested in Vantage, our insurance subsidiary. HHH CEO David O'Reilly, Ryan Israel CIO, Marc Grandisson Executive Chairman of Vantage, and I will make a presentation and address audience Q&A. Advanced registration for the meeting is required with priority given to HHH stockholders. To register, visit:
IonQ's Q2 2026 revenue rose 287% to $80.1 million, but durability hinges on its $485 million RPO and enterprise adoption for production AI…
 Deep Value Investing
$GRML has been #1 on my short squeeze tracker for 3 days straight, here are the metrics:
See that sudden spike down in $AMC. That is what a naked short selling ladder attack looks like. It is hard to tell when executed in dark pools but this one is so much fun to watch.
Rocket Companies combines Redfin, Rocket Mortgage and Mr. Cooper into an end-to-end homeownership platform, adding mortgage servicing fees…
Not saying this is a “where’s there’s smoke there’s fire” type of situation, but I don’t think it’s great that $LGCY is still dealing with account receivable issues when it wasn’t really supposed to be a lingering one when they first mentioned it in Q4 2025.
$GRML - Continues to be in a short squeeze after the recent Greenland announcement. 900% borrow rate, no borrow in sight, this one might run for a few days.
Activist Starboard Value putting pressure on former spin-off $KNF Been a wild post-spin ride... $40 to $100+ back to $50 Starboard arguing KNF margins are half (!!) of peers and should close the gap by 2029 or sell the business
@SebKrog are you long $opal?
Eckert & Ziegler trades near €12, about 14 times expected earnings, as its isotope supply business expands with radiopharma demand despite…
Am long Prosus $PRX here, shorting $ECNS to hedge china risk. I think $TCEHY is pretty attractive here. In relative terms it's way more attractive than the junk in ECNS at a similar low teens valuation. The discount is very large and Prosus continues to create value with buybacks
Mach Natural Resources' Q2 distributable cash fell to $60.1 million as development spending rose, prompting a distribution cut; its units…
Berkshire Hathaway's succession elevates Greg Abel to CEO and Howard Buffett to chairman, reinforcing its acquisition, buyback and…
 Jim Sloan 4 clicks
Ouster began coverage at Accumulate as lidar revenue rose 56% in Q2, while annual cash burn near $80 million has driven an 86% share-count…
AAON's BASX data-center cooling business targets $1 million to $1.5 million per megawatt, with new capacity and backlog conversion expected…
We’ve been mega-bullish on $PLTR since late 2020. We expected it to come out on top of our SaaS Survival Scorecard. It did. Most software will sit under someone else’s AI window. Palantir is one of the few that can reasonably be that window — the place where work, decisions, and data meet. The edge is breadth plus depth. Breadth: hundreds of kinds of operational work on one substrate, not one app. Depth: it reaches down into the source data layer. A lot of the records still live in old ERP and CRM systems. Palantir doesn’t have to own those databases. It normalizes the mess, puts a shared map on top — objects, relationships, allowed actions — and that map becomes the ground truth. Think of SAP and Salesforce as the ground floor. Palantir is floor 1: where the business actually runs. That creates data gravity and speed. Once decisions live on floor 1, going around Palantir is the hard path. One thing that is not a proven Palantir product yet is refining models on the customer’s own missions — post-training and reinforcement learning on their data, with the customer keeping the weights. That is the NVIDIA Nemotron work. Until recently it was a partnership. Two weeks ago at AIPCon 11, NVIDIA showed it live in its own supply chain. That’s the first public install. Not a general customer rollout. A few months ago the stock was subdued even after strong results, on the fear that model labs would expand into Palantir’s territory. A working Nemotron collaboration takes some of that risk off the table. The risk now is different: Nemotron has to become a frontier-quality model. If it does, Palantir is the best — and probably the only — company positioned to deliver true sovereignty over enterprise intelligence. If it isn’t smart enough, post-training and RL on Palantir’s stack may still not be good enough for enterprises. Watch two windows for Nemotron progress. The nearer one is Q3 earnings commentary — Palantir usually reports that quarter in early November. Management may say more there. The other is the next AIPCon, Palantir’s customer case-study day, roughly every quarter - possibly early December. That’s where live customer proof will show up.
PHINIA’s tariff-free Q3 EBITDA must exceed $132 million to prove organic growth.
 The Sharpe Quest
