
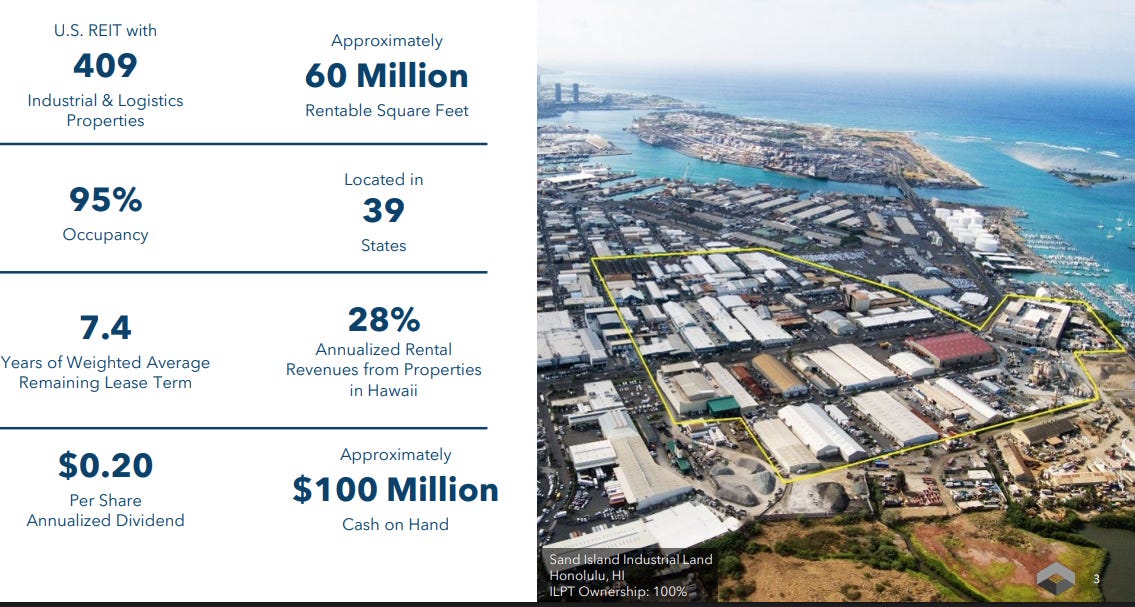
Dance with the Devil (Nasdaq: ILPT)
ILPT’s Hawaii ground leases and US warehouse portfolio are improving, while five-year fixed-rate refinancing eases the debt burden created…
Sector
Everything our editor has picked under this sector, best first.
65 stories
ILPT’s Hawaii ground leases and US warehouse portfolio are improving, while five-year fixed-rate refinancing eases the debt burden created…
Sureste Airports’ 20-airport Motiva acquisition and U.S. concessions are set to lift EBITDA, while shares trade at 7x forward EBITDA.
PUDO’s revenue rose 35% to $5.6 million, but losses quadrupled as administrative costs outpaced growth; $242,000 of cash and ongoing burn…
Kurt Wolf of $PBI. Hands down. No comparison. https://t.co/v6AKggxJD4
Interesting the $AMZN Supply Chain Services announcement has been glossed over by competitor share price action after the initial announcement hit. $UPS has been up virtually everyday for the past 2 weeks + even though they alongside the LTL carriers like $SAIA $XPO are probably the most exposed to competitive pressures or price pressures. Trucking is being supported by heavy admin crackdowns (that will help foster inflation later this year and into next year) and AI demand in areas like flatbed. But LTL and parcel demand is lagging and has relied heavily on price in recent years to compensate for higher costs and volumes....AMZN entrance should pressure both sides for these companies especially domestic players, much less for global routes
DoorDash is framed as an undervalued giant with potential to double.
Newest out: Logista: Still Truckin' $LOG $IMBBY $MO $PM $BTI $STG $HAYPP https://t.co/7p5IFSBnJf
Sidoti raises $PBI price target to $20: https://t.co/d1B7rmSGYC
Eagle Point favors McKesson, AutoZone and other physical-network businesses with durable demand, scale moats and lower disruption risk than…
Just hammering this home. For simplicity's sake, let's use round numbers for 2025: 1) J&T Order Volume Grows: 75% y/y 2) Tiktok & Other Customers Grows: 40% y/y 3) J&T Grows Market Share from 27% in 2024 > 33% in 2025 (disclosed in the 1H25 Report) 4) Non-platform % of revenue goes from 0% > 10% in 2025. All the data-points line up. Takeaway: It can be true that J&T grew 75% y/y, AND Tiktok is slowing to 40% y/y orders growth (and 30% y/y GMV). - Market narrative of Tiktok competition increasing is likely wrong. - Means that Shopee's recent spend is not a defensive move or coming from a weakened position. - In fact, they're pressing harder, while competition is weak (That's just how they operate. They waited to grow Monee loans, until the digibanks started blowing up. That's why you see an inflection in loan growth 2 years ago. Compare that to when Indo digibank NPLs started blowing up, and you'll see the correlation). Included pictures of the math (thanks ChatGPT). $SE $1519.HK
From J&T's 4Q25 call. They called out 1) winning share from competitors and 2) non-platform parcels growing (i.e. not from Shopee or TTS). So perhaps J&T's strong volume growth isn't related to TTS vs. Shopee competition? $SE $1519.HK https://t.co/Jn0UArEo04 https://t.co/pbA0DXJsD6
#Southeast Asia Logistics Where there used to be dozens of players, now there's just two that matter - Shopee Express, and J&T (>60% combined market share). In a high fixed cost business, Scale > Order Density (across both Geography x Time) > Lowest Cost per Parcel = Competitive Moat. Parcel delivery cost has declined -45% over 4 years. h/t @momentumasia. $SE $1519.HK
Shopee's SPX Express reminds me of $PDD's community group buy pick-up point locations. $SE "They are a familiar sight in Singapore. The retired “uncle” in flip-flops, slinging parcels across a housing block in an ever-practical blue Ikea bag. Or an entrepreneurial homemaker busily sorting a makeshift Shopee kiosk beside the lift. They are the human backbone of SPX Express, which now handles most of Shopee’s several billion parcels annually... With SPX Express, 90 per cent of its parcels are delivered the next day in Singapore. In the rest of Asia, almost half of SPX Express orders are delivered within two days." https://t.co/oyQtg6SZ5i
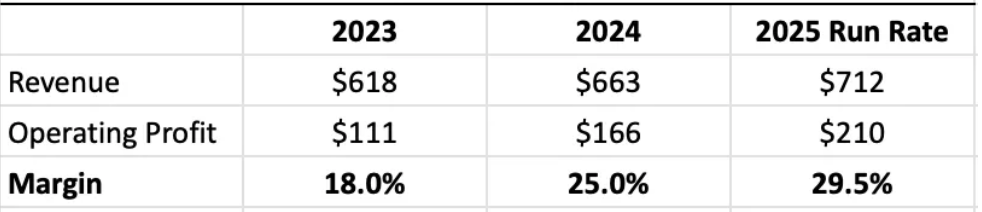
Pitney Bowes trades at an 18% FCF yield, with 25% operating margins, 30%-plus ROIC and plans to return free cash flow mostly through…

Abrdn European Logistics Income, Dream Residential and FrontView REIT returned 19%, 15% and 4% through June, with asset sales and strategic…
$PBI short interest https://t.co/FO86LLy82E
More 3PL Datapoints. $1519.HK $SE 1) External funding raised by 3PLs 2) Lower volumes are leading to negative spiral for delivery workers (who are paid per package). Fewer deliveries per worker = less $ per day = workers leaving for growing 3PLs (Shopee Express & J&T) = more supply / competition of delivery workers = cheaper per parcel costs for SPX & J&T (widening moat). And further erosion of network density for sub-scale 3PLs. https://t.co/n35vONTb7Y
