
Colin King on X
$RAVE down 20%+ today... FY26 results looked good (sales + earnings growth at core franchise business) ...but dispute around CEO comp surfaced (likely driving sell-off) https://t.co/gA7o6lNFzr
Sector
Everything our editor has picked under this sector, best first.
182 stories
$RAVE down 20%+ today... FY26 results looked good (sales + earnings growth at core franchise business) ...but dispute around CEO comp surfaced (likely driving sell-off) https://t.co/gA7o6lNFzr
General Mills Profit, Sales Slip as Turnaround Continues $GIS https://t.co/hCadtnVNZ8
How much would $MCD rally if they changed CEO....capX cycles are not tings investors want to get in front of, and plenty of affordability issues but feels like a new CEO would be given more grace on developing the value menu and reinvigorating the franchisee base then the current team
The franchisee in bankruptcy also pointed to the reduced effectiveness of Wendy’s brand marketing and national promotional strategies. $WEN they gonna stop trian? https://t.co/oFWD9DSqud https://t.co/WyL5iMVgs8
@EmmaStockNotes Purely eye candy: the biggest compounder is Altria $MO at 442,100,000%. Strip Altria out of the average and it drops to about 15,000%, roughly cut in half.
@Tintincapital @valuehurts Has already happened, no? The $WING and $CAVA style restaurant growth stories have collapsed. Or look at something like Vail Resorts, down 65% off the 2022 peak.
Hot Honey no, thanks good buzz for $HRL tho https://t.co/ythkEhbNVK
Yes these Celsius $CELH purchases certainly stood out when we were looking at insider buys this week. They were also buying at similar prices in May. Although those Nov 2025 purchases by the same director that was buying this week (Hal Kravitz) and by their COO were not timed well. Kravitz was previously a Coca Cola executive and has been on Celsius' board for over 10 years. We usually like to see opportunistic insider purchases by independent directors with long tenure on the board.
Diamond Estates Wines & Spirits plans to expand grocery and export sales, invest in six brands, and improve winery operations through FY29.
Greenhaven Road @GreenhavenRoad took a full position in Burford Capital $BUR on the economics of its protein price-fixing book: Burford has put more than $150m of its own capital into the chicken, beef, turkey and pork cases, so it keeps all of the upside rather than sharing it with a client and it controls when the cases settle. The track record behind that underwriting: 285+ concluded cases, 90% won or profitably settled, an 82% return on invested capital over a 2.6-year weighted average life for a 25% IRR. The catalyst is dated — the chicken trial against Tyson Foods, Pilgrim's Pride, Koch Foods and Cargill is set for 2027.
https://t.co/5BLPWc2ddm $ALTO $GPRE
GLP-1 drugs are gaining traction across Asia as Chinese developers advance candidates and Indian generics slash prices, reshaping prospects…
Another 10,000 share buy from the $ALTO Chairman 👀 https://t.co/pPgkaIYFgG
Newest out. Imperial Brands: On the Table $IMBBY $LOG $MO $PM $BTI $STG $HAYPP https://t.co/3r40Fd1sOv
Keurig Dr Pepper’s U.S. beverage growth and JDE Peet’s acquisition support earnings growth as coffee-cost and tariff pressures ease.
 Value Capital Research 1 click
Sometimes a simple chart and pun captures the entire thesis. Just go with the $FLO and make bread. https://t.co/VyIYTaVRF1 https://t.co/lGn8FncexY
@CDInewsletter Nice piece. Absolutely agree on owning ones with strong brands/balance sheets like $HSY over the optically cheaper ones that are dividend cut risks. Also quite remarkable how well $KOF has done, as you mentioned, versus the U.S./Canada peers.
Brown-Forman faces declining organic EBIT and uneven ready-to-drink sales, while U.S.
@fides_capital and sugar $SB
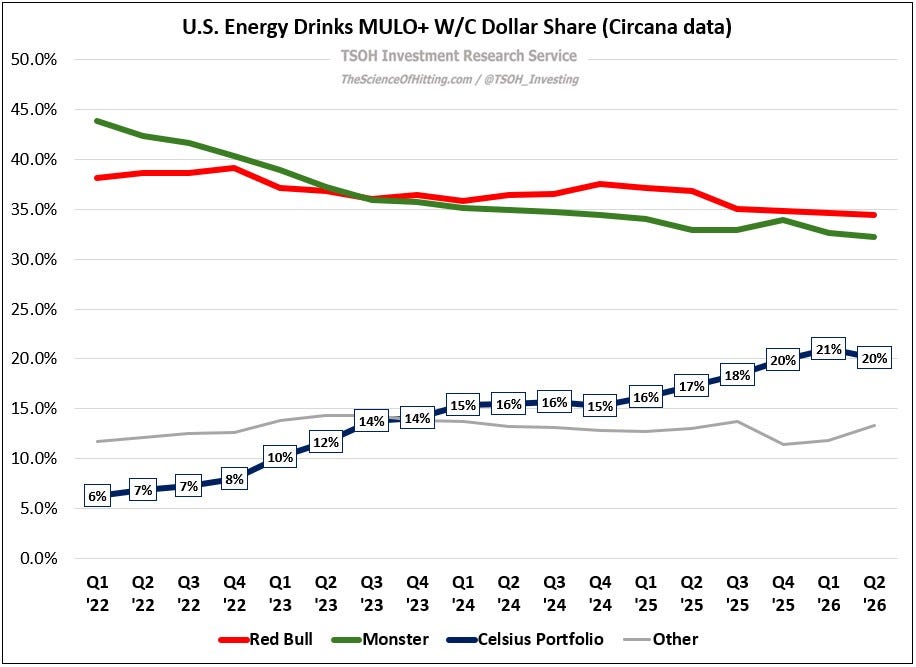
Celsius holds 20% of the U.S. energy-drink market and 40% of sugar-free sales, but its $1.65 billion Alani acquisition complicates…
PepsiCo trades at 16 times 2026 earnings with a 4.3% yield as international revenue approaches $40 billion and North American volumes…
 Steven Fiorillo
Would much rather own $CALM https://t.co/Kvr8sFALPr
imo the risk is not egg price going lower -- its very low right now, and $VITL gets sells into the premium tier. but the company is exposed to corn/soy. At least the last time I checked it did not hedge. Those have moved up a lot in the past few months, so my best guess is that Vital Farms is getting squeezed rn between low egg prices and high input costs. long term, that could clear the deck of weak competitors. Short term, might make for a rough few quarters.
Hershey raised guidance after a Q2 beat as cocoa deflation and improved logistics support margins.
Steven Fiorillo 