
The Neoclouds Series, Part 2: CoreWeave
CoreWeave built the most leveraged neocloud model, stockpiling Nvidia GPUs and renting AI compute from rapidly expanded data centers.
Thursday, August 20
Everything we published on this day.
53 stories — the front page that day →
CoreWeave built the most leveraged neocloud model, stockpiling Nvidia GPUs and renting AI compute from rapidly expanded data centers.
ConocoPhillips’ CITGO claims cover $1.5 billion under Amber’s deal, with a proposed Venezuela settlement targeting roughly $4 billion more.
@Mike10947310 This is the comp set for those looking to do more work. $APX was not always a market pariah and, at one point in time, traded at 5x sales. In the unlisted space, $META bought comp ScaleAI at over 10x revenues this time last year. https://t.co/p91qIkSPgL
Good news for $ALTO and $GPRE! U.S. to end summer blend gasoline requirement early in bid to help curb pump prices https://t.co/K0dqx0sSpV
Coursera $COUR popped a $500m buyback, almost 40% of its market cap. They have the cash for it. The aim is to finally become profitable this year. Only look at it if you don't believe AI will kill the industry https://t.co/Gl1GBorWim
McIntyre Partnerships @Mc_Partnerships considers QuidelOrtho $QDEL a once-in-a-decade opportunity, as the company is reportedly selling its Point-of-Care division to deleverage and fund a share buyback. Note this was written before a potentially thesis-changing Q2. Previously flagged in KEDM Vol. 281.
Moderna's Phase 3 intismeran autogene trial met its recurrence-free survival endpoint in adjuvant melanoma, supporting an asymmetric…
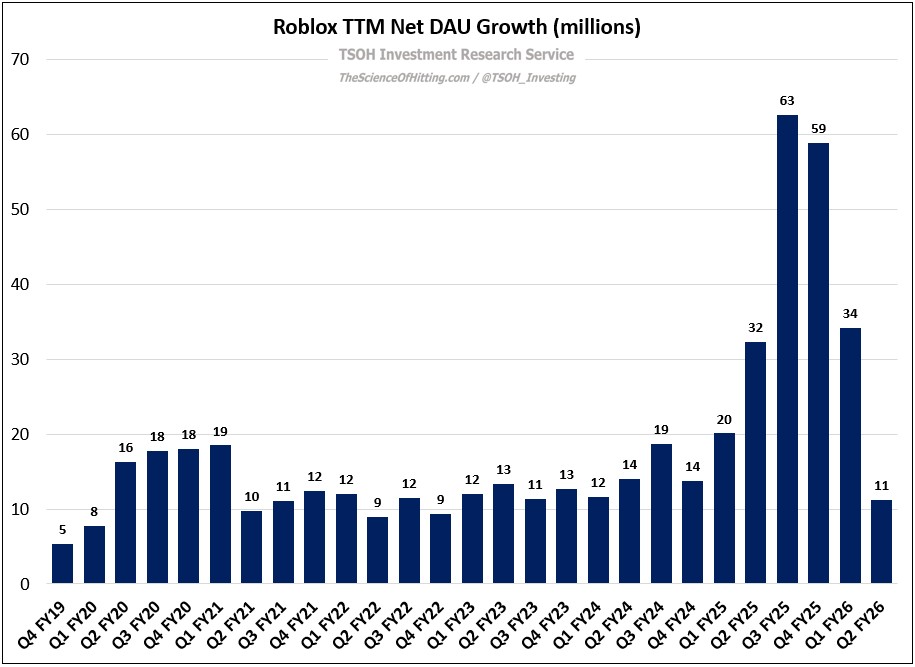
Roblox reached 144 million DAUs and 123.9 billion engagement hours by 2025, but Q3 FY26 bookings are set to fall mid-teens, renewing calls…
June 2026 13F filings show Baupost doubling Genuine Parts ahead of its 2027 split and Ratan Capital making Silicon Motion its largest…
$SGA "the best media company on the planet" And they keep saying that after failing to deliver quarter in, quarter out... https://t.co/gxeMvEC7OM https://t.co/NPOOWjERL4
@HiddenGemsInves $CLPT $NURS.v $ZDC.v $PNG.v $OUST
@HiddenGemsInves @friedoystercult @MikeFritzell FYI- $ISSC is now $IA
Did Moderna $MRNA just cure cancer? Probably not https://t.co/QBodzsTaZD https://t.co/qFRucE9ri8
@BeeliCapital I've been short it a bit since the $XLP runup earlier this year.
@Pray4Equity Growth stuff like this where there's no valuation bottom I set a hard 5% max rule. $RDDT started there and is now at 4.
The $NBIS and $CRWV bulls hate each other more than the average nation involved in a Middle Eastern conflict
$IESC is buying DBM Global from $VATE for $650 Million. Not sure if I am missing something, but DBM's backlog is up 50% year over year, revenue up 25%, and they agreed to sell it for 11x earnings. What?
Speaking of which, $AAP APPsolutely shat the bed (again... And again... And again). CEO speaks a good game, seems to have made the right (big) moves on logistics side, yet... https://t.co/60Z4Tv8OCK
@BillRoman15 It's not that I'm confident $GPN has a structurally better merchant business. But with Genius, they seem to have a solid offering and perhaps more importantly, post TSYS/Worldpay, they have a focused business, whereas Fiserv will take long to clean up, which will hurt execution
@BillRoman15 I'm looking at '27 numbers, which gives $FIS and $GPN a full year of owning TSYS+Worldpay. But whatever metric I look at, fwd P/E, FCF or sales looks ballpark similar for the 3. Which honestly makes it a little hard for me to even own $GPN after the pop over buying more $FIS.
@BillRoman15 So my point is and has been for a while that I don't get why people would go with a massive turnaround in Fiserv, when you can get the same exposure but better fundamentals, mngmt with a track record (can debate if good or bad!) with $GPN + $FIS AND withot paying up
@Adam17609412325 @BillRoman15 Earnings quality legit? Say what? Doing $40/share isn't a high hurdle for $GPI to clear next year (even if they stumbled on the used car side in Q2 and might have a bit of a rebranding headwind in H2 '26).
@THESAVAGEJOHNSO It's the biggest shitco in a sector full of shitcos. Can get the same exposure with $GPN + $FIS at about the same price, but they already focused their businesses, grow MSD and in a much better spot. $FISV can't hold on to neither execs nor customers, why bother
@BillRoman15 Not sure I follow... I also own $GPN and thinks it is great value despite a nice pop...
@Goldridge_Cap $KWY I only think about per share growth. This assumes they are only issuing a small number of shares each year under their executive comp plan. Not additional shares to do acquisitions.
@Goldridge_Cap $KWY Great questions. If they continue to have quarters like the most recent, they will deserve a 20x multiple. If they reinvest cash flows and can grow at 15-20% per year, a 20x multiple seems reasonable. That is why the next 4-6 quarters will be so valuable to review.
@oscarazocar50 $KWY KSX EBITDA of $4.3 million and warranty modified cash EBITDA of $2.9 million. The modified cash number for warranty is really the proper metric. Those numbers were in press release.
$ETD announces a $3.00/share special dividend to quell shareholders while Doug Bergeron's activist efforts escalate. As a reminder, $ETD made the strategic decision to pay almost all of its free cash flow out in dividends (regular + special) over the past few years. The company has no debt and still generates strong FCF despite overall weakness in the housing market and what I would call lackluster execution on its growth plans. Seems like there's still a lot of ways to win here as a shareholder.
@SixSigmaCapital I will believe that $MRNA cured cancer when Bancel and Hoge go a year without selling shares
Worst analyst piece I have seen in years: Litchfield Hills Research puts a 12-month price target of $66 on $FFAI You will be shocked to learn that the small type says: "Litchfield Hills Research LLC has received compensation from the company for distribution and investor targeting services."
$KSCP quarterly results improve but still stink. Now trades for about 1x annualized sales. Note that any valuation metric needs to be taken with a grain of salt here given the heavy dilution. https://t.co/oGq9fRNtNe
They certainly left the door open for that by saying "they expect banks to finance 50% of an acquisition." But, based on previous interviews, I do not think they will do more than ~10 to 20% dilution. They have a nice level cash and should use it. They talked about a $20M upper limit. So, the bank does $10M, $BOSC could spend $5M in cash, and then issue ~1M shares. I am still on the sideline here, but watching. However, if they are not crying wolf again, it's interesting and cheap enough to wait and see for a bit.
Can finally believe that $BOSC will make an acquisition? https://t.co/iMwgVmJvux
$WMT talking about investing heavily to lower prices with the bulk hitting at the end of Q2 and the real impact to be seen in Q3 and Q4....how is that not a negative for $TGT? Consumer incremental weaker according to wmt mgmt and while TGT has stepped over low comps, and created some traction with new assortment at current prices (17x next year on 3% growth and actually declining earnings yoy) very difficult to argue Target is cheap and isn't going to be threatened by new price competition for tighter wallets across WMT and TJX
 PTLO 2026-08-20
Portillo's guidance cut followed a 1.2% same-restaurant-sales decline and 1.9% margin compression, while its $343 million TRA liability…
 KC Research 3 clicks BAC 2026-08-20
Bank of America’s BAC.PR.B yields just over 6% near par, while discounted lower-coupon series such as BAC.PR.P offer better value despite…
 Prakhar Agarwal, CFA 1 click
Contrarian view: $MRNA raises equity in next week. Bullish. No equity raise in the next 2-3 weeks? Very bearish.
It is simple: $NVDA is using vendor financing to avert margin pressure and market-share loss. https://t.co/IlD9IHVhP8
NBIS 2026-08-20 Nebius posted 454% revenue growth and a 41% EBITDA margin, while Meta’s $27 billion agreement supports its AI infrastructure backlog.
 The Quality Growth Investor 3 clicks TEM 2026-08-20
Tempus AI's diagnostics and data businesses grew Q2 2026 revenue 19.4% year over year, with FDA approvals, expanded tests and pricing aimed…
BHP 2026-08-20 BHP expects copper to generate over half of FY2026 EBITDA and plans a 40% production increase by FY2035 after profit, free cash flow and…
 On the Pulse 1 click ANET 2026-08-20
Arista Networks posted Q2 2026 revenue of $3.036 billion, up 37.7%, with AI fabrics and data-center networking driving higher EPS estimates…
 The Curious Analyst 1 click SA 2026-08-20
Seabridge Gold's KSM gold-copper project could re-rate on a joint venture, 2027 feasibility study and infrastructure progress, with gold…
 Redfern Research
Fed, Alabama regulator enter enforcement action against SouthPoint Bancshares $SOUB | S&P Global Market Intelligence - @colarion had this pegged https://t.co/2tHGECNUTo
$OTTW https://t.co/PCj3SfS5yv https://t.co/8TdjhoKoa5
@Ron284Ron At 35% of what $CNAF book value used to be…☠️

El Al trades near 2x EBITDA after wartime near-monopoly profits, with $1.3 billion of net cash and owned aircraft weighed against…
El Al’s wartime near-monopoly has produced net cash, owned aircraft and a 2x EBITDA valuation, while regulatory obligations, customer float…
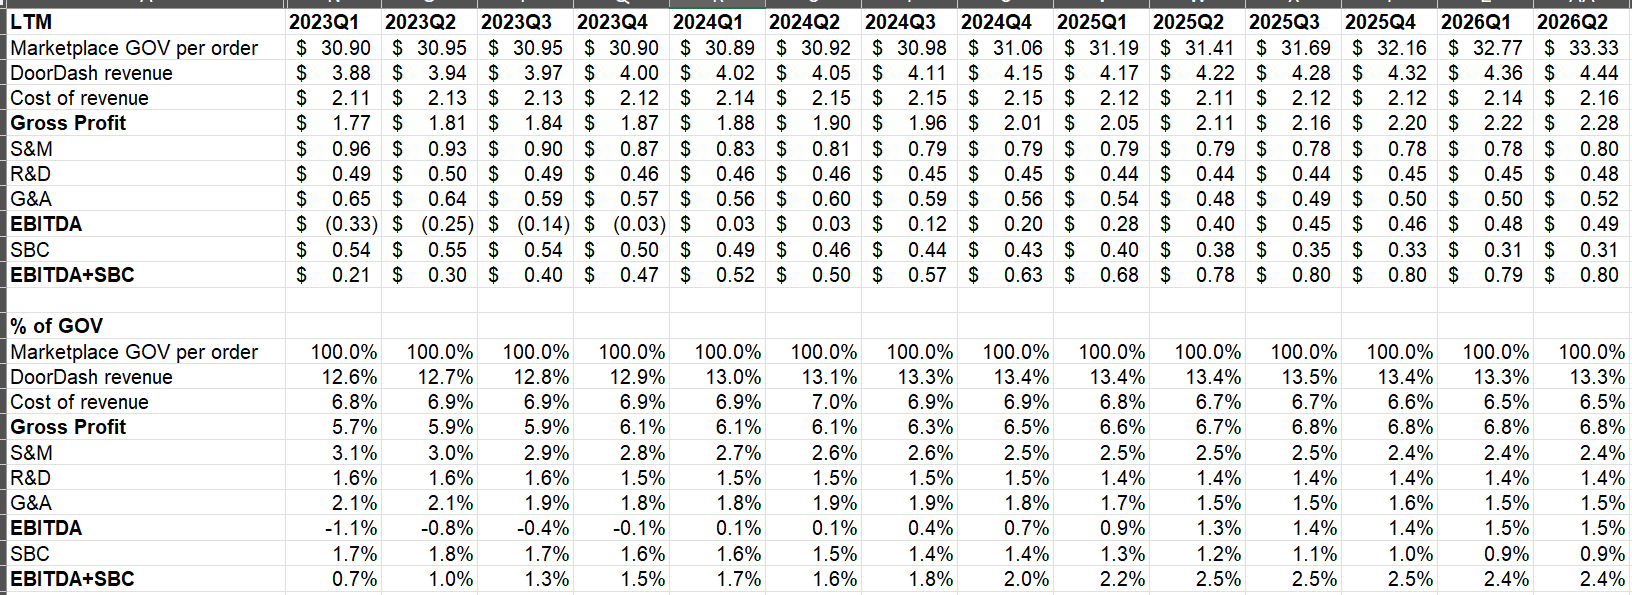
Instacart’s per-order unit economics provide a benchmark for assessing DoorDash’s LTM profitability and operating model.
@ragingbullcap $PBT interesting here to. Merging with royalty acres/surface interests owned by affiliate of the operator, converting to a C-Corp. Softvest is once again the architect as with $TPL https://t.co/acWX95uQQI
$XGN bio pharma revenue increased 40% yy in Q2 hitting a quarterly record. What we also love is that the stock trades for 2.5x sales vs a comp set at 10.3x. This is in advance of launching testing for Myositis which is another connective-tissue disorder that requires early diagnosis to treat and prevent serious organ damage. Rheumatologists have requested a calibrated Myositis test w/ 15x more frequency than any other test because the condition is so critical to rule out. Only $XGN will offer this and its coming in the 1H of 2027, maybe Q1 and the additional cost of launch are already baked into the cake.
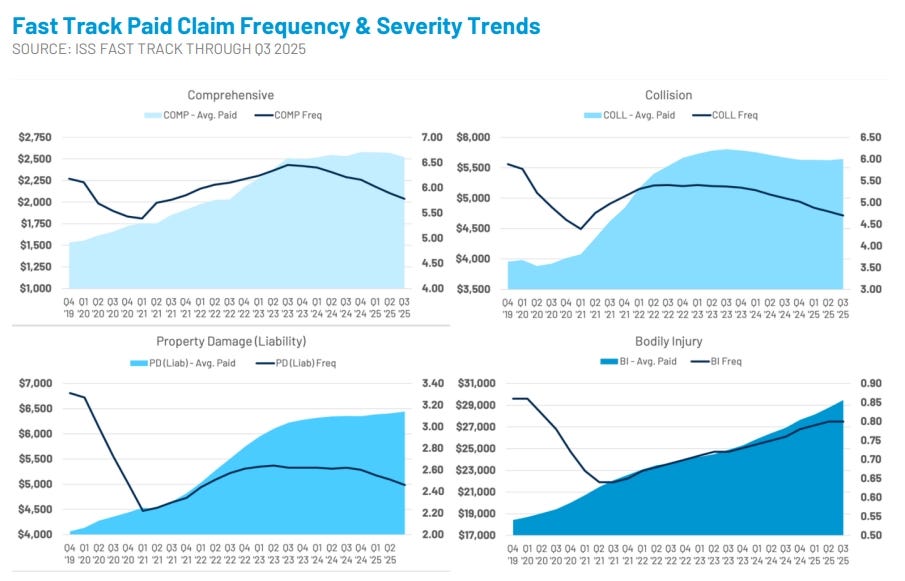
CCC, the dominant auto physical-damage claims estimator, connects 27 of the top 30 insurers with 31,000 repair shops as takeout rumors…
Verra Mobility's new seven-year Avis agreement replaces a customer worth over 10% of revenue on materially worse economics, exposing…

