
Adobe Inc.
Adobe’s 11x P/E reflects AI disruption fears, but its creative standards, product bundling and Firefly monetisation support the case for…
Thursday, August 13
Everything we published on this day.
54 stories — the front page that day →
Adobe’s 11x P/E reflects AI disruption fears, but its creative standards, product bundling and Firefly monetisation support the case for…
$BSP https://t.co/zo5oqwTXa3
Adobe’s valuation fell from 70x earnings in 2020 to 11x as generative AI challenges its creative-software franchise; product standards,…

Riot Platforms has 241MW of contracted data center capacity, including a 191MW, 20-year $9.8 billion frontier AI lab deal, as it shifts…

WillScot Mobile Mini returned to revenue growth in Q2 2026, raised full-year targets and invested $114 million in fleet capacity for data…
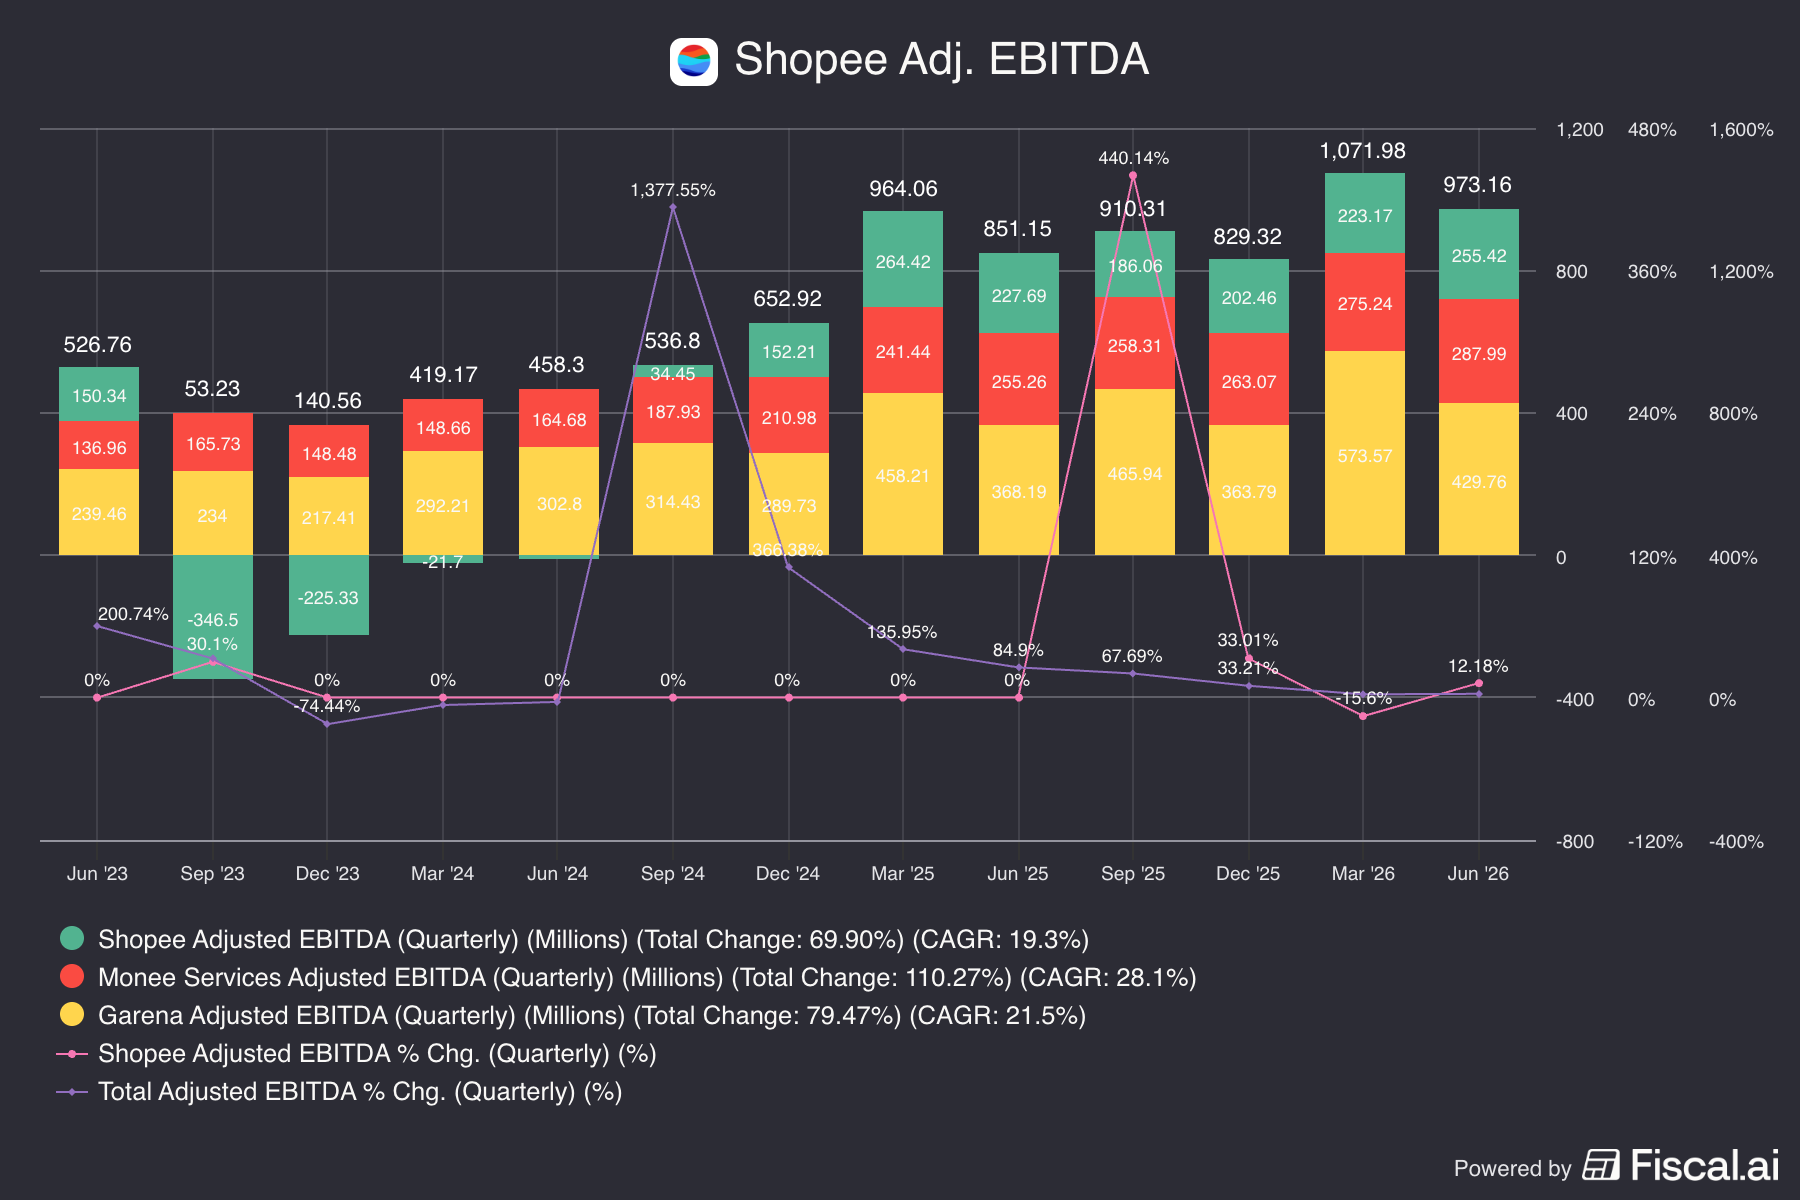
Sea Limited’s Shopee lifted adjusted EBITDA margin to 0.7% in Q2 2026 as revenue rose 48%, targeting 2-3% through fulfillment efficiencies…
All great, but $SKM one of few public proxies for Anthropic is not moving in tandum, any experts could enlighten us on the situation? https://t.co/P5LqpCkYXH
@Junior102515457 Not really. $PBI shifted the volume to an upgraded facility. PCI is abandoning the region.
Agreed, this was PCIs largest market.... this is an enormous win for $PBI ... I think PCI was might be the one's that were targeting Pitneys customers. Definitely didn't work out the way they thought it would. PBI should get a lot of customers back. PCI handles over a billion pieces nationally...
HUGE news for $PBI this morning...... major competitor PCI just filed a WARN notice. Permanent closure of facility in Florida. I suspect the Indiana, Texas, and Massachusetts sites are ... not for long. VERY bullish for PreSort operations... https://t.co/WBVUUQugne https://t.co/MXBts3BMEt
I don't agree. $GME could have easily put in place a 10b5-1 program that would allow them to repurchase shares through any sort of blackout period. In-fact - I expect they did exactly this. https://t.co/V9ZJuwYaen
Short sellers did their best (worst?) to try to tank $ALTO over the last couple of months with short interest rising from a million shares short to 4 million shares and now 6 million shares despite the company proving that they are now profitable in every quarter of the year... https://t.co/apt6gE0VYM https://t.co/7y50j4h1bn
JinkoSolar sold control of its Florida solar plant to a Delaware entity run by China’s “Sun King” family, potentially sidestepping new…
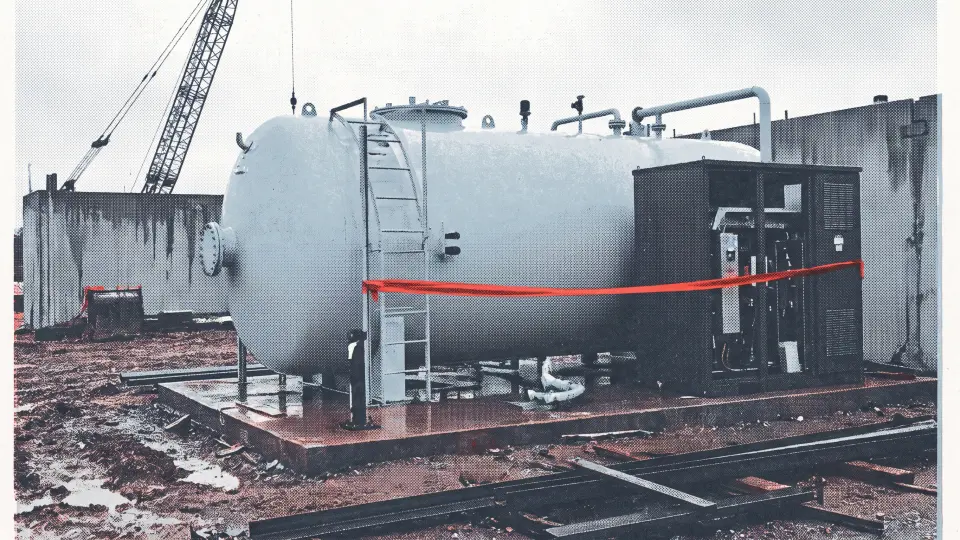
Nebius told investors its Vineland data center was on track days after officials halted unpermitted Bloom Energy fuel-cell and LNG-tank…
Long Cast Advisers is pitching Pro-Dex $PDEX, saying Zimmer’s mBos robot launch and the contingent value rights from its Monogram acquisition could drive an exceptional transformation in operating cash flow, justifying a substantially higher corporate value. https://t.co/eiJmjA9OKP
SEACOR Marine $SMHI has launched a strategic review, looking for value maximizing transactions – tough, clearly preferably a full sale. This comes after a ton of pressure from Pointillist (the largest shareholder), which argued SMHI’s market cap massively undervalues a fleet. Their thesis: the offshore cycle has fully recovered, but SMHI’s equity still trades at well below its $22/share broker appraised value. Seacor remains weighed down by high interest costs, G&A expenses, and subpar utilization, forcing asset sales to bolster liquidity. The premium PSV fleet alone should be worth ~$11/ share, with FSVs and Middle East liftboats pushing embedded value to $15/share+, vs. today’s price.
Uranium Royalty $UROY completed its (asset) deal with Sweetwater Royalties. This was quite the big deal for UR, not only in size ($1.9bn in EV and roughly $1.1bn in equity acquired, vs C$490m EV and C$600m market cap for UROY), but also because it will drastically reduce exposure to just one main commodity. The company recently listed on the Nasdaq and delisted from the TSX. In short, a transformative acquisition (trona is an interesting commodity) which should help the valuation. BB is not yet showing the correct financials, and coverage is picking up.
If PE wants to own SW, go get $FIS. Sticky as fuck, could cut employees in half and shit is already levered to the tits and ready to go!!
Not saying I told you so, but I did tell you this shitco was a better shitco than $FISV (ignore my posts about $FOUR, that's just a temporary 'mark to market'/'ya, so that's just your opinion man, it really ties the portfolio together'
Mkt feeling frothy, we're approaching 6xFCF $gpn https://t.co/v8JZBAHFfU
If limited to large caps, Verizon looks kinda interesting here? $vz Revenue accelerating into H2 (4% in Q4?), FCF ramping, '27 guided to be better than '26, yet analysts expect sub 2% rev growth next year? Google contract signed (>$1B rev), others should follow.
Many. High level, the $AIRS quarter wasn't as good as hoped, but certainly not something that warranted the kind of response it received. Top of the funnel interest in lipo slowed in June/July. I have my own thesis on the potential impact of the world cup, given the shift in consumer interest in that procedure towards the latina community over the past 15-years. Only time will tell if that's right. Either way, the business is stable and now oriented for growth. Adding new procedures (eye bleph and alloclae) significantly expands $AIRS ability to serve the GLP-1 crowd. My expectation is we'll see the bank deal completed before they report 3Q26 and that could coincide with the announcement of site expansion in early 2027. The growth opportunity here remains monumental. $AIRS has massive inherent operating leverage to improved site level utilization. There was some fast money and retail involved here (clearly!), but this is about the company improving the marketing funnel in absolute lead generation and conversion, driving site level utilization, and expanding on a de novo basis. That's the recipe and obsessing about whether growth should have been 2-4% higher for 2Q26 in that context is irrelevant. This is a business that can be 3-5x the size and still have a runway for growth.
Did $FFAI just post the worst gross margins of any EV shitco? $1.35m revenue / $11.54m cost of revenue https://t.co/8quolRi1gN
$NU strong report imo. LFG. I'm long and may add. https://t.co/8sNxzwFADh
$INTU strong rebound. Not a zero like the bashers said. I'm long, covered by Jan 400 calls. https://t.co/yuYhxU6OIa
@OnodaCapital $OPEN deserves all the skepticism you can muster, especially because its promoter is a liability. But this structure has been used successfully by other companies, no? I thought $RH did something similar ~5 years ago?
$PSFE results: good enough, not great. https://t.co/ilpWevfAd5
Good report from $NXPL. Losses cut drastically, will flip to profits soon. I remain long and may add. https://t.co/6CIYQea0JU
It should be no surprise that as the reality of commencing operations gets closer, investors are less doe-eyed about $EVTL https://t.co/4Q8ETMvQLM
If you ever owned recently acquired $CRAWA, you might also follow $PKOH (family ties). It’s is up 138% this year. Logistics and supply chain solutions is a great trend to follow. So many stocks have seen their valuation re-rate, in what’s typically been a low P/E industry https://t.co/6xaCGQf5nF
Playing out nicely for $KLNG. Hopefully, we’ll eventually be saying the same on $SIF pullback opportunity. https://t.co/0u7pxLVft4
Testing out our new live "beta" earnings call feature at @InfoArbMonitor via $TGEN call. Loving the feature, but I'm biased :).... Looking forward to $KLNG at 10:00 AM https://t.co/ILoEJn3GLW
@Uzocapital Thoughts on $TTD here?
What price would you guys buy $LFTO at? https://t.co/KotrBWwRVj
Me seeing $HOG up 5% after a massive insider buy the market missed. https://t.co/PaS59DADNh
Growth hogs slamming $LFTO down 10% as Liftoff says they also won’t have sequential growth because Q2 was so good from model breakthroughs and The World Cup. Growth hogs and slobs still price Liftoff higher than Entravision even though Liftoff is guiding to 35% annual revenue growth and Entravision is in the triple digit range. Growth hogs are not to be trusted around your wives folks.
Wow, $LESL 1L TL trading ~20 cents Operating picture much worse than expected and they just withdrew guidance Restructuring inevitable at this point https://t.co/nv7uYbpOVn
Workday employees learning their new owner's first workstream will be headcount reduction $WDAY https://t.co/AIvTDIXGdo
who is financing an LBO of $WDAY at this valuation....one of the more baffling capital allocation decisions across the spectrum I could imagine. Seems like a very levered play to try and change marks on private credit and then move to open refinancing or the IPO market to dump all the bags and use "WDAY" as mark/proof. Whole thing is sketchy.....
*SILVER LAKE IN TALKS TO BUY WORKDAY: REUTERS ~$43B enterprise value...would be one of the largest software buyouts EVER! $WDAY
Some interesting credit stats: > Hyperscalers are now ~20% of the entire 30-yr IG bond bucket > ~40% of all 30-yr IG deals this year came from hyperscalers > $AMZN and $META each make up more than 5% of long-end bonds individually
@ShmuelLon Good. That was my intention. It was less about the merits of $EVC in the future and more about recognizing that 1) we have to think about growth properly; and 2)we have to guard against thesis drift.
Is $EVC is a classic case of thesis drift for its investors? It was all about sequential hypergrowth (with a supposed SOTP margin of safety). Mgmt said Q3 will be below Q2. Now the thesis is about strong year over year growth. What happens in a few quarters when year over year growth is gone, or is low single digits? Is this really a seasonal business? For me it was a small position due to the nature of the situation. Q2 growth was lighter than I expected so I was selling after hours and have fully exited.
Citi $C Expands Customer Engagement and Commerce Media Capabilities With Addition of Kard - https://t.co/A0DL3zGdiS
$BAFN registers all the $3.50 stock. Document https://t.co/S4JoztfY0r
Bingo. Executive order just signed to go into effect soon...domestic suppliers WIN. $MOB being FCC exempt, Blue UAS, and supplier to domestic OEMs like $TDY means they also win. And great quarter too...business is starting to inflect. https://t.co/Wj5fOsJxvh
How important is precise autoimmune diagnostics? How big is this market? How fast is it growing? $XGN, 2x sales. https://t.co/Q54JkIDLkQ https://t.co/a2FvxREDnN
$XGN remains a top holding for us. Even after the big move higher post a beat and raise Q2, the shares trade for a material discount versus comps. The discount is silly. Especially when we consider that they are launching a new marker for Myositis. XGN tells us that Rheumatologists are BY FAR requesting a precise diagnostic for Myositis more than any other condition. The reason is because Myositis is treatable if caught early, but problematic if not. "this is the #1 asked for product amongst our rheumatologists clinical base... it's not even close to the #2 asked for offering" $XGN trades for 2x 2026 revenues. Comps go for 10x.
Kenneth Dart (Candle Lake) is offering 695 SEK per share in Evolution $EVO after crossing the threshold that triggers a mandatory takeover bid. Acceptance period is scheduled to run from August 17 to September 15. After that, Dart can continue buying shares. https://t.co/lexNUjdqSZ
So now $SMCI is part of the agentic & SpaceX capex trade? https://t.co/BMrEvmCbQj
Macy’s and Kohl’s face renewed short cases as their recent reratings ignore fading store-refresh gains, credit-card earnings exposure and…
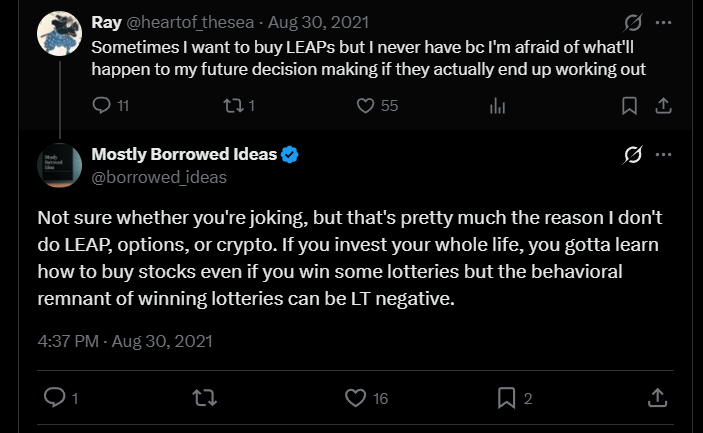
Options strategies will manage portfolio risk after Meta, Alphabet and Amazon calls drove gains, while Lululemon LEAPs produced an 80% loss.
Zoetis’s U.S. companion-animal revenue fell 6% as dermatology competition drove rebates and discounts, pushing full-year net pricing to…
Copart faces a near-term lift from pricier AV repairs and total losses, but shrinking accident volumes could eventually force its…
