
Odd Diligence on X
"The next wave of AI is robotics—and it starts with autonomous vehicles." $CCXI https://t.co/21o6xQV8zH
Tuesday, August 4
Everything we published on this day.
25 stories — the front page that day →
"The next wave of AI is robotics—and it starts with autonomous vehicles." $CCXI https://t.co/21o6xQV8zH

SpaceX plans to build exclusively on Nvidia and lift compute toward 10 GW by end-2027, while Musk says AI memory demand is rising 200%…
@kevin_smith45 $LLY
@dalibali2 $META $AMZN $HONA $PM $COF $GSHD $523A.JP
@TrungTPhan $BSP will end in tears. So obvious.
Stevanato's 8% organic Q2 growth and 21% adjusted EBITDA growth came with a modest FY 2026 guidance lift after the Balda divestiture.
Nvidia’s $2bn Marvell investment is not a simple endorsement $MRVL is one of the few real DSP alternatives to Broadcom. Nvidia lacked that lever — now it has influence. Marvell has also struggled in custom AI silicon and networking (Trainium 3 was a clear disappointment). The path of least resistance becomes designing compute that attaches to NVLink rather than building independent high-speed I/O. On scale-up, the field is largely NVLink vs Broadcom’s Ethernet camp. UALink was the alternative; Marvell was the key switch name. Once Marvell is aligned with Nvidia, UALink’s prospects as a true independent standard weaken. Three effects at once: 1) DSP influence, 2) custom ASICs pulled toward NVLink, and 3) a potential NVLink competitor blunted. We stayed on the sidelines. Not every Nvidia partnership is automatically bullish.
Why we exited $FIG AI coding agents and prompt-to-UI tools are changing the design workflow faster than most expected. Platforms such as v0, Lovable and Claude Design can already take a team from idea to a working interface without a traditional design file in the middle. Figma has added its own generative features, yet these have largely been layered on via external model APIs rather than a full re-architecture around AI-native workflows. Newer entrants were built for this environment from the start. In public interviews the founding team has consistently struck a defensive posture — essentially arguing the existing franchise is secure — rather than showing the urgency of a company prepared to disrupt its own model. That mindset is rarely a positive signal when a platform shift is underway. After several quarters of waiting for a more compelling response, we exited the position.
Why we exited $CRSP and kept $TEM AlphaFold solved the backend of the problem — predicting a protein’s 3D structure from its sequence. The harder frontend problem remains: knowing which protein or pathway is actually worth targeting. Most complex diseases are still poorly understood at the causal level. That distinction matters. The next real breakthroughs look more likely to come from AI-native groups that treat large-scale compute as the primary engine, in the same way OpenAI and Anthropic approached language before the ChatGPT moment. Public investors may only get clean access later via secondaries or IPOs. CRISPR sits on the earlier-generation side of that divide. Tempus is closer to the compute-and-data native side — building models while assembling a genuine clinical data moat. That is why one was exited and the other retained.
$PFHO left for dead (again) even though it’s earning ~$1m/year. Trades below cash. https://t.co/gaeXllgPDa https://t.co/g9DBeyd1t7
$ALTO $GPRE Ethanol Blend Rate Shatters Record, as Cost Advantage Soars During Iran War https://t.co/SLJHUejmfX

Floor & Decor’s same-store sales improved to minus 2% in 2Q26, while $45 million of tariff refunds lifted profit and funded pricing,…
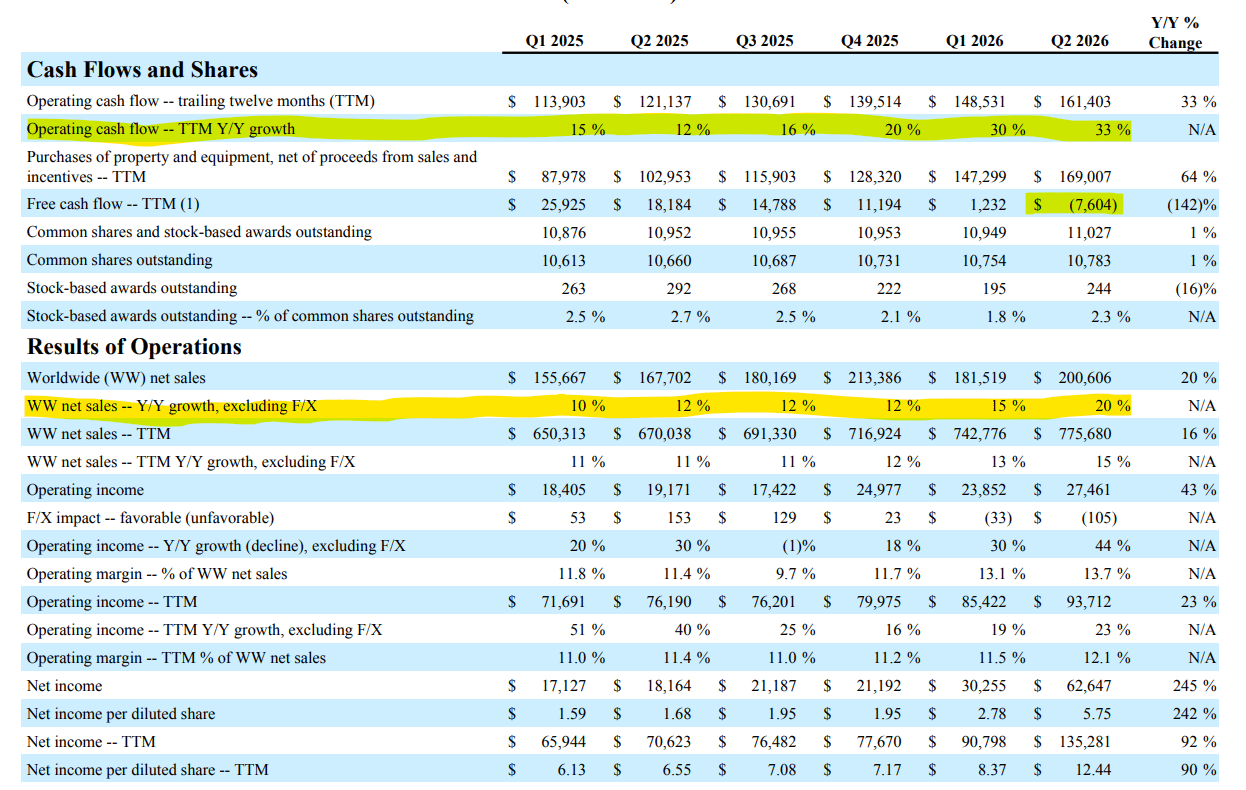
Amazon's AWS growth accelerated to 37%, while $220 billion of 2026 AI and AWS capex pushed trailing free cash flow to negative $7.6 billion.
Xerox is pitched as a cash-generating managed-decline value play, with debt, activist interest and short interest setting up a potential…
Large insider buy over at $HOG 40K shares, or almost $1M in open-market purchases
Watches of Switzerland says Roberto Coin, e-commerce and pre-owned watches generate 24% of revenue, as private equity interest follows its…
$WYNN shares are trading at January 2007 levels despite significant EBITDA growth. The stock has been rangebound for 7-8 years. Valuation compression has been monumental. We all miss Steve talking about his Lagoon and other matters. Perhaps the opening of the Al Marjan casino in about 13-months will be the catalyst for a massive breakout. I think they've set an extremely low bar for that property.
Big gap higher pre-mkt for $W. Furniture names in general have been ripping the past 3-months. QUIETLY. 4+ years of brutal housing market headwinds and these businesses have been grinding away, generating cash, buying back stock, preserving margins. Easy comps + the potential of an upturn in housing velocity make it a good recipe for longs with valuations that remain notably cheap relative to mid-cycle EBITDA. Look at some of these 3-month returns: $BOBS: 64.8% $W: 35.8% $BSET: 34.1% $WSM: 33.2% $HOFT: 21.4% $LZB: 18.5% $ETD 12.2% There's plenty of juice in the group with a sustained upturn in home furnishings spend after the post-COVID19 crash. $WSM is on our Buyback Outliers list. I own $BSET, $ETD, $BBBY
Interesting look at who made money on $BSP's take out of #airtable. Some people didn't do great here, but a return of funds is always better than nothing in VC land. I'd love to see the original deck on Airtable from 2013 and what this business has morphed into.... https://t.co/D5PMxk25bF
Dogged determination by Stilwell & Co on $PFBX. Seems just a matter of time now. https://t.co/LAh5oS4BdN https://t.co/E0Uz5QxwnF
Really starting to like this $XGN mgmt team.
Good numbers from Broadridge $BR. Stock was stupid cheap a few weeks ago, hit 14x trailing eps for a capital light monopoly
Bought $CTRI ~$22-$22.50 into this post-earnings sell off. Margins were disappointing, but $CTRI is growing nicely given the tailwinds in energy and utility services. Margins should follow in time from greater scale & pricing power, and the balance sheet is vastly improved.
Floor & Decor’s same-store sales improved to minus 2%, while $45 million of tariff refunds lifted second-quarter gross profit and operating…

FICO's fiscal third-quarter 2026 revenue rose 26% year over year but missed consensus, and shares fell about 24% after earnings.
