
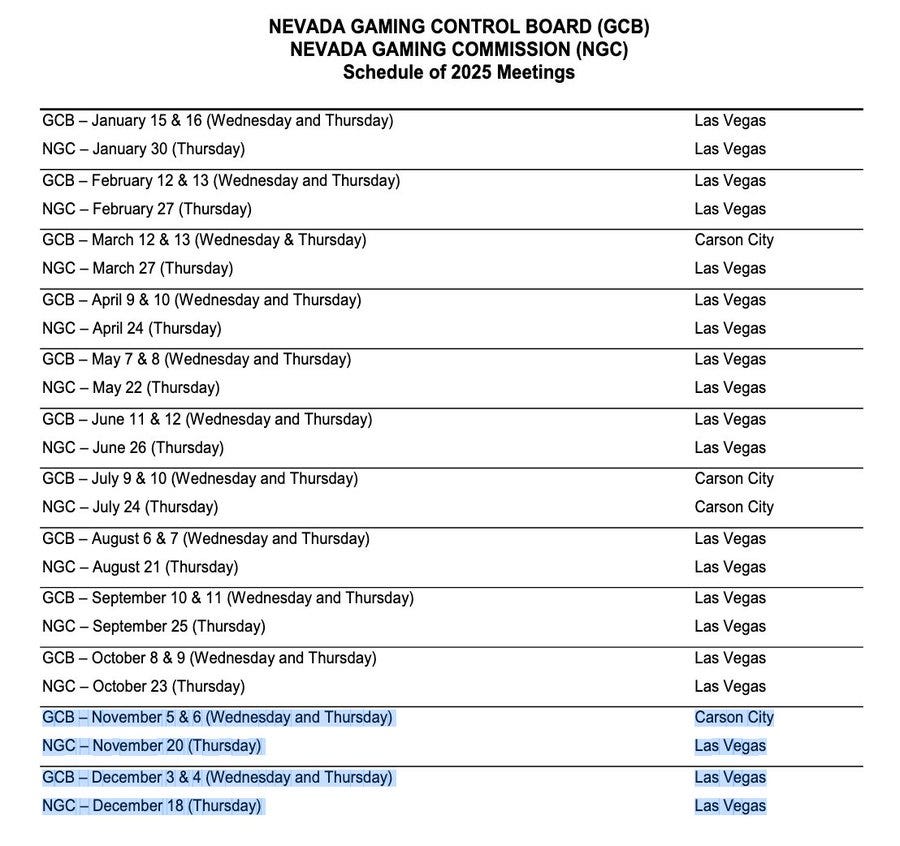
No Downside Merger Arbitrage with potential 58.7% IRR if deal closes
Evolution’s acquisition of Galaxy Gaming awaits regulatory approval, with a claimed 58.7% IRR if completed and a $5 million termination fee…
Sector
Everything our editor has picked under this sector, best first.
199 stories
Evolution’s acquisition of Galaxy Gaming awaits regulatory approval, with a claimed 58.7% IRR if completed and a $5 million termination fee…

Braemar Hotels & Resorts initiated a sales process and faces a gross asset management contract.
$LYFT vs $UBER https://t.co/jsAZEak1pQ
$BKNG vs $EXPE https://t.co/zzuhmvsl0k
Pebblebrook Hotel Trust preferreds yield 8.2% to 8.4%, supported by a hotel portfolio trading at a claimed 40% to 55% NAV discount and…
@Vienna13Capital @RicksCEO @orchardwealth69 @BradleyChhay BMB alone according to the CEO is 65 - 85mm and generating no EBITDA.. That's like 20-30 pct of the market back to you.... $RICK
@WBPetersen @RicksCEO @BTaylorUSA @orchardwealth69 SSS in the clubs have been flattish.. They are closing BMB units which has been driving the lion share of negative revenues. Huge RE value in BMB too. New clubs purchased / open/ central city should start ramping soon too. Lines should cross on rev by end of year IMO. $rick
$rick is trading less than value of RE/ PP&E (412.6m gross). Given the big locations in big cities my guess is the market value of this could be > 600 mm. RCI has total debt of ~200mm leaving net RE of 400mm. curr. mkt cap is 308 mm. @RicksCEO @BTaylorUSA @orchardwealth69
@oraclealexx @qlixontop @RicksCEO I think $rick has been public since 1995 or smthg. The opty to trade bmb/ re for buyback in future earnings diwn here is tremendous or more m&a…..
@qlixontop @marginofdanger @RicksCEO Bmb RE worth close to 100 (assets making zero). Re held for sale I think co. said ~30. Tootsies worth 125? Ricks nyc 50? That’s 300 right there. Scarlett’s ? 50+ other clubs many are in major metro areas. This thing is worth more dead than alive now. $rick Ask @RicksCEO
1/ Odd day. Sen. passes bill on housing and RESTAURANTS. No tax on tips/ no tax on overtime pay. Powell also not ruling out cuts and restaurant stocks ripping. Overhang at $PAR has been strength of their end market / customer. Today everything got better... @SavneetS @PAR_Tech
$EXPE has always been a much slower grower than $BKNG, won't be surprised if it's a fav pair trade of hedge fund (long booking, short expe). Over the years though Expedia has been going through internal changes, sold some businesses (Egencia to AmEx travel and few other sites), went through a technology transformation for internal sites (Expedia, https://t.co/ap3OIandej, Vrbo). 50% improvement in operating margin since 2019. But not as profitable as Booking (operating margin at 12% vs 32% for bkng). Mainly a US focused player (unlike bkng) with a very strong B2B segment that's growing mid teens and about 30% of total revenue), now looking to expand internationally. To be seen if that would drive higher margin given the much fragmented hotel market internationally vs US. Bkng on the other hand seeing revenue growth slowing down to high single digit and mid teens eps growth with margins declining since 2019. Expedia needs to show higher top line growth but possible still delivers mid teens eps growth. Travel is cyclical but these OTA are very robust, they saw revenue growth even in the financial crisis, as more ppl look for deals. AI is an unknown, Expedia is embracing it. Finding a hotel with the right deal is not same as getting an answer to a question from LLM, distribution/platform should remain valuable. Interesting to see how the pieces fall for Expedia, PEG < 1 and these multiples should atleast provide downside protection
More event-driven news for another Value Sit Portfolio name this AM, with Dalata $DHG $DAL #DHG #DAL up ~3.7% on news of take-private bid ... https://t.co/iYj58zAdn4 https://t.co/zuNEdRJLnI
@RicksCEO I’ll take your deal if we can add a zero to your 6 mm of ebitda added a year. 60 sounds a lot better ! $rick
@RicksCEO Maybe if you did 500 of ebitda, we could afford that one… $rick
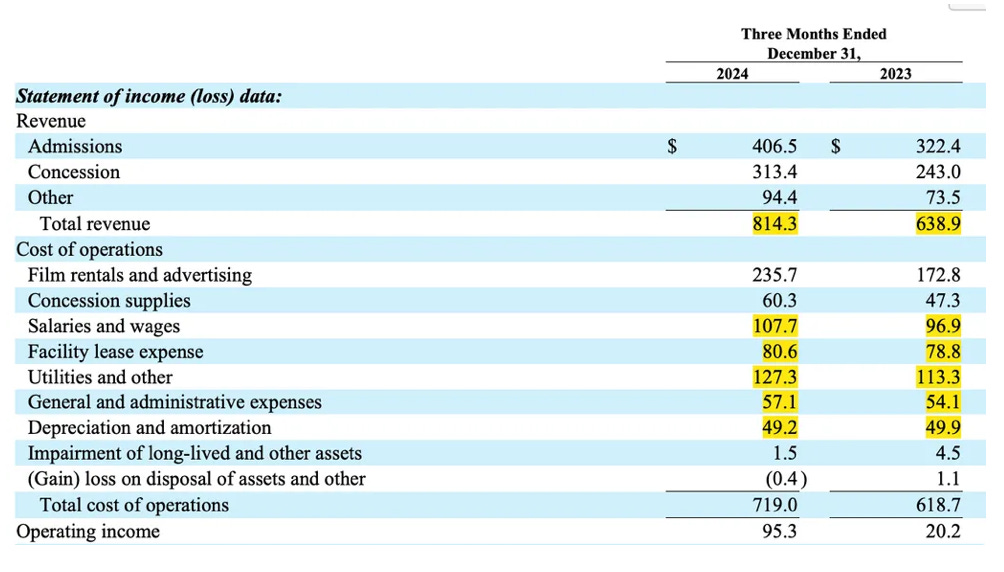
Cinemark’s $200 million buyback anchors a review of theater cost structures, MCS and a completed Fairfax preferred-share special situation.

EDreams nears 7.25 million Prime members and €180 million of Cash EBITDA, marking its shift from an online travel agency to a…
EDreams’ Prime travel subscription model makes the €3.6 billion European OTA a potential Uber, Airbnb or Amazon acquisition target.
*THIS IS NOT INVESTMENT ADVICE* 1/6 I’ve been slowly building a position in $RAVE since December of 2023 but since their most recent annual report I’ve been buying much more aggressively…
My team has the stones to tell me "the deck we prepared on $PLNT is the best work we've EVER done." I rarely hear that degree of confidence from anyone. You be the judge...presentation TOMORROW, 8/16. Deets below. https://t.co/u5qz3Xcdl4
The work we're doing on $PLNT is next-level -- similar to what we did on $FND, but with a VERY different conclusion. Analyzing each store from a property developers perspective... Black Book on Friday... https://t.co/XKWvJdeWyH

Monarch Casino trades at 7.2 times EBITDA with net cash, completed property upgrades and projected annual free cash flow of $120 million to…

One Group Hospitality's $365 million Benihana acquisition adds $575 million of revenue and $70 million of EBITDA, funded partly by costly…
$DAKT Est $50-70M revenue project. 4 jumbotrons, 5 ribbons + software contract for 2 stadiums. https://t.co/ANVOiAiZHn
