
Barbarian Capital on X
3/n $SBUX CEO on the @CapitalGroup pod on the turnaround efforts + more Also covers his time at $YUM $CMG $PG https://t.co/PI6oUxsXLE
Sector
Everything our editor has picked under this sector, best first.
182 stories
3/n $SBUX CEO on the @CapitalGroup pod on the turnaround efforts + more Also covers his time at $YUM $CMG $PG https://t.co/PI6oUxsXLE
$PM crazy intraday moves (incl new intraday ATH both days) July 28 Oct 15 $COST $KO $BUD $MO $MDLZ similar on these two days; earnings day-like moves https://t.co/jVyJ8a4Tkp
rare for a large chain KFC to Ditch Pepsi for Coke in Thousands of Restaurants $YUM $PEP $KO https://t.co/9qSnos5TxW
Starboard built a ‘several‑hundred‑million‑dollar’ stake in Shake Shack $SHAK, likely making it the largest active shareholder. It calls the brand undervalued, seeing it trading at ‘about half’ of where it should be. Starboard is pushing SHAK to accelerate US expansion by adding franchising rather than relying solely on company‑owned stores.
Kraft Heinz expects brand investment and productivity gains to restore sales growth and protect 2027 margins against 4-5% cost inflation.
 The Alpha Analyst 1 click
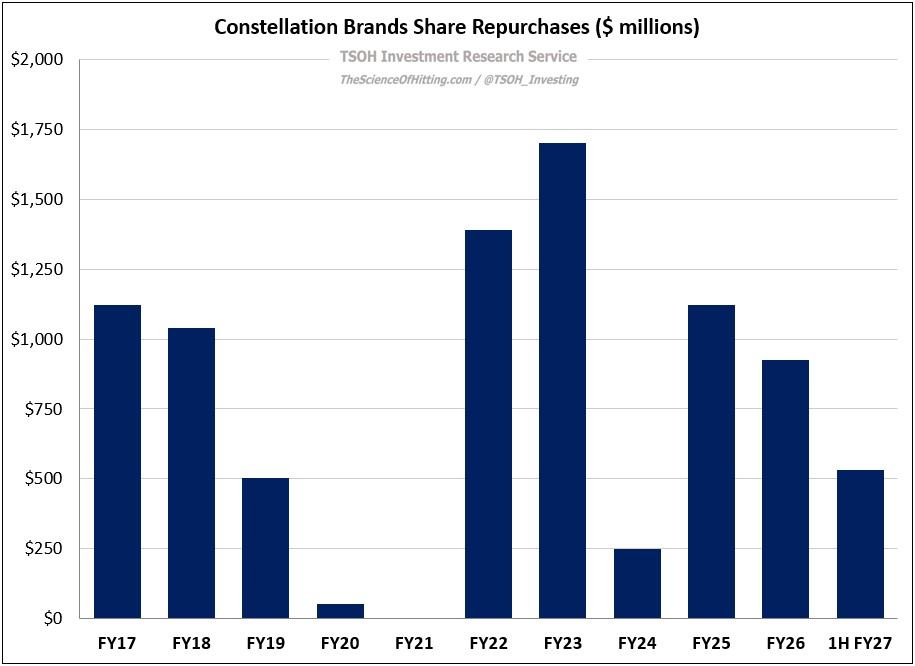
Constellation Brands trades near $127 at roughly 11x next-twelve-month EV/EBIT, with recent business results offsetting concerns over…
@valuedontlie Forgive me I haven’t done the work I may soon, isn’t the whole point of $VITL is having a brand and being specialized to insulate it from cyclicality to see degree? I’m one of those people who pay up for pasture raised no matter what
@ThothCapital @valuedontlie I would love to/can’t wait to read your $calm report
@valuedontlie Colin would you pick $CALM over $VITL and why? Thank you, love your research and opinions
August write-up on Cal Maine $CALM now available to freebie accounts on VIC... Good overview of the situation... at ~$60-65/sh it looks like an asymmetric bet with a 4-6 quarter time horizon https://t.co/60U009ZX53
Sweetgreen’s Plan to Shed Its Expensive Salad Image $SG https://t.co/3IxCL40Caw
$NOMD held their first investor day in ~6 years... dedicated an entire slide to the insane amount of recent insider buying + incentive comp upside https://t.co/B3mpLfE9Q9
Altria’s EPS gains rely on tax refunds and discount brands while Marlboro growth lags.
 Vishal Jadaun 2 clicks
$FIZZ seems like an attractive short. Classic staple juicing price into slowing volumes, meanwhile they're getting attacked by competition. They trade at around 17x earnings for some reason when a lot of better looking staples trade at low teens.
 GNCGF · long
Greencore is the UK’s leading fresh prepared food producer, pitched as undervalued with potential to nearly double within 12–24 months.
Anyone following $NOMD with a take on their recent investor day presentation?
Flowers Foods trades at 7.5x earnings after an 80% decline, as a 50% dividend cut and potential asset sale aim to reduce leverage following…
Pretty odd divergence in the move in $SHAK versus the rest of the QSR space in the past 10 days.....
PepsiCo trades at 15.28 times 2026 earnings with a 4.61% yield as international growth, cost cuts and higher cash flow support its dividend.
 Steven Fiorillo 3 clicks
Wow - corn-o-plenty for $ALTO and $GPRE Shocking USDA numbers today.....
Paramount Skydance’s debt-heavy Warner Bros. Discovery acquisition, streaming bundle pricing and alcohol-industry diversification anchor…
@jupiters_string $VITL? 👀
 POST · long
Post Holdings remains a large position after the stock's recent decline.
Secular theme of increasing competition in the coffee space, no issue taking a position against SBUX which still carries a premium valuation largely on that premise. My flip side to that, is why also be long Dutch $BROS? Trades worked against you for almost the same reasons - intensifying competition from direct copy cat 7 Brew. But there are many regional players that are aggressively scaling - Summermoon, Foxtail, Lala land, Merrit, etc and those are the ones just geographically close to me but it's a countrywide phenomenon. Turns out yes coffee is habitual and generates good cash returns, but barriers to entry are low. The bidding war for the Salads real estate was insane, and shows how deep pocketed 7 Brew is in their expansion, and being PE backed and not public means they might be less disciplined...... So why Bros? There might still be potential there, the model is efficient and a cult service culture, but even at current levels I find the valuation difficult to digest not to mention overhangs from GLP1s, affordability/gas prices
