
Odd Diligence on X
$SKHY 44% premium to KOSPI issue, arbs https://t.co/KkL02w7b2m
Sector
Everything our editor has picked under this sector, best first.
137 stories
$SKHY 44% premium to KOSPI issue, arbs https://t.co/KkL02w7b2m
WhatsApp named CRED founder Kunal Shah to replace Will Cathcart after Meta bought a 20% CRED stake for $900 million, signaling a push to…
$WDFC results are staggering when you read through them....then you get to the guidance and it does not reflect the monstrous quarter they just posted (relatively the same as the guide from Q1)....something is off with this company, they are either one of the worst non micro cap companies at forecasting their business (not a great endorsement of management and their processes). AND/OR they are playing games with inventory to influence the stock. I will reserve my own comments for private, but if you look back in recent years there are some odd swings in Asian /Chinese inventories in given quarters. Fascinated how a product that has been around forever with wide distribution posts a +30% print in Americas, 24% company wide. And the guide moves from 5-9% to 6-9% growth for the year?? What is going on?
DoubleU’s $11.25-per-share bid for DoubleDown Interactive values its operating business at 0.25-0.7x EBITDA; minority holders can block it…
JD, Alibaba and Douyin are assessed for their competitive threat to PDD, with a specific investment stance on JD.
Nvidia’s switch from billing location to customer headquarters reclassifies geographic revenue and exposes a larger China footprint through…
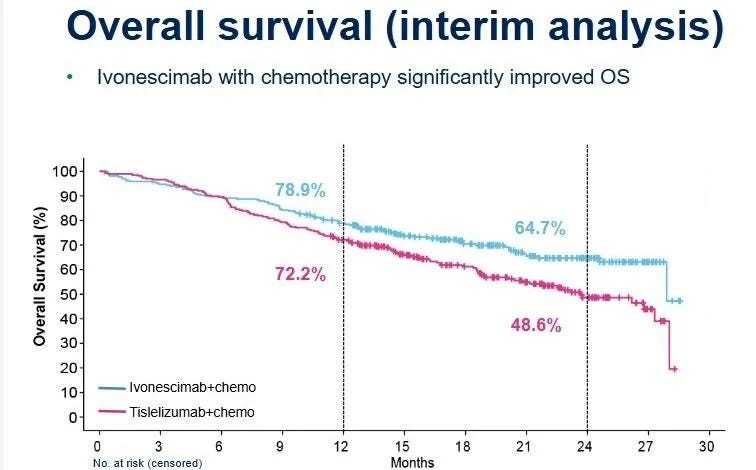
Ivonescimab plus chemotherapy extended median overall survival by 4.2 months versus Tevimbra plus chemotherapy in HARMONI-6, challenging…
Portfolio end of May '26: Centrotec $CEV.HM Toyokumo $4058 Evolution $EVO Secunet Security Networks $YSN BioRem $BRM.V Leatt $LEAT -undisclosed- Shelly Group $SLYG Enogia $ALENO.PA (prev. undisclosed) ErreDue $RDUE Lindbergh $LDB.MI -undisclosed- Circle Group $CIRC.MI (1/2) https://t.co/ZCsmkvYuTS
Grab reported Q1 2026 operating leverage, targeted financial-services breakeven by H2 and held $5 billion cash while advertising average…

Coupang’s data scandal cut active customers to 23.9 million, but 80% of departed WOW members had returned by April as vouchers and…
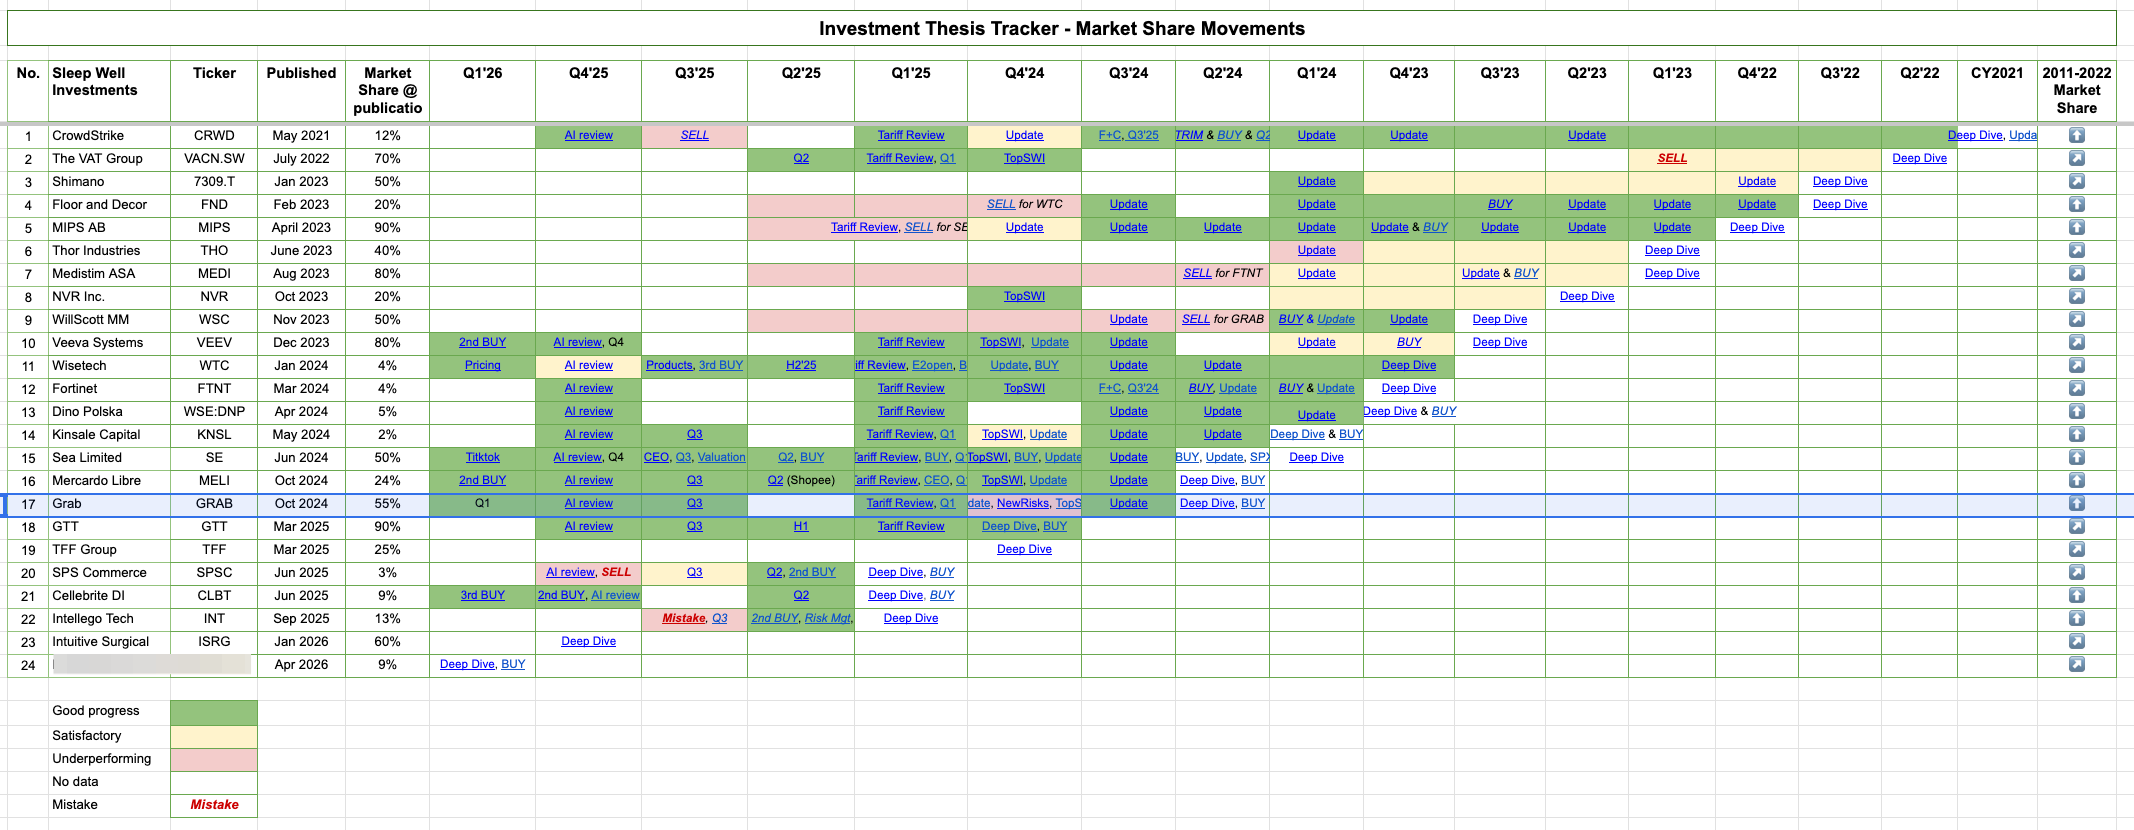
Sleep Well Portfolio publishes its 24th pick and updates Grab, Sea, WiseTech and Veeva as software stocks stabilize.
Sea Limited generated about $3.5 billion in free cash flow as Shopee invests in Southeast Asian and Brazilian growth despite lower 2027…
Happy to share our Q4 2025 letter. Especially at a time when the future of internet and software business models are being questioned. In it, we offer our take on: - The "AI Scare Trade". The market is pricing in fear, not facts. These businesses aren't broken (yet), but investors are selling indiscriminately. - What's still investable? Software faces real headwinds - disruption to terminal value assumptions and forced pricing model shifts. But ~80% of a software company's value is trust, reliability, and headache-free solutions. That doesn't disappear overnight. - Network effects are real moats. Gaming, ecommerce, consumer internet - they're all down substantially from highs. But as AI reduces barriers to entry, the barriers to scale go up. Distribution grows more valuable. - Thoughts on $SE, after a -45% drawdown. We don't think the TikTok boogeyman is as scary as the market fears. In fact, the opposite. - New Oriental $EDU exit. Originally bought near net cash, and business has stabilized since. Time to move on. Full letter linked here: https://t.co/0WPoxoHt7t
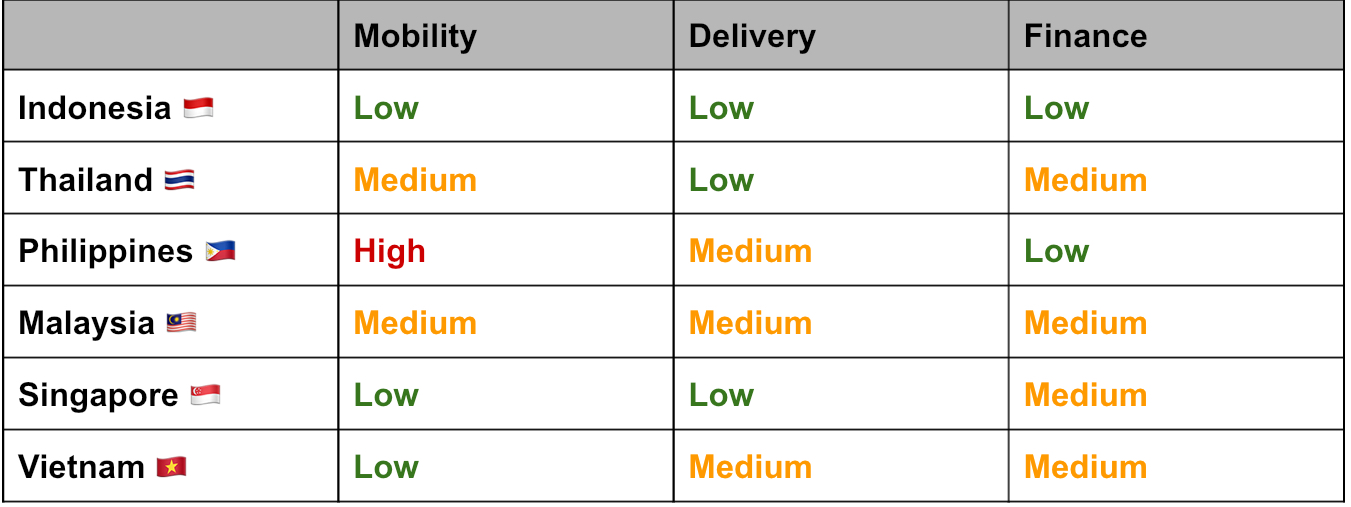
Grab’s main holding risks are competition, sustainable profitability and valuation, with entrenched ride-hailing and delivery positions…
Evolution's fourth-quarter revenue fell 4% as Asia cyber disruption and European channelization outweighed U.S.
Just hammering this home. For simplicity's sake, let's use round numbers for 2025: 1) J&T Order Volume Grows: 75% y/y 2) Tiktok & Other Customers Grows: 40% y/y 3) J&T Grows Market Share from 27% in 2024 > 33% in 2025 (disclosed in the 1H25 Report) 4) Non-platform % of revenue goes from 0% > 10% in 2025. All the data-points line up. Takeaway: It can be true that J&T grew 75% y/y, AND Tiktok is slowing to 40% y/y orders growth (and 30% y/y GMV). - Market narrative of Tiktok competition increasing is likely wrong. - Means that Shopee's recent spend is not a defensive move or coming from a weakened position. - In fact, they're pressing harder, while competition is weak (That's just how they operate. They waited to grow Monee loans, until the digibanks started blowing up. That's why you see an inflection in loan growth 2 years ago. Compare that to when Indo digibank NPLs started blowing up, and you'll see the correlation). Included pictures of the math (thanks ChatGPT). $SE $1519.HK
From J&T's 4Q25 call. They called out 1) winning share from competitors and 2) non-platform parcels growing (i.e. not from Shopee or TTS). So perhaps J&T's strong volume growth isn't related to TTS vs. Shopee competition? $SE $1519.HK https://t.co/Jn0UArEo04 https://t.co/pbA0DXJsD6
$SE is down -45% over the past few months. The prevailing bear case seems to hinge on two points: 1) Rising fear of TikTok Shop competition, and 2) Shopee reinvesting more heavily into logistics, capping margins at ~0.7% of GMV this year vs. prior expectations of ~1.2%. The concern is that this spend is defensive - a necessary response to TikTok rather than a choice. But alt data is telling a different story. TikTok Shop’s Southeast Asia GMV growth has slowed materially over the past few quarters - from 70%+ in 2Q25 to ~30%+ by late 2025. That’s only modestly above Shopee’s own growth rate. More notably, TikTok’s relative share vs. Shopee in Indonesia (~50% of regional GMV) has effectively flat-lined over the past year. If this data is directionally right, Shopee’s ~50 bps of reinvestment looks discretionary and offensive -widening the moat - rather than a defensive reaction to competitive pressure. And critically, that implies the margin compression is temporary, not structural. Oh, and both Shopee & Tiktok are raising take-rates. Not usually the sign of a competitor trying to aggressively take share... Curious, what am I missing? Is the -45% drawdown really just “2026 margins down > negative 2026 earnings revisions > stock down,” even if margins are likely to re-expand next year? And Shopee emerges with a wider moat after? The competitive backdrop looks like it’s improving, not deteriorating...
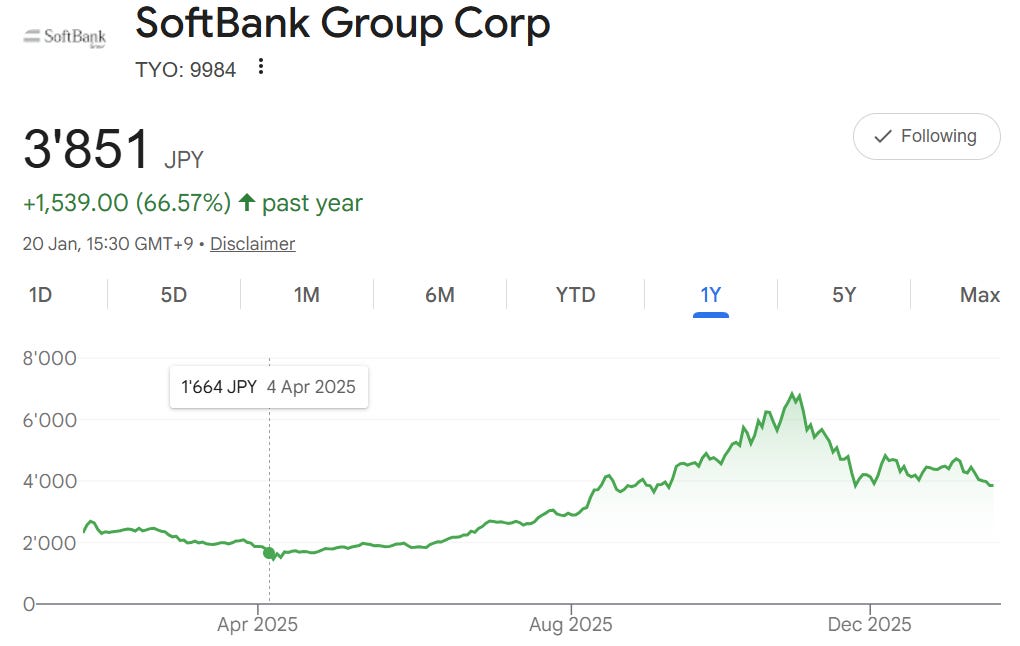
Portfolio update exits The Trade Desk, QXO and Park Hotels, then adds Tencent at a 35% discount, SoftBank for AI exposure and HelloFresh at…
Coupang’s former strategy VP discusses Taiwan expansion, 1P-versus-3P economics, margins and competitive risks as CPNG trades 35% below its…
#Southeast Asia Logistics Where there used to be dozens of players, now there's just two that matter - Shopee Express, and J&T (>60% combined market share). In a high fixed cost business, Scale > Order Density (across both Geography x Time) > Lowest Cost per Parcel = Competitive Moat. Parcel delivery cost has declined -45% over 4 years. h/t @momentumasia. $SE $1519.HK
Coupang’s former strategy VP discusses Taiwan expansion, 1P-versus-3P economics, and competitive risks as $32 billion of LTM revenue…
China Yuchai (CYD) seeks a 2026 rerating as governance normalization, global expansion, AI data-center power demand, and green-powertrain…
Forrest's latest memo echoes his recent podcast interview - belief that the AI platform-shift has created a window of opportunity. For Sea Ltd $SE to be a $1TN company, if they play their cards right. https://t.co/s9IiqSfd4w https://t.co/Q5AEMfnl7P https://t.co/EYgD8uK51z
