
 PERF · long
Perfect CORP
Perfect Corp., a Taiwan-based beauty-tech microcap SPAC, trades below net cash despite sales growth after falling from a brief $2 billion…
Sector
Everything our editor has picked under this sector, best first.
137 stories
PERF · long Perfect Corp., a Taiwan-based beauty-tech microcap SPAC, trades below net cash despite sales growth after falling from a brief $2 billion…
Humanoids down under! While it may surprise, Appen $APX.AX used to be the world's largest data labeling company, but it lost market share to $INOD because it was slow to adapt its tech stack and lacked product-market fit. However, their Chinese business (China's largest) continues to do well and has really seen an inflection; all the forward hiring trends we see are extremely strong. So if you believe Chinese AI and robots have any relevance globally, they should benefit. Yours truly for sub-1x revenues, because most Australian investors still have this stock on a blacklist after losing their shirt last cycle.
Is $BABA is the only NYSE/Nasdaq listed company that owns Unitree? https://t.co/02u7SwTbOc
 PRGLY · long
PureGold Price Club, the Philippines’ largest food retailer, operates hypermarkets, supermarkets, minimarts and S&R membership warehouses.
$ACMR evolving its institutional shareholder base as its earnings power & liquidity increase: US-listed bet on China Semicap. Capital Group now top 4. Ward Ferry, 12 West, Citadel… https://t.co/7mMHvefEYe https://t.co/cY0fynu04r
ZhongAn Online trades at 0.57 times book after five profitable underwriting years, with a 95.8% combined ratio and ZA Bank’s first…
JinkoSolar sold control of its Florida solar plant to a Delaware entity run by China’s “Sun King” family, potentially sidestepping new…
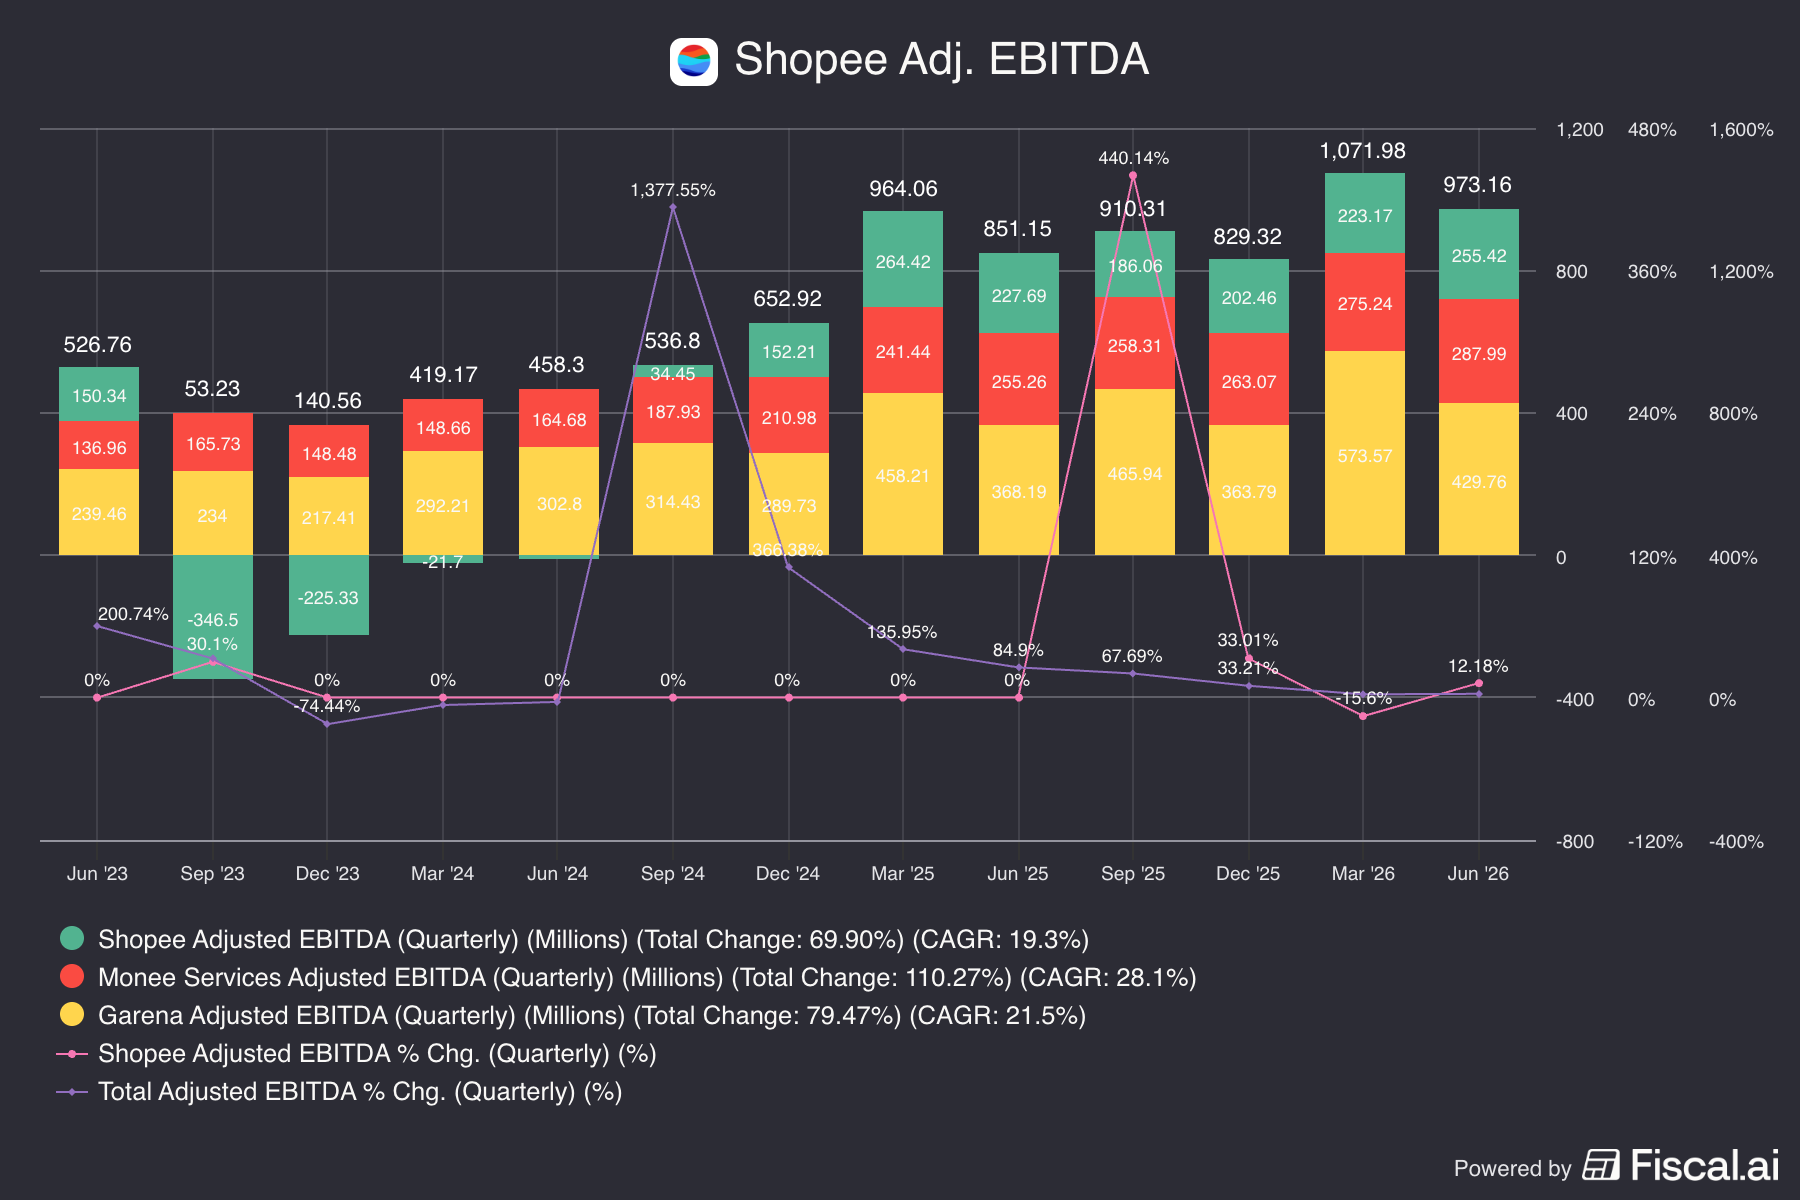
Sea Limited’s Shopee lifted adjusted EBITDA margin to 0.7% in Q2 2026 as revenue rose 48%, targeting 2-3% through fulfillment efficiencies…
Bernstein China Semicap & WFE update: $101 bn in ‘28 > WFE ramp drives reacceleration of local WFE vendors > logic underestimated > memory revised up: CXMT, YM & JHICC easier to ramp clean rooms > local vendors take share from global vendors > ‘27-28 numbers go up $ACMR https://t.co/8qZFoulEau
Noah Holdings trades near the value of its RMB 5.1 billion cash and short-term investments, while earning recurring fees on roughly RMB 140…
GS on $ACMR beat and 2026 raise. PT $164 2027 numbers and memory contribution (CXMT matter more) imho https://t.co/XXKNyhL8Gg
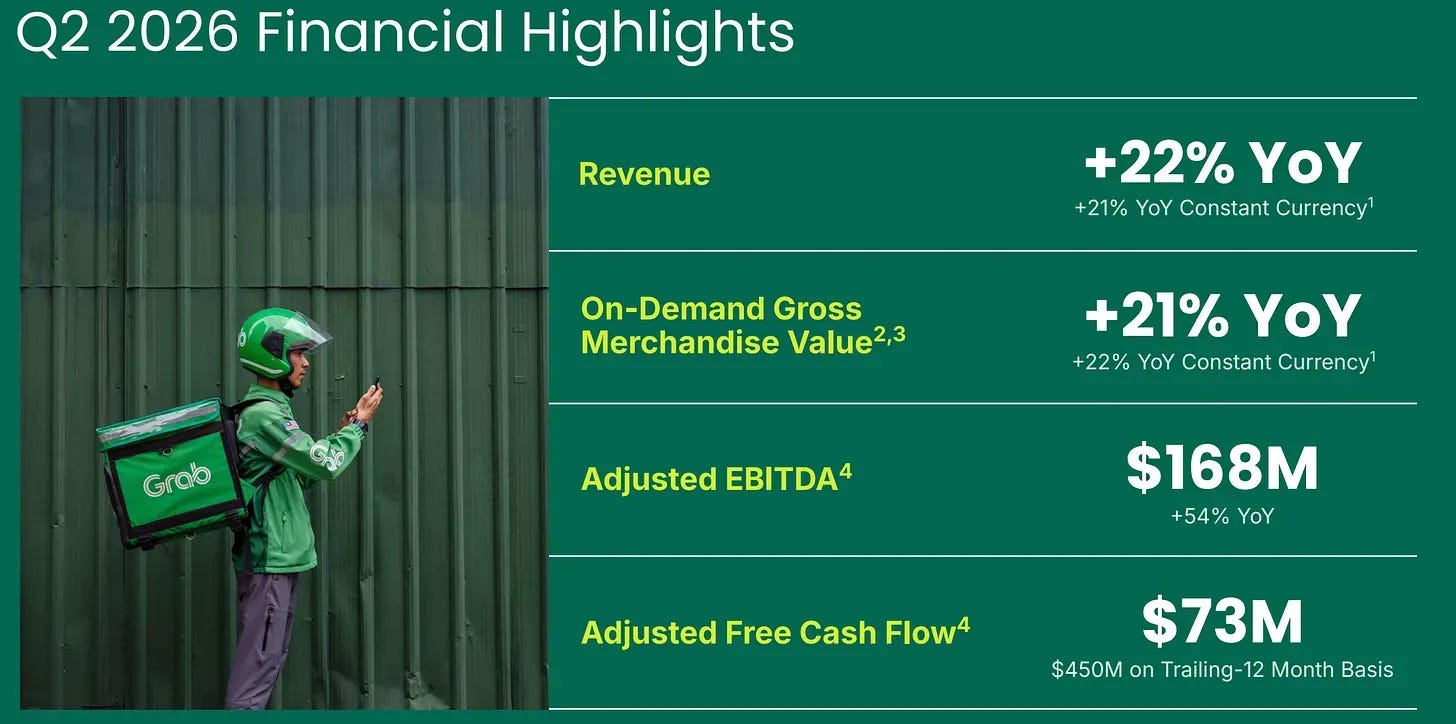
Grab reported 54 million monthly transacting users, up 16.7%, and $168 million of adjusted EBITDA, while autonomous driving threatens its…
Coupang’s product-commerce revenue rose 8% in constant currency as data-leak churn lingered, while promotions and underused logistics…

Coupang’s data leak held 2Q26 constant-currency product-commerce growth to 8%, while promotions and excess logistics capacity pressured…
Roderick van Zuylen discusses Night Watch’s value strategy, catalyst-driven screening and positions in Asian equities including Dream…
$AAPL also prices in the flattering things you've articulated. 35x EPS. Missed on Services revenue w/ a 4 point decel vs a 2 point harder comp. Comp gets harder in September. China revs missed and are slowing. China comps get much harder next year...could easily see 22% growth down to 10% or less. And again, everyone owns AAPL as evidenced by the near 2x market cap appreciation in the last year - thats nearly $2T that's been bought. All the other names have more hair, but much more upside if they continue to execute.
Well would you look at that. $COLO $EWY https://t.co/fIuPhTl9TI
Hmmm so what happens to China WFE and local semicap? $ACMR https://t.co/zCLlueeF3O
“Huawei’s report on its progress gave Ding leeway to be more aggressive. He delivered a blunt warning to China’s largest AI users, according to people familiar with the message: Anyone who resisted employing domestic chips was a traitor.” $ACMR https://t.co/2DDOgMTQEW
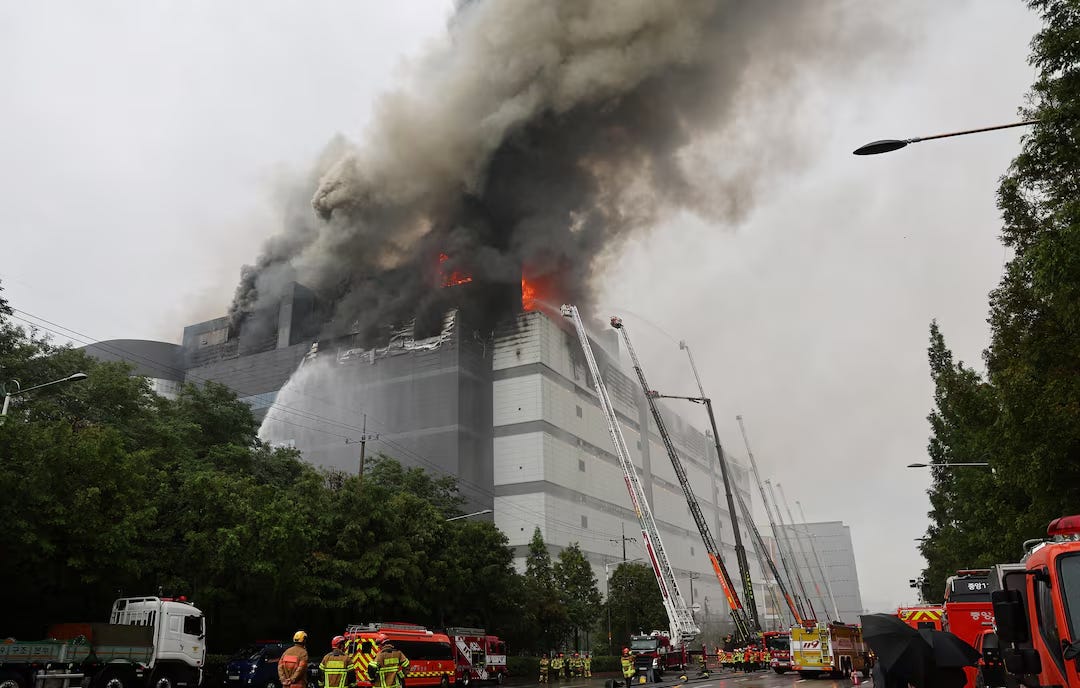
Coupang says customer demand is normalizing after its 2025 data leak, while Q1 vouchers and underutilized capacity pressure margins.
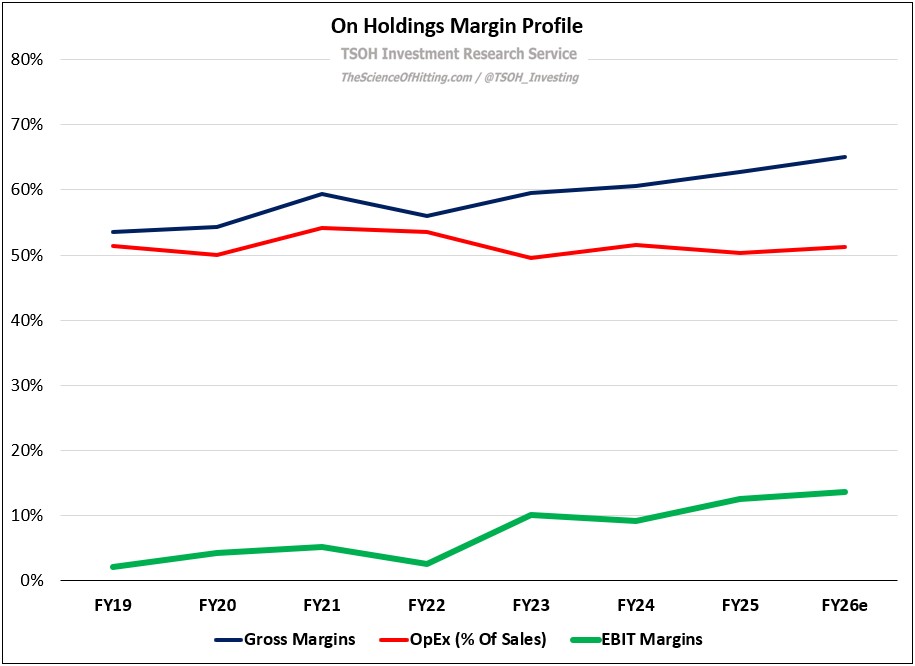
On Holdings expects roughly CHF 3.5 billion in FY26 revenue as running shoes drive growth, while APAC exceeds 20% of sales and apparel…
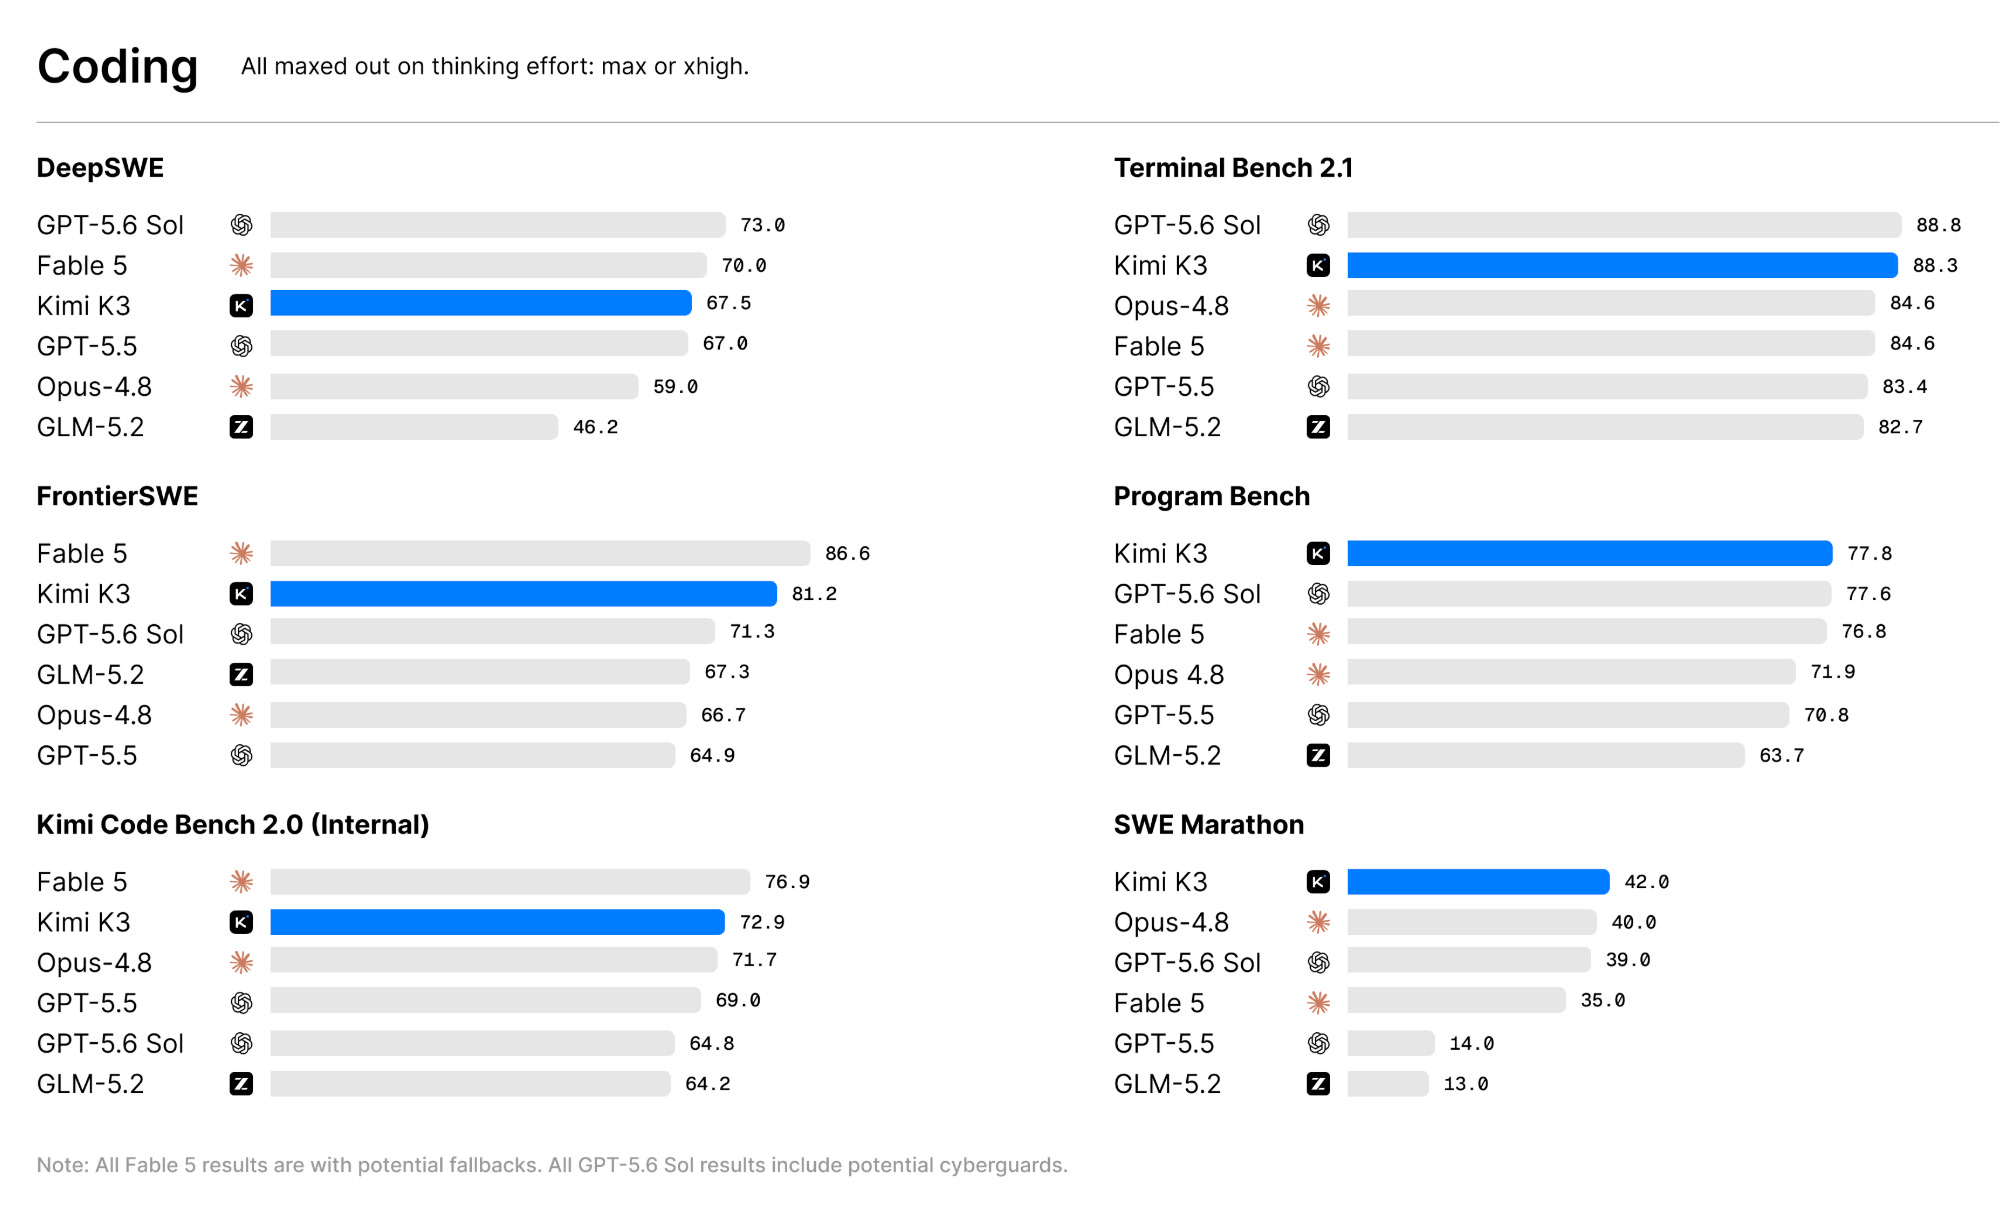
Moonshot’s 2.8 trillion-parameter Kimi K3 is a China AI challenger that requires high-memory Nvidia servers and heavy inference compute.
@Merridew__ $SOXL down 52% $KORU down 69% Nature is healing.
the KOSPI shares should open up higher.. Maybe 5 to 10%? Just depends on the Korean vibes i guess over there, hard to pin down. for $SKHY 177.9M shares in IPO, 118.6M shares went to top 25 IPO buyers. Unfair to say they are not trading but have to think a lot of them are not for now. So just napkin math hypotheticals, 59.3M shares after top 25 IPO buyers. $DRAM ETF has 2,898,599 kospi shares currently, and have started buying $SKHY already - they have 850,000 SKYH shares. 2,898,599 KOSPI shares is equivalent to 28,985,990 SKHY. I dont think theyve said that they would switch but IF they did that's another 29.8M shares or so just for that 1 ETF Then SKYH is down to 29.5M shares... All this is hypothetical of course... Just basic hypotesis. Not to mention all the other ETFs that will hold this, all the funds that had no access to Korean markets who can trade this now. All the dumb levered ETFs. I think the premium can get real dumb. Im long both SKYH and $660.KS. for my trading there i think there's opportunity cost in monitoring this trade, when being in the spread, which doesn't fit my personal style - so i dont think i'll be in the spread at all - but thats personal preference
