
Tencent Music: The Market Is Pricing In Too Much Weakness
Tencent Music trades at about 8.8 times forward earnings, with membership revenue and Ximalaya integration supporting profitability despite…
 LL Insights 2 clicks
Sector
Everything our editor has picked under this sector, best first.
137 stories
Tencent Music trades at about 8.8 times forward earnings, with membership revenue and Ximalaya integration supporting profitability despite…
LL Insights 2 clicks
Undercovered Dozen profiles 12 lesser-covered stocks, including Ares Capital, Grab, Lenovo and Rigetti.
GLP-1 drugs are gaining traction across Asia as Chinese developers advance candidates and Indian generics slash prices, reshaping prospects…
FT on Huawei’s quest. China WFE looking stronger. SMIC, CXMT and YMTC are all customers of US listed ACM Research $ACMR https://t.co/KJmyqHFa17
$WDH out with what looks at first glance to be pretty good earnings. 3 cent/ADR dividend. https://t.co/NZZUQXN0Jz
Kirin 9050 Pro is the first Tau Scaling chip. The bigger story is Ascend. Huawei just put LogicFolding in the Mate XT 2. First commercial SoC on the Tau (τ) law He Tingbo laid out in May / updated in July. Not a surprise if you read that paper. Still a real jump: DUV + SAQP + logic stacking took density from 155 → 238 MTr/mm² on the same SMIC N+3 node. +55% in one gen. Power went down, not up. That’s N3-class equivalent density. Headline number matches Intel 18A HD (238) and sits next to Samsung SF2 (~231). TSMC N2 HD is still ahead (~313). Caveat: 238 is Huawei’s LogicFolding equivalent, not a planar N3 shrink. Same device node as 9030 Pro. Some analysts put the industry-formula read closer to ~175. Mobile scoreboard vs last-gen trifold / 9030 Pro: • Device +42% • CPU ST +24% / MT +52% • P-core 3.1 GHz (was 2.75) • CPU / GPU / NPU iso-perf power −41% / −58% / −66% • GPU render +142% • On-device 30B-total-param MoE Multi-core still trails $QCOM’s latest. The gap is no longer multi-generation. Next Tau Kirin can catch, maybe pass, a leading-edge mobile SoC. The packaging tell is sharper than the phone benches. 1.4–1.5μm hybrid-bond pitch. ~50M vertical interconnects. Western HVM hybrid bonding is still ~6μm (TSMC SoIC) to ~9μm (Intel Foveros Direct). If 1.4μm holds, that is SOTA vs Western leading-edge bonding — not the Geekbench print. Phone catch-up is the demo. AI silicon is the payoff. Apply the same fold to Ascend and the process-density gap vs $NVDA peers compresses from the lithography side over the next few quarters. Remaining bottlenecks: domestic DUV tool volume, HBM, packaging, software. I wouldn’t assume they outproduce ASML on DUV. I also wouldn’t fade the direction. Mature DUV + stacking + almost-unlimited power is enough to put China in the token-factory fight vs the US. Tables below. 🧵
Grab Holdings dominates Southeast Asian ride-hailing and food delivery, trading at 23 times earnings while profits grow rapidly.
 A.J. Button 1 click
Hurco returned to operating profit after 11 loss-making quarters as sales, margins and orders improved, led by a broadening U.S.
 Stephen Simpson
The massive share buybacks at $SKHY & Samsung are highly supportive to the stocks but quickly coming to an end. The Hynix buyback is 32% done & at current pace will conclude by 10/15. For Samsung the comparable numbers are 37% & 9/30. Then we see where prices shake out.
Chinese stockbrokers FUTU $FUTU and Up Fintech $TIGR are taking a beating after the Chinese securities regulator ordered all unauthorized Mainland accounts to be closed within 2 years, with only sell orders and fund withdrawals allowed. Both companies will be fined, but a rumored 1.85b CNY fine for FUTU is less than 2 months of profit. For FUTU, mainlanders are 13% of accounts but closer to 20% of total assets and revenue. FUTU's rapid growth in HK and SE Asia has diversified the business in recent years, and the loss of Chinese customers is less than 1 year's worth of customer growth outside China. What remains is a faster-growing, HK/SE Asia consumer play with no China risk, which probably trades at 8x P/E with net cash. That is, if this was the last shoe to drop and Mother China isn’t intent on ruining them.
NIO beat Q2 expectations as delivery growth and higher ES8 and ES9 vehicle margins narrowed losses. Its shares trade at 0.35 times revenue.
 The Asian Investor 3 clicks
 TOYO · short
TOYO CO LTD is the target of a short thesis.
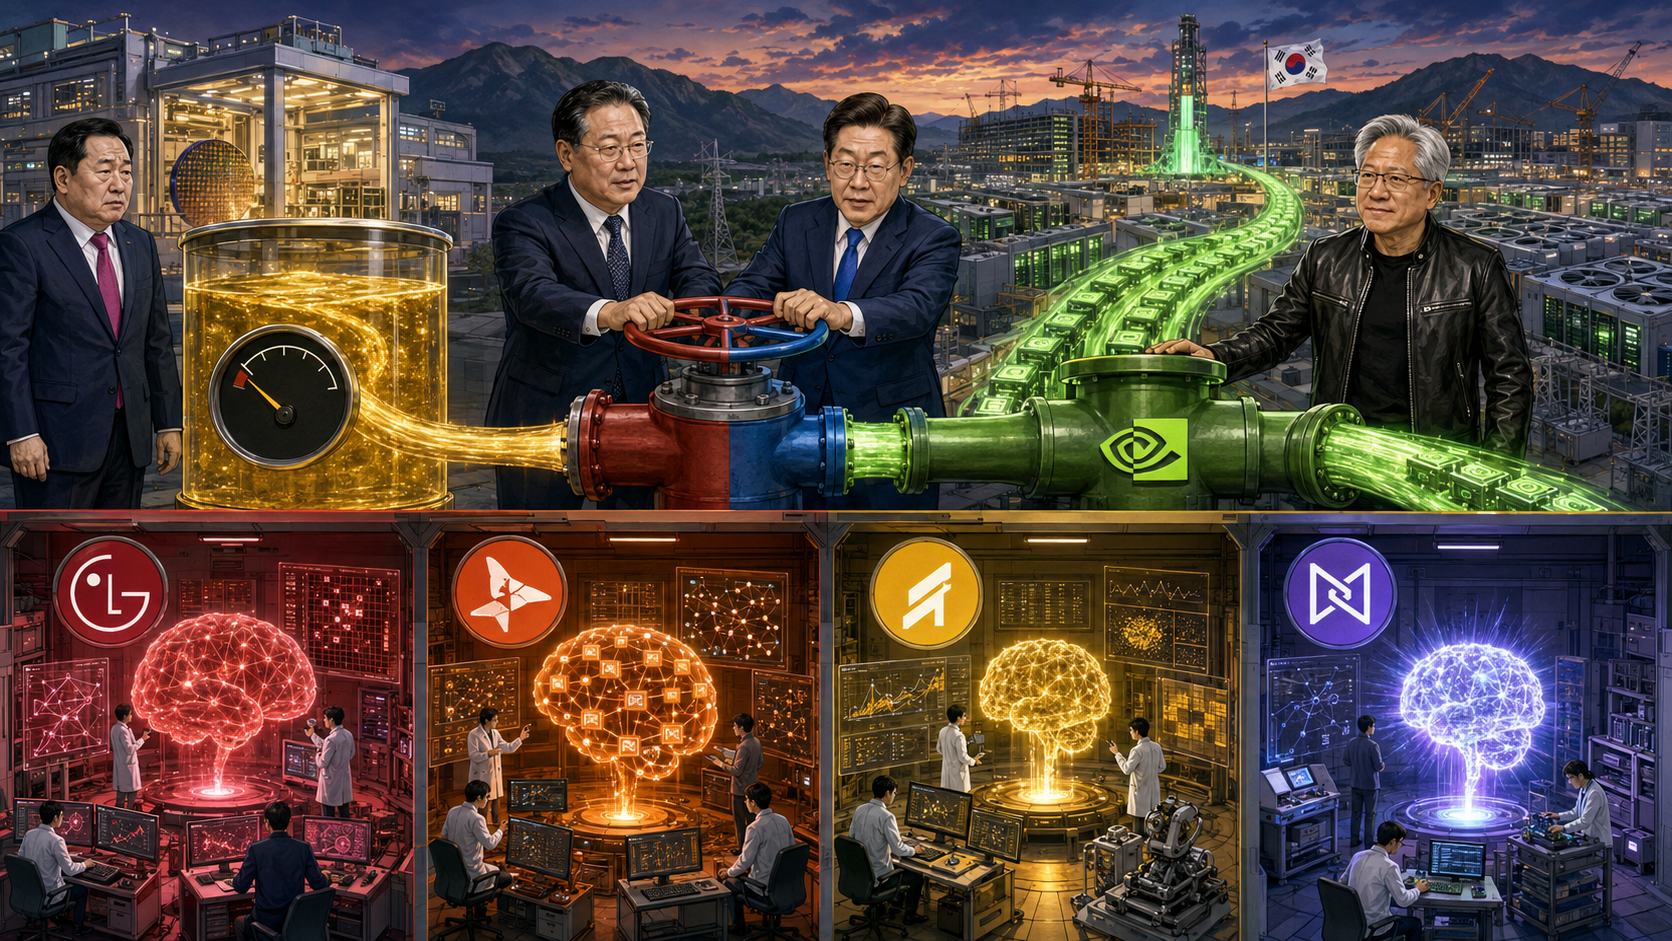
South Korea’s sovereign AI push channels GPU spending to Nvidia while domestic-model ambitions risk conflicting with Samsung and SK Hynix…
The most interesting observation about Midea for us this reporting season is that since the national team liquidated most of their holdings, Midea is one of two private companies that Huijin choose to keep. Why? One can only speculate, but having the long term track record to zero an entire global industry probably has something to do with it: just check the share price of $WHR or $ELUX.ST
Having Sony Music Entertainment makes it a lot less likely Gungho will attempt a take-under of $GRVY, IMO https://t.co/xvjalTHgN7
I just published my Portfolio Update for August 2026. It includes: ▫️My current Portfolio & position sizes ▫️Earnings Update about $YSN.DE, $SLYG, $LEAT, $4058 ▫️Recent news & information about $CIRC.MI, $EVVTY, $4058, $SLYG https://t.co/bEmwcymkyy
 MU 2026-08-28
SK Hynix posted record quarterly revenue of 79.32 trillion won and a 76% operating margin, while trading below Micron on forward sales and…
 Prakhar Agarwal, CFA 4 clicks KSTR 2026-08-27
Kraneshares China Semiconductor ETF, KSTR, is the only U.S.-listed ETF holding CXMT, giving investors direct exposure to China’s leading…
 Chetan Woodun 1 click
YMTC is another top customer of $ACMR ACM Research seems to be the most clear direct US-listed beneficiary of the inevitable Chinese memory wave https://t.co/zrRv9YQSXQ
$BABA management continues to do everything in its power to keep the stock a generational value trap https://t.co/kgj6l73QpY
$BABA Aug 20: "For the quarter we repurchased shares for USD 162 million. We remain committed to maximizing long-term shareholder returns through disciplined capital allocation across investments, share buybacks and dividends." Aug 22: https://t.co/zqPOmQ8B8q
@davey_juice What did we learn from the all-in $pdd guy crashing out? Not much, apparently.
FUTU 2026-08-23 Futu Holdings' Q2 funded accounts rose 33.6%, client assets 43.6% and net income 41.6% as it shifts from mainland China toward Singapore,…
 Emanuel Nemec 4 clicks
Trip.com dominates China’s online travel market with over 50% share and has grown international platform traffic from 1 million monthly…

