

Hunterbrook on X
UPDATE: Is Google $SEI’s “Customer C”? A Solaris Energy Infrastructure subsidiary applied for an air permit for “natural gas electric generating units” in Texas. The listed location points to Google’s Midlothian data center.
Tuesday, September 29
Everything we published on this day.
72 stories — the front page that day →
UPDATE: Is Google $SEI’s “Customer C”? A Solaris Energy Infrastructure subsidiary applied for an air permit for “natural gas electric generating units” in Texas. The listed location points to Google’s Midlothian data center.

@lazereater You can read about $LWAY drama here:

$QURE A bunch has been written about today's AMT130 news by people far more scientifically credible than me, so I'll just summarize to say my opinion is that the data was directionally bearish but only mildly. I think the reaction to the news was overblown. If you gave me the press release and conference call ahead of time and asked me to guess "what does the price trade to", I'd say around $32. Lots of people have complained about the type and quality of disclosure and messaging from the company but I want to highlight something I noticed that I think has been missed. My experience this morning was that the actual press release process was entirely mishandled. Here's what I think happened: 7:05AM ET is the "typical release time" for QURE. So naturally when they setup an interview with Stat News and Bloomberg the night before, they likely communicated this "embargo time". So at 7:05AM, the pre-written articles from Stat and Bloomberg hit the newswires. Bloomberg's article was particularly poorly done, with exceptionally little detail beyond the "-44% not stat sig" datapoint. (They later "updated" their news article to be more robust). But this awful article was essentially first to hit the headlines, and obviously thousands of bots and machines are scraping Bloomberg, and trading off it. Naturally one would want to "check for more data beyond two articles", but for some reason, at 7:05AM, there was no Press Release from QURE. This was likely a mistake (either by QURE or by the wire company). In the screenshot (and link) below, you'll see the timestamp of the official wire including ALL of the data. So investors were "left in the dark" for a full 7 minutes. Does 7 minutes really matter? To a long term investor, certainly not. But it matters to algo traders, who leave footprints of price action, which affect sentiment, so it does matter. Also, it leaves me unsettled that they're possibly getting some of the most basic things wrong. I get their jobs are stressful and there's a lot on the line here, that's why you have to dot your i's, cross your t's, because everything matters. To be clear, I don't know for a fact who's error this was, but I'd speculate it was the company. (Here's a normal press release from the company timestamped at 7:05AM ET. There are many other examples on the site that corroborate the 7:05 ET pattern) Disclosure: Creek Drive and its affiliated funds hold a long position in QURE. Views expressed are current opinions for information only, subject to change and are not investment advice or a recommendation to buy or sell any security. Investing involves the risk of loss and past performance is not indicative of future performance. See the disclosures link in my bio for more important information.

@SmallCapVal Was excited to see an insider purchase at $CME filed yesterday but it turned out to be a dividend reinvestment as most of the purchases at $CME tend to be.
@accrued_int Yes indeed! Tons of buying In $DKS since August. Retail has generally been a difficult sector for me and so I am approaching this cautiously.

442,113,600%. That's how much Altria has compounded over the past 100 years. $MO Remove Altria from the average return of every US stock since 1926, and the average gets cut in half: from 30,000% to 15,000%. What's stopping you from compounding like that?
Asia's elevator boom favors maintenance and modernization providers, with Otis deriving nearly 90% of operating profit from after-sales…

Doing this on the eve of the first massive share unlock on $CBRS is quite the move...

Can someone find me a single CEO own has bought as much stock in the open market as Ryan Cohen has done for $GME? I know it’s a hated stock on Wall Street but come on guys. This is massively bullish.
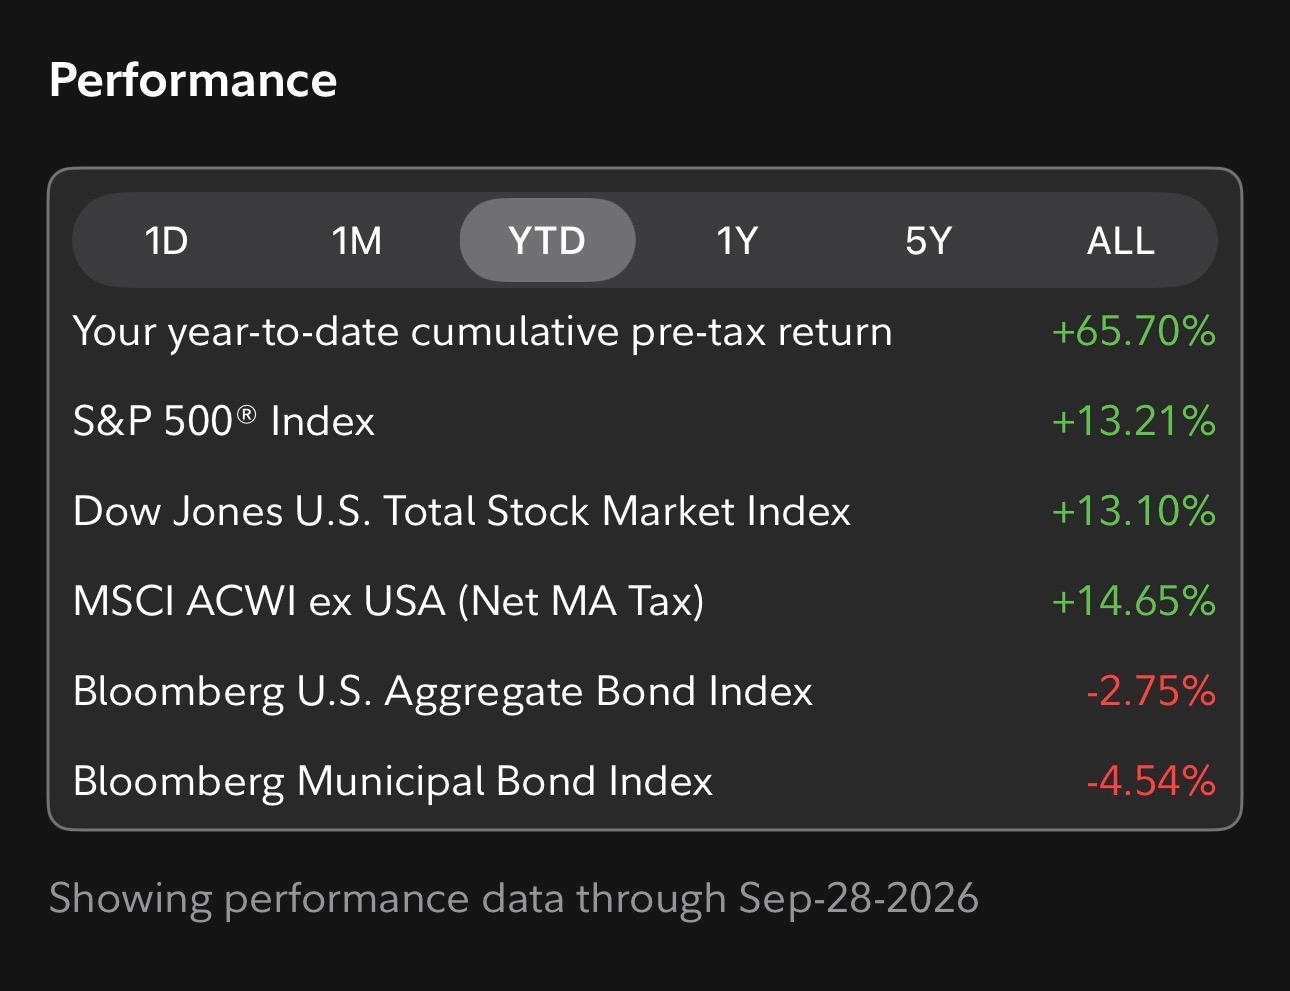
Portfolio returned 65.7% through September 28 versus the S&P 500’s 13.2%, while backing Tourmaline, EQT, Athabasca and SLB on gas demand…

Just buy $QURE every time it drops 50% and sell it when it recovers 100%. It’s happened like 3 times already. Wild one.

$TLN sub $290 was indeed a joke. $1.5bn accelerated buyback, retiring >10% of shares by Q1 2027. $3bn total authorization…
The Greenland trade is played for now. $GRML looks tired, but borrow still runs ~602%, with $GLND at ~684%. The pump may be fading. The squeeze risk hasn’t. Falling borrow fees + returning inventory would make the “party’s over” call much stronger. It would need another news pump item to reignite it.

El Pollo Loco to open first New York restaurant as it aims to become national chicken chain $LOCO
Shell to Double Production Capacity at LNG Canada $SHEL
CarMax Posts Higher Profit as Turnaround Takes Shape $KMX
Piper Sandler Holds Talks to Buy Perella Weinberg $PIPR $PWP
Carnival Logs Higher Profit, Revenue on Accelerating Demand $CCL
SoundThinking to Be Taken Private by Transom Capital Group $SSTI

This game was INSANE!!! Even got to meet some $PBI bros 😉
I have been avoiding posting about $ZD, but it appears they have already purchased a massive amount of shares this quarter. Huge ruling here that will impact their court case. $ZD heading to $100+...
I have been avoiding posting about $ZD, but it appears they have already purchased a massive amping of shares this quarter. Huge ruling here that will impact their court case. $ZD heading to $100+...

@buysidedigest @GHadjia The market has destroyed high leverage type businesses as rates have escalated. $PAR besides its business challenges staying relevant in a new AI world (still to be seen) is caught in the basket with names like XRAY, FOUR, CCOI, PZZA they have all been rapidly sold this month

@The_Pro_Invest @Muneeb0Muzaffar CEO will get fired $FICO

Teleflex $TFX closed the $1.5bn sale of its OEM business to Montagu and Kohlberg, with the deal delivering ~$1.25bn after-tax, and Teleflex paying down $800m of debt and advancing its $1bn buyback (now ~17% of market cap). They bought back $250m worth of shares in the last quarter, and you can expect them to continue this pace over the next few quarters.

@DeepValueStonks Hey, love your content have followed you for a while! Here is what I am using on $BMBL Owner's Earnings:
Ryan Cohen just bought another $10 million of $GME in the open market. This is over $60 million in less than a month. Is there any company with insider buys this big? Wall Street is completely ignoring this stock. They are asleep at the wheel drooling all over their fat bellies.
@alex7frey Very sorry I mixed up my investors it is Chuck Akre with the mental model I am parroting relating to $FICO. Chuck Akre on $MCO and mandated regulatory competition after the GFC. Link:

For the last month I’ve been sharing all the positive developments for $orcl, especially re OAI reaccel. Nobody cared until it’s in their face. Same is true on the ground w/Jupiter. Project will come online. FCF will inflect. Force Majeure is good move.
FTAI Aviation’s engine-exchange model swaps CFM56 engines in days rather than 200-day overhauls, driving Aerospace Products adjusted EBITDA…
$fico

@DeepSailCapital $MRNX via short Mar27 150-200C lots of ways for this trade to work. Its my preferred way to fade the outsized (and in the past 2 weeks heavily autocorrelated) move in $MRNA

$META started ripping when Dottie fumbled
Added back $CRCT short too: One time tariff impacts make the financials look good, but the company is in structural decline: $26.7M of the $47.4M operating income was non-recurring $20.3M of IEEPA tariff refunds and a $6.4M royalty reserve release. Strip them and operating income is roughly half what printed, on revenue that fell 9%. The rest of the bear case: Hardware is in structural decline — down 22%, with lower ASPs on the Joy 2 and Explore 5 launches and heavier promotion. A razor-and-blades model where the razors are shrinking. Platform growth is 5% and subscribers grew 3% to 3.10M. That's the "good" half, and it isn't growing fast enough to carry a declining hardware base. Engagement is flat, not recovering. 90-day engaged users 3.49M against 3.48M. Management framed stabilising active users as a win, which tells you the trend it's stabilising from. Tariff refunds do not repeat. The Q2 comp next year is brutal.
What a bailout for some of the concentrated players trapped in $SSTI. Don't understand the acquisition or how the pe firm will winout but congrats the concentrated layers who entered late last year and can now break even to even make a little money with the voucher. So much regulatory risk for a product that is not well liked, has well funded campaigns against and has not shown to be overly effective. Best of luck
This is what I am alluding to in the Chuck Akre 2011 google talk $FICO
$FDXF has materially underperformed LTL peers heading into October's first standalone earnings call… Market seems to be pricing in a deteriorating earnings story rather than post-spin complexity. If management can provide clarity on standalone financials and reaffirm its margin trajectory, the RV dislocation could close quickly. Interesting asymmetric setup….
$FICO forward P/E means nothing, trailing P/E around ~18x. Relevant mental model may beBill Nygren sand $MCO Moodys post GFC when regulatory expanded agencies from 2.5 to 6 and essentially mandated competition with Moodys. See interview with Google on YT in maybe 2011. We saw how that turned out. Bias: 1 share bought at $870 to scratch an irrational itch. Status: miffed, @wpulte suffers from man with a hammer tendency
$ADEA New CEO hire is exactly what you want to see. She spent last 8 years at $ARM turning semi conducter IP into massive growth + recurring revenue honestly surprised stock is down given how the previous CEO exit had been weighing on the stock

$ASIC has significantly outperformed its more loftily valued peer, Kinsale, by 42% YTD. With Excess and Surplus activity continuing to slow, however, I think Ategrity is no longer the value setup it once was and I've taken profits on the ASIC leg of the trade.

Batch size sets the trade-off between speed and cost in AI inference. An AI server answers many users at once by bundling their requests into one batch. Our $CBRS note compares this to running a bus. There are two ways to run it, and each gives something up. 1. Fill the bus. Put as many passengers as possible on every run. More stops slow each passenger's trip, but the cost of the run is spread across more people, so the cost per passenger falls. Larger batches do the same: each user's answer is slower, and the cost per token falls because the system produces more tokens from the same hardware. 2. Carry fewer passengers and stop less. Each trip is faster, but fewer seats mean the cost of the run is spread less well, so the cost per passenger rises. Smaller batches are fast for one user and raise the cost per token. So in the analogy, speed for each user is how fast each passenger arrives. Cost per token is cost per passenger. A system set up for one gives up some of the other. When someone compares two inference systems, check the batch size behind each number. A speed figure or a cost-per-token figure quoted without it cannot be compared fairly.
ProQR Therapeutics $PRQR CEO Daniel de Boer bought $513K across two separate purchases on July 7 and July 9, and a company director bought another $229.5K in late June (real money for a Dutch CEO). PRQR is a small-cap RNA-editing biotech backed by a major pharma partner: Eli Lilly. Their collaboration, running since 2021 and expanded in 2022, could pay ProQR up to $3.75 billion in milestones plus royalties, real validation for a company this size. The balance sheet just got stronger too: ProQR raised roughly $59 million in late June 2026, with Lilly buying in alongside the public offering to keep its stake intact, a vote of confidence from the partner who knows their science best.

Meta’s Enterprise Platform creates a third-party compute outlet, reducing the cost of overbuilding AI infrastructure while adding…

Paramount's $52bn $WBD debt package is FINALLY in the market. Here's the package: $32bn of IG-rated 1L bonds, the 5th-largest US high-grade sale EVER. Plus $7.5bn of loans and $12.4bn of 2L HY bonds. Paramount's existing unsecured bonds? Primed. Back of the line. Good luck and thanks for playing. Where in the cap stack are you playing? $PSKY $PARA

Selling low vol international stuff and buying risk and rate exposure today (with some hedging using $ANGL, $SMH and $QQQ). Purely a sentiment and positioning thesis. Historically I've been too cautious in these sorts of dislocations so im trying something new.
Fair Isaac $FICO is getting killed today. Looks absolutely hammered. Should deep value guys be buying this today? What’s the worst case scenario here?
Perella Weinberg combining with Piper Sandler is one of those headlines that would have sounded impossible to a banking analyst in 2010. $PWP $PIPR
Archer Aviation's Insitu, Wisk and SkyGrid acquisitions add military and drone revenue, cutting FAA-certification dependence and leaving…
 The Alpha Analyst 4 clicks

@PythiaR I think $SRPT is the undisputed king in this regard, at least over a full career.
Is $70B ARR for OpenAI ahead of expectations? I dunno ask $ORCL
@Menckenist What good real estate does $SGA own?
As per our SaaS Survival Scorecard series, $DDOG is one of the strongest. The only risk is the model labs making a telemetry agent that feedbacks to coding agents regarding what’s going wrong and needs optimizing in production. If they brought this to market, new application stacks with there observability requirements might go to the model labs instead of DDOG.
@everyonehatesp1 I like $EGHT and may join you on the long side soon. However, it needs to grow revenue substantially. Otherwise, its slow but serial dilution will continue to eat away at sales per share.
72% drawdown on $FICO
Why a $MNRO sale is likely imminent: The quarter after the Chairman, Solomon,received millions of shares in exchange for giving up his right to veto a sale of the company - the company initiated a strategic review that was in "preliminary stages." Last quarter that changed to "well underway" and the "financial and legal advisors" became "independent financial advisors Bank of America and Solomon Partners." In regards to valuation. The CEO has a comp package that essentially doubles his outstanding shares if the stock hits $25 and triples them if the stock hits $30. An announcement of a sale of $MNRO appears to be imminent (before year end) especially since Icahn just closed on Pep Boys sale to Mavis and a sale price of $MNRO of at least $25 but possibly $30+ seems probable.

Notes from my May 2026 write up on $SANG Another “strategic review” in the bag…
I think the $FICO bulls have finally suffered enough. We still don't need any more articles about how it's a great compounder, though.
In your opinion Drew does part of the end buyer most still hold due to the years of data and hence better prepayment risk that a $FICO score allows for? In addition I haven’t looked to much but if it’s clear it’s a VS 740 and a FICO 740 won’t buyers still reflect that differential in price because they aren’t completely the same
Good news, however if you are following this please keep cash around as when it is ‘officially’ announced arbs exiting will likely sell it down a good chunk. $ZIM
Kimberly-Clark's 5% dividend yield and Kenvue merger upside outweigh Tylenol litigation risk after a 30% share-price decline.
$ZIM
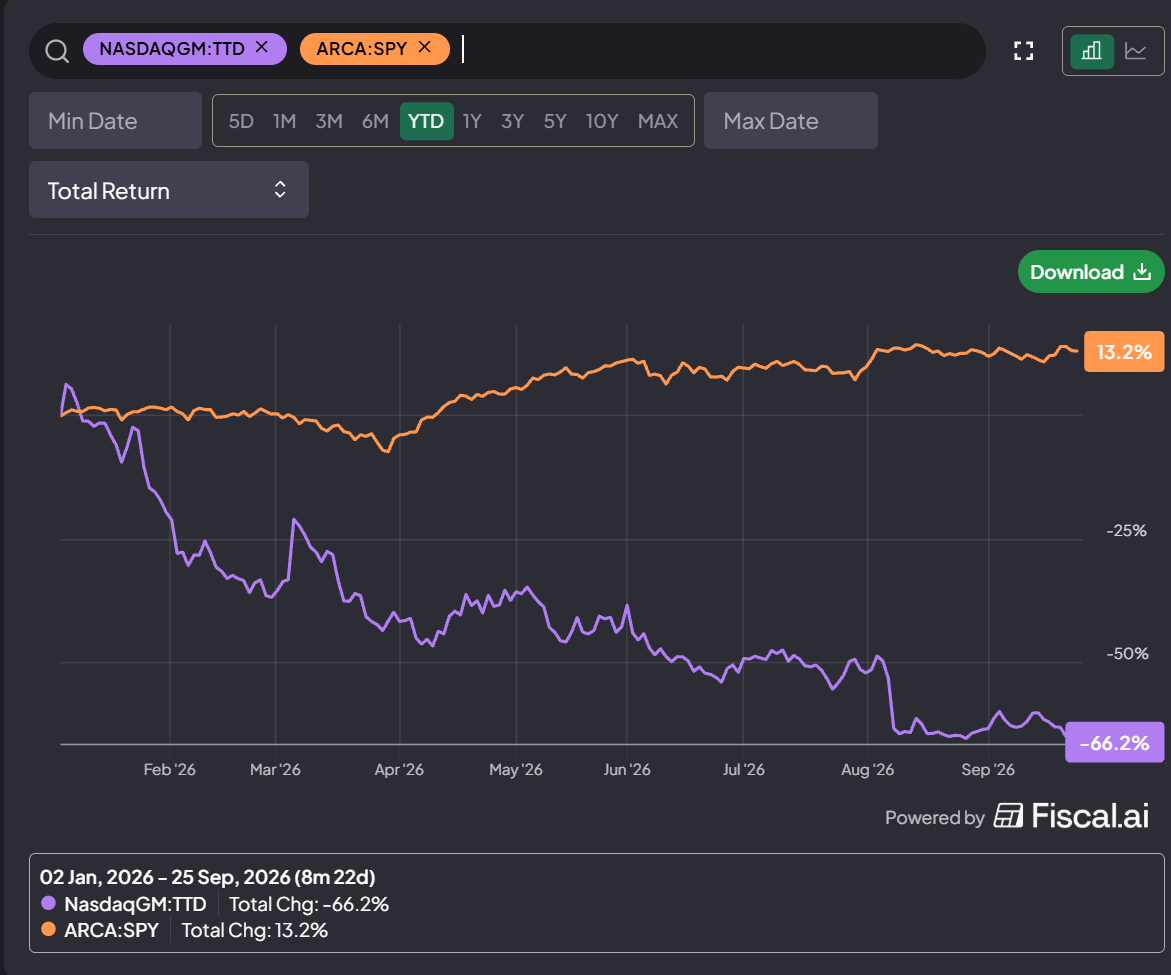
The Trade Desk’s CEO received a new 10-year option package targeting $105 per share as the company seeks shareholder approval to reprice…
Cullinan Therapeutics plans December 2026 autoimmune updates for CLN-978, while zipalertinib awaits an FDA decision in previously treated…
 Myriam Alvarez 2 clicks
Beam Therapeutics’ BEAM-302 AATD gene-editing program anchors its 2028–2029 upside, while a 2–3 year cash runway leaves dilution likely…
 Robert J. Lake
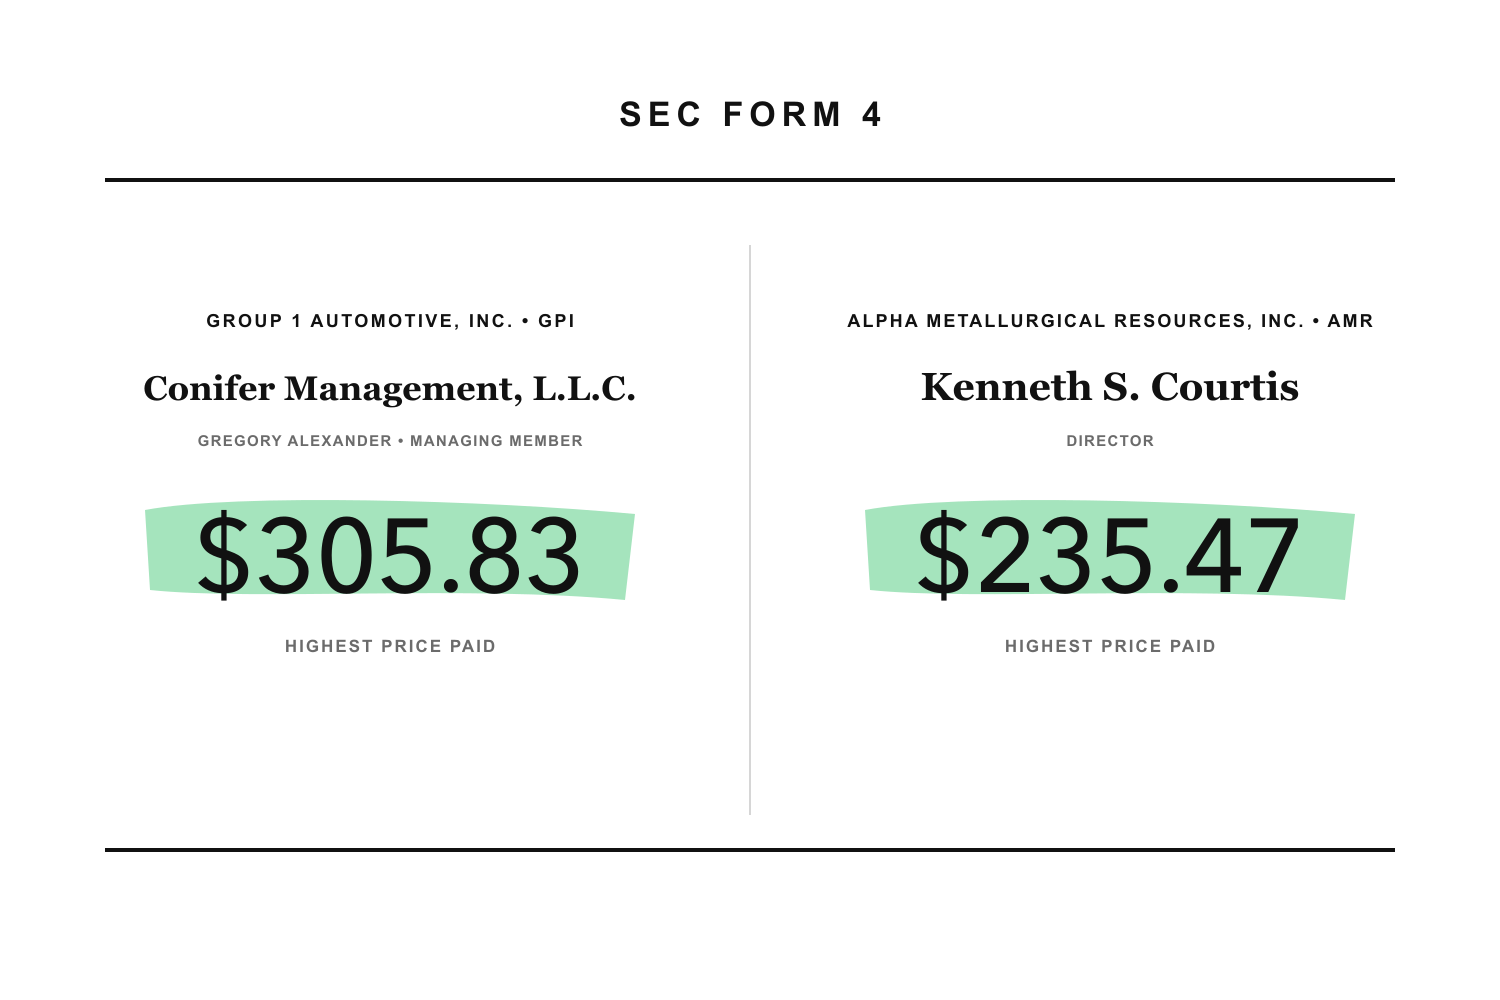
Alpha Metallurgical Resources director Ken Courtis bought $10.5 million above $190 after a blackout lifted, while Conifer’s 12.7% Group 1…
Monte Investments upgrades Karman Holdings to Buy with a $133 target after a 65% drawdown, citing 28.83x EV/aEBITDA and governance changes.

Remember when this compounder turned shitco traded below TBV? $KMX Eventually everything trades like a toaster:
Robinhood’s long-term value rests on retaining customer assets and becoming a primary financial platform beyond trading.
 Thomas Veth 2 clicks
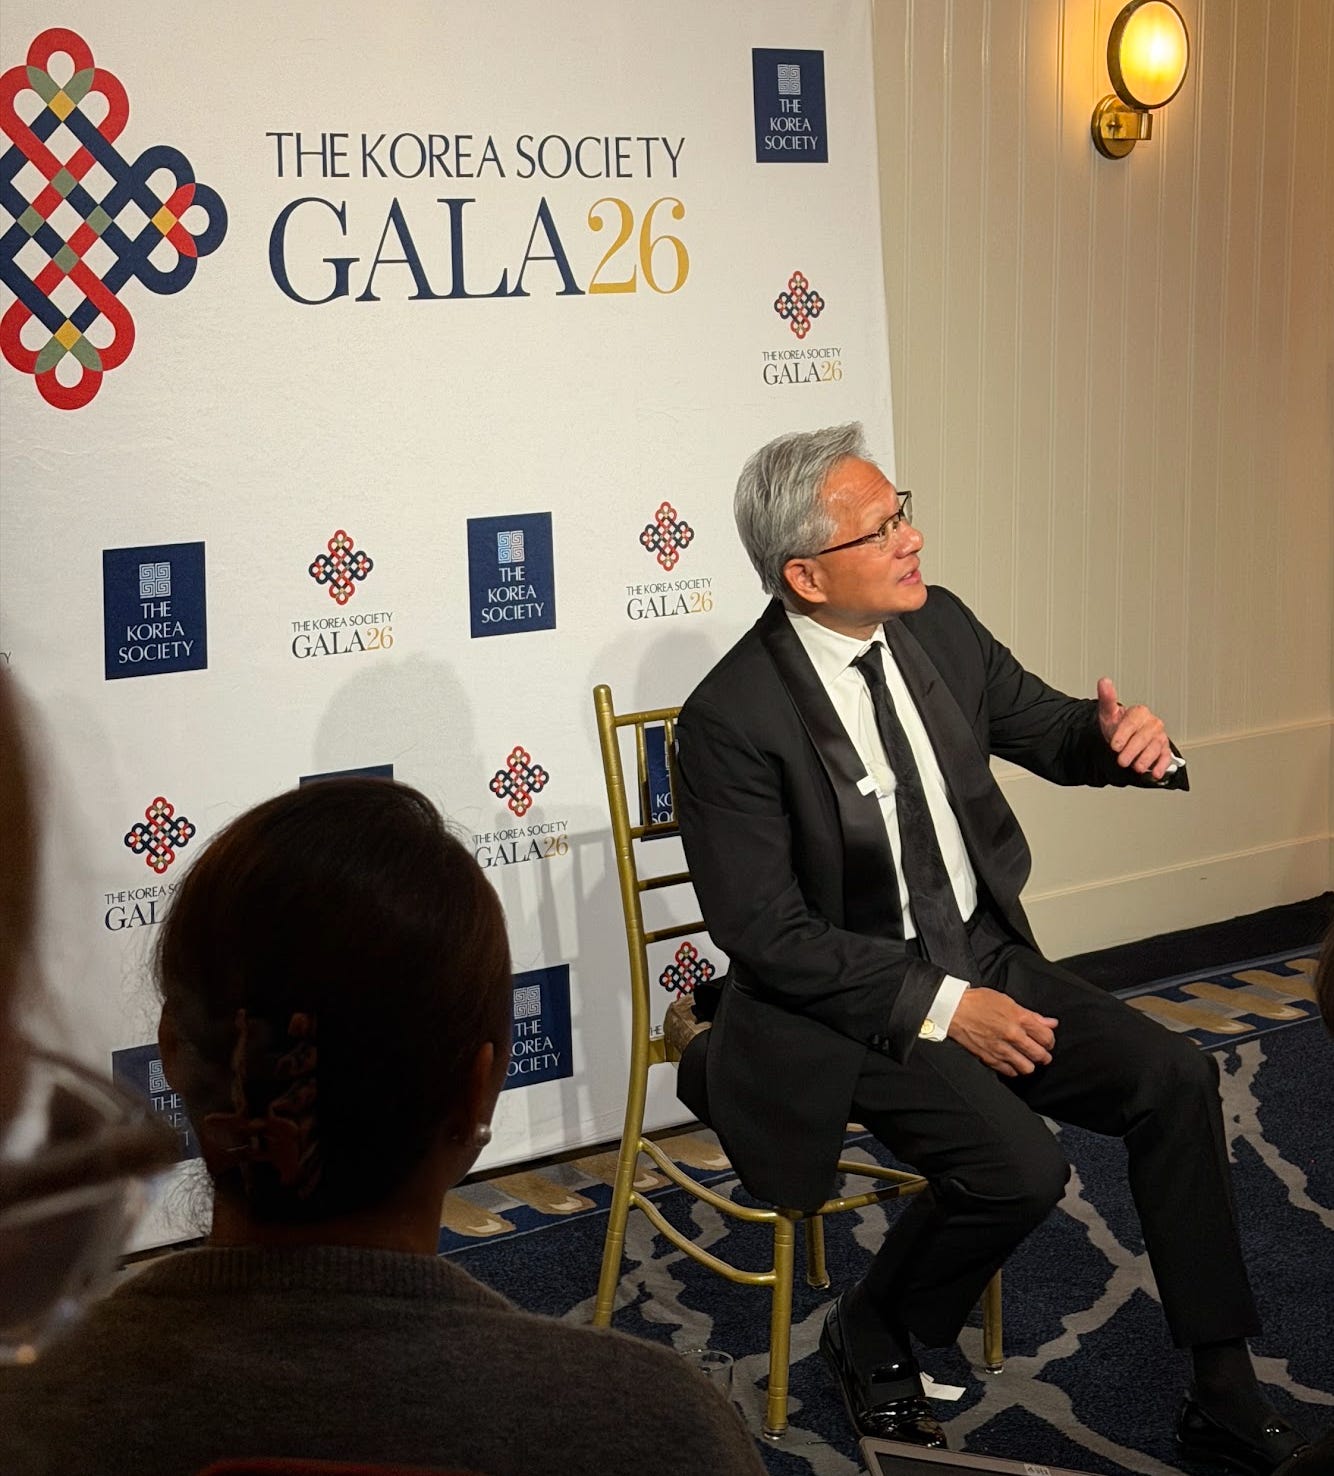
Nvidia CEO Jensen Huang says the company will buy back hundreds of billions of dollars of stock in coming years.
Pfizer’s new products and $9.7 billion cost-cut plan target earnings support through COVID normalization and patent expiries, alongside a…
 Value Capital Research 1 click
Analog Devices expects data center revenue to reach 26.7% of sales by 2029, lifting its five-year revenue growth forecast to 15% and net…
 Khaveen Investments 1 click
Applied Optoelectronics targets $1.1 billion in 2026 revenue as 800G and 1.6T data-center demand drives capacity expansion, despite…
 Infinity Curve 2 clicks

