
Thursday Tailwinds #8: Sep 24, 2026
ResMed benefits as Eli Lilly-funded sleep-apnoea diagnoses expand PAP demand, while NOV’s geothermal cutters and Po Valley’s unhedged…
Sector
Everything our editor has picked under this sector, best first.
160 stories
ResMed benefits as Eli Lilly-funded sleep-apnoea diagnoses expand PAP demand, while NOV’s geothermal cutters and Po Valley’s unhedged…
@caseyjdonaldson @lhamtil I made 6-8x on $CNQ calls from that time period. I expect to make 3x on my long duration U.S. gov bonds ($EDV specifically). Could do better with calls but I don't have a strong view on exact timeline it plays out.
Love me some microcap crap. $GLND, an early-stage oil exploration company in Greenland, has just more than doubled in value. Well, of course, the Greenland-Denmark-US security agreement was announced. It all makes sense now: there is oil in Greenland, so obviously the agreement means the oil will be extracted. Perfect connection. To be serious, though, this is one of the most promotional stories I’ve seen recently. Why? GLND plans to drill what the CEO claims could be $1T worth of oil reserves in Greenland. The problem is that not a single well has ever been drilled on this land. The company does not even have the green light to drill yet. And btw, GLND doesn’t even own the licence. $80M.L owns it and is currently being acquired by GLND. The spread is extremely wide, but I wouldn’t touch it. The whole thing smells fishy. 80M.L and its management also have a terrible track record of dilution built around promises of enormous exploration potential across other Greenland projects. Unsurprisingly, very little came of those stories. The worst part here is the media coverage. It largely misses the promotional nature of the story and instead keeps feeding the Trump/Greenland narrative that management appears happy to lean into. That is also why you now get a huge move in GLND on a security agreement that, as far as the underlying oil project is concerned, changes essentially nothing. Microcap world is a fun place to be.
Atlas Energy Solutions expects proppant price recovery and a 2GW power business by 2030 to lift EBITDA, alongside low-cost Permian sand,…
 Ron Ferrie 2 clicks
Long $BORR https://t.co/W0xvygRBPr
Chevron plans drilling spree as it overhauls oil and gas search $CVX https://t.co/aZV7kguxYR
Southwest Airlines targets more than $2 billion of 2026 EBIT from assigned seating, extra legroom and bag fees despite higher fuel costs…
 Dhierin Bechai 4 clicks
 NINE · long
Nine Energy Service (NINE) is a domestic onshore oilfield-services consolidation play as U.S. rig counts show early signs of recovery.
Disclaimer: I have sold this position and have no view on the valuation or future prospects My craziest OTC adventure this year was discovering a single-asset refinery that sells Jet Fuel to the US Military. It sounds kinda crazy, but it's the exact type of ridiculous setup funny enough to look into. In July, refining crack spreads were blowing out, and nearly every refiner $PBF, $PARR, $VLO, $PSX were steamrolling. I wanted some exposure, but I felt sheepish chasing names that were already tearing it up. I started looking at smaller refiners, but nearly everyone was in the 3x - 5x forward earnings range, not expensive, but for a cyclical, also not really that cheap. It turns out that, aside from the megacap refiners and $PARR, there's only one other US listed microcap refiner, Blue Dolphin Energy $BDCO. The stock is heavily insider owned, and at the time, was trading at just over 4x Q1 earnings ($0.99). Crack spreads are publicly viewable, and other refiners were demolishing estimates - $PARR came in at $11 in Q2, triple Q1, so it didn't take too much math to realize BDCO's Q2 was gonna be strong given jet fuel prices, and that the stock was potentially trading under 1x forward earnings. Of course, it's an OTC name with limited liquidity so you can't realize size it up, but how often do you get a chance to buy someone who supplies jet fuel to the Department of Defense under 1x annualized earnings? It was almost comedic, the story was funny enough to swallow the OTC stigma and just pick up a little bit up. About a week later, Q2 results came in at $1.19 (putting 1H earnings at ($2.18), and the market suddenly realized a stock trading at $4 on $2.18 of two quarter's EPS was just too cheap. The stock hit $18 today - I've been trimming since entry and am finally out. It was a tiny position, but I continue to find it ridiculous that these OTC setups exist. With a small amount of capital and a love for reading filings, you can probably find a slew of OTC names that are actually decently profitable that are simply too small for larger investors to take a stab at. I have no position in BDCO and have no opinion on it, $4 and $18 are totally different prices, but the fact this setup existed and somehow flew under the radar until earnings is pretty entertaining.
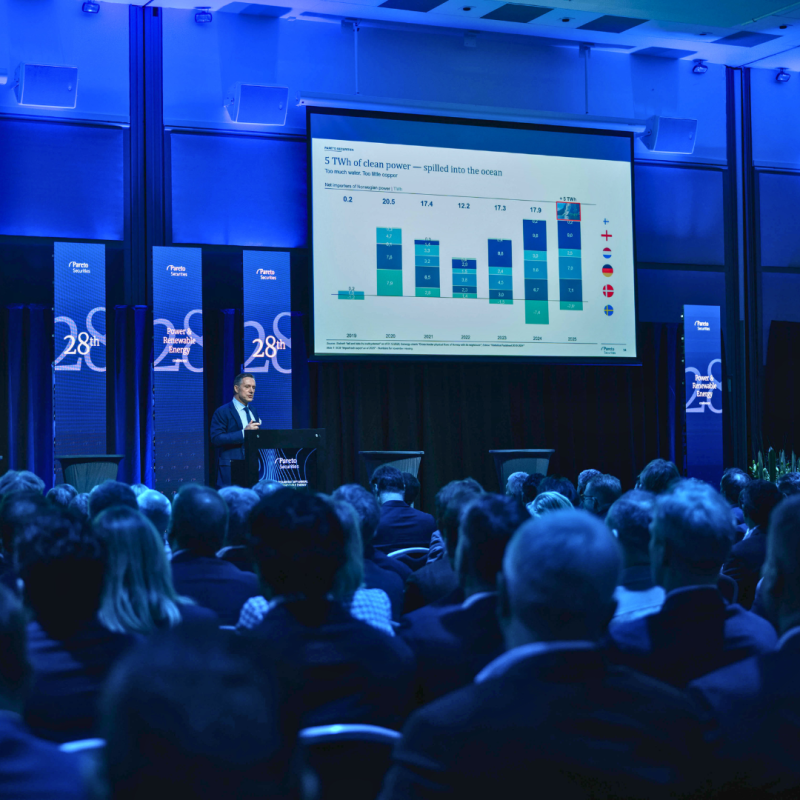
Offshore drillers have secured 105 rig-years by September, 42% above all of 2025, as national oil companies lock up long-term capacity.
PBF Energy benefits from elevated crack spreads as refinery capacity cuts and oil prices support margins, with 67.5% of spread increases…
 Andres Veurink 4 clicks
Enbridge’s 5.1x leverage and $6.45 billion of 2027 maturities raise refinancing pressure as Venezuelan exports and new Canadian pipelines…
 Melissa Tucker 4 clicks
 EFXT · long
Enerflex, a $3 billion natural gas infrastructure and equipment company, blends contracted energy-services cash flows with equipment…
BKV Corporation is pursuing PPAs for its Temple power capacity by early 2027 to improve cash flow visibility while capex and equipment…
 Capital Connoisseur
Borr Drilling expects rising jackup demand and a 2028 earnings inflection after refinancing debt on improved terms.
 Henrik Alex
 BKV · long
BKV Corp, public for less than two years, is an underfollowed natural-gas producer pursuing early-stage projects and a transition.
You're seeing a lot of bullish commentary from energy executives these days, yet I don't see a ton of M&A activity .Why isn't $CVX buying more unhedged crude centric producers? Where are the monster M&A deals? Obviously no board is going for that and most of these executives wouldn't either. Hence, I take all that's being said with a monster grain of salt. The secular trends still matter more.
Plains GP Holdings cut leverage to 3.3 times adjusted EBITDA as Permian volumes and distributions rise, while $8.44 billion of debt faces…
 Vishal Jadaun 1 click
Talos Energy is raising standalone production guidance without added capex while using offshore cash flow to fund Shell acquisition and…
Capital Connoisseur 
New Fortress Energy’s UK restructuring extinguished $7.5 billion of debt, but common holders retain 35% behind a large preferred stack…
 Eborose Capital
Cannibal Stocks favors cash-generative companies that retire shares at low valuations, citing Dillard’s 80% share reduction and…
 SCEYF · long
Source Energy Services is Western Canada’s dominant integrated frac-sand producer and logistics provider, supplied by three Wisconsin…

USA Compression targets nearly 30% full-year EBITDA growth as JW Power synergies, telemetry and maintenance reduce costs; its units yield…
Ron Ferrie 3 clicks
Chevron’s 2027 EPS could be underestimated by about $4.50 per share if U.S.-Iran conflict keeps oil near $100 rather than forecast $74 to…
 Envision Research 1 click
