
John_Hempton on X
@Benthom41722354 $NWBO needs no introduction. Such a bozo operation. Never heard of $AABB
Sector
Everything our editor has picked under this sector, best first.
178 stories
@Benthom41722354 $NWBO needs no introduction. Such a bozo operation. Never heard of $AABB
UBS on $CENX Oklahoma optionality “The only real growth story in aluminum, or meaningful shareholder returns” https://t.co/56beYZN7hE
ContextLogic will acquire specialty-solvent maker gChem for $850 million, funded by a $650 million rights offering and $250 million of…
Macompta.fr targets France’s four million mandated e-invoicing buyers; GEE Group, a Korean auto-parts maker and a Nova Scotia zinc mine…
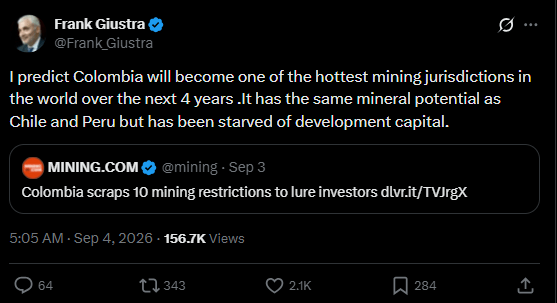
Tecnoglass could recover tariff- and FX-hit margins as U.S. blanket tariffs on Colombian goods lift.
Titan Mining reported Q2 revenue of $25.7 million and adjusted EBITDA of $9.6 million as zinc output rose, while advancing its Kilbourne…
SSR Mining holds $1.8 billion cash with no debt after exiting Turkey, while higher costs persist.
 The Supercycle Investor 2 clicks
McEwen Inc. targets production growth from 115,700 ounces in 2025 to 300,000 by 2030, with Los Azules copper optionality and a McEwen…
 The Bullionaire
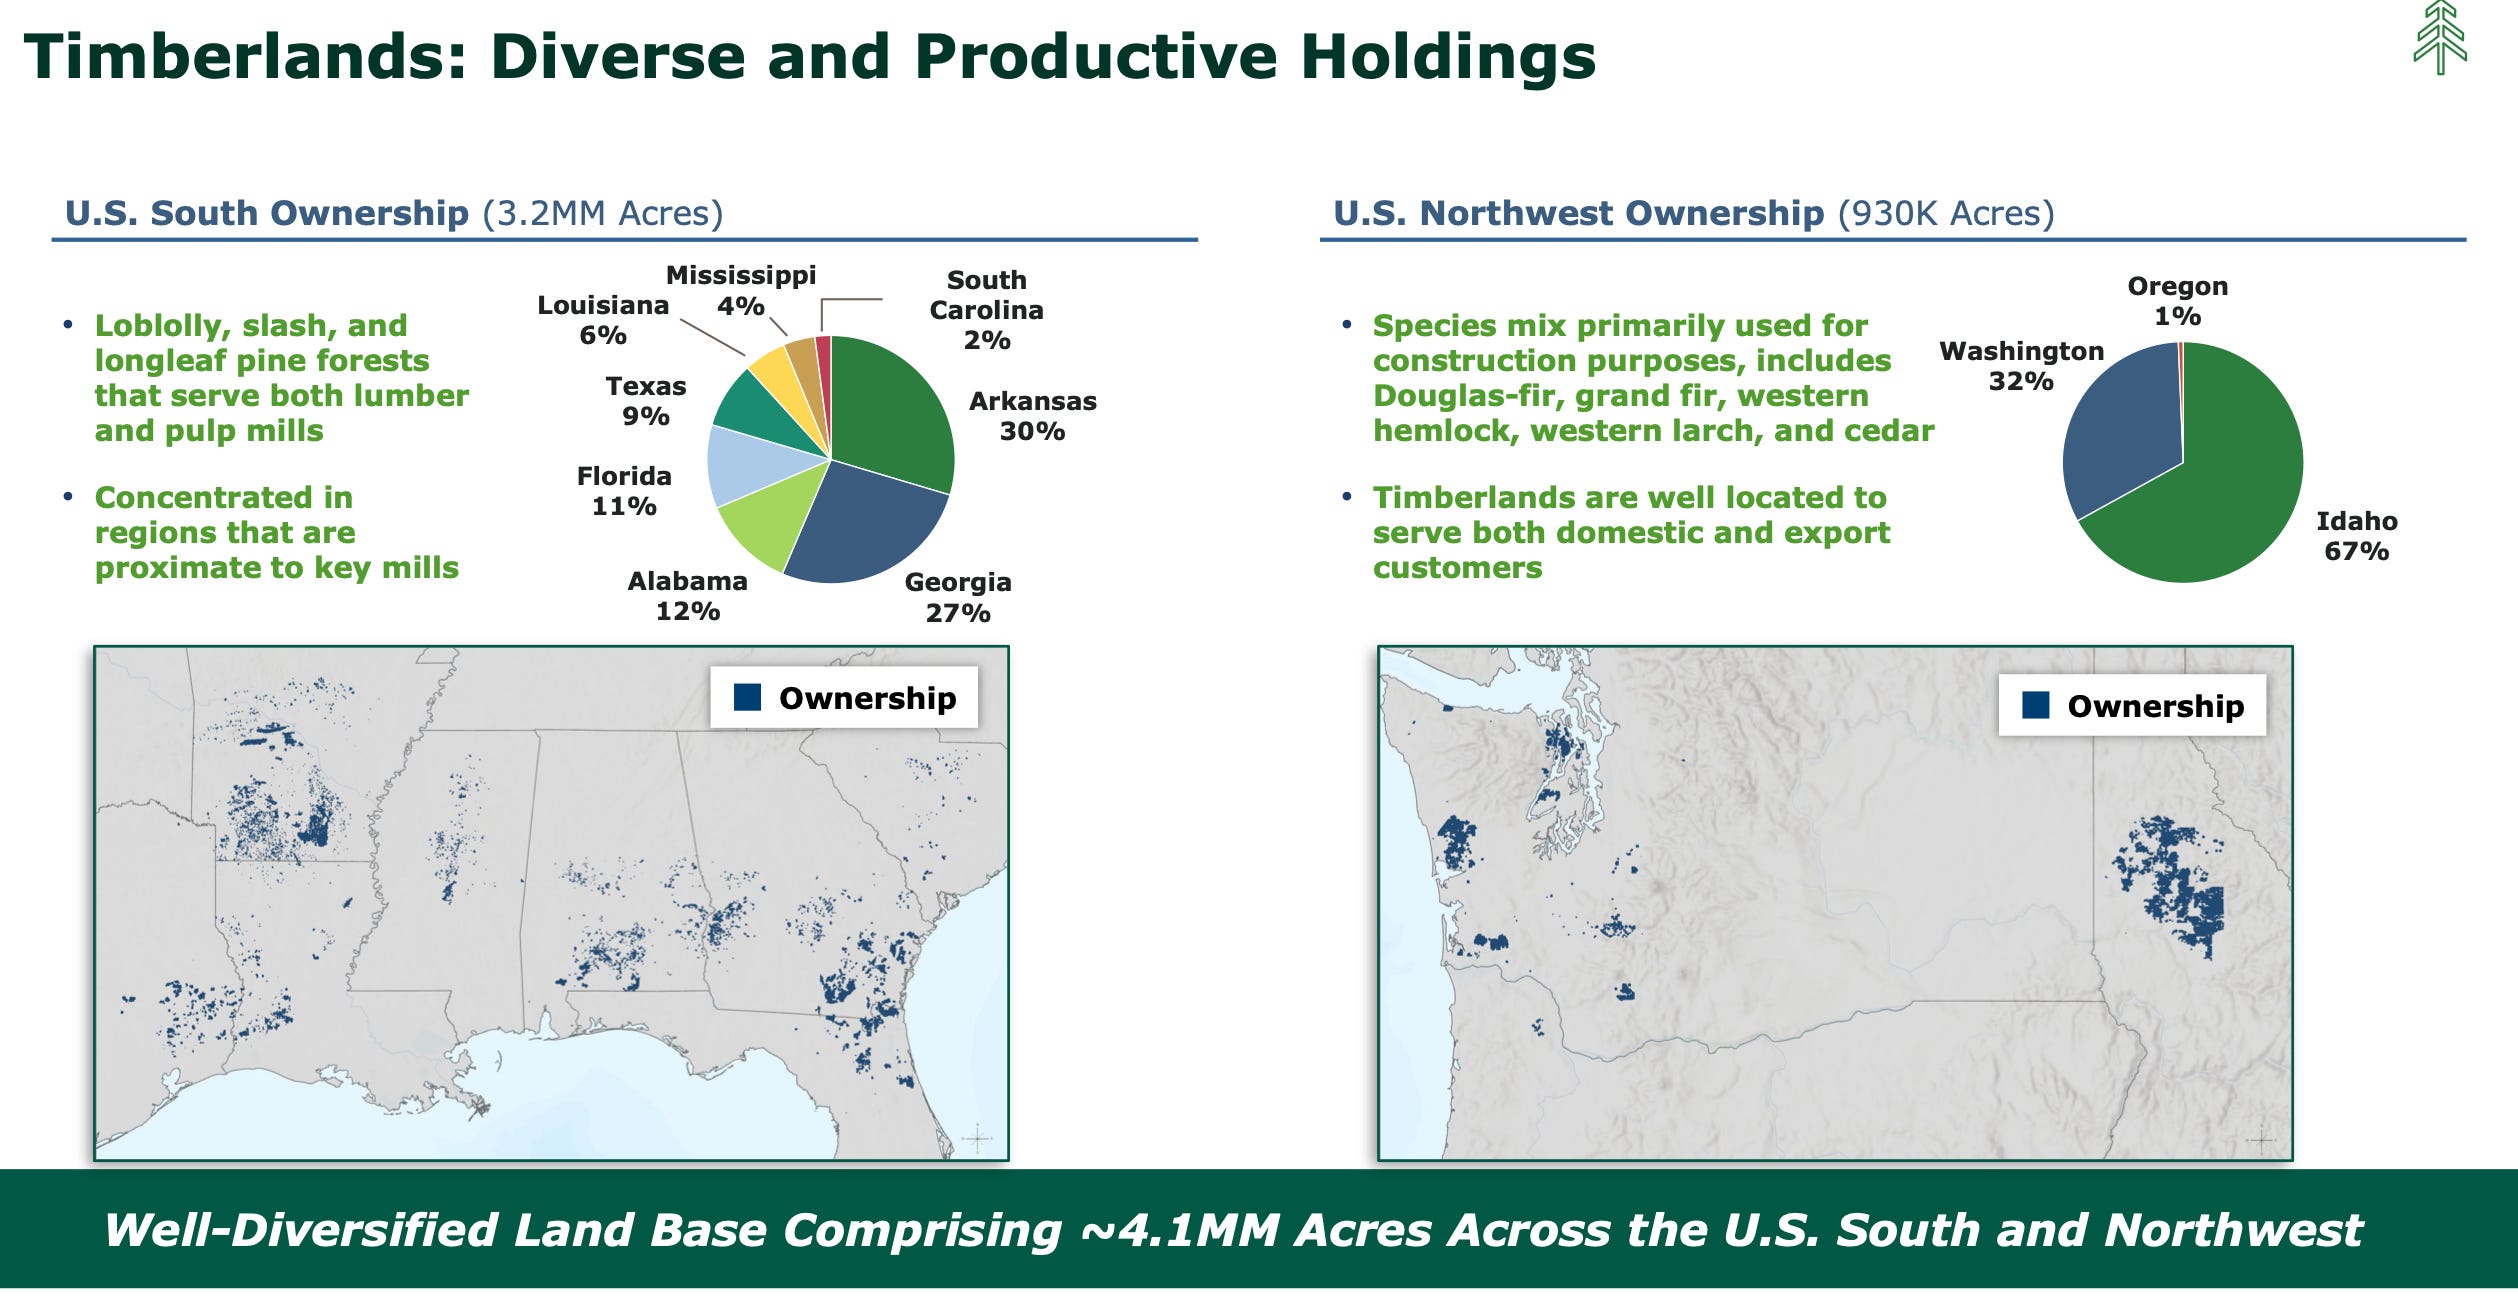
Rayonier’s 4.0 million acres are valued at $393 an acre after other assets, versus $1,200 to $1,800 cutover-land sales, framing the timber…
This man is probably an activist investor in $RYN trying to create his own catalyst by removing timber supply from the market. Heard he has an MBA from Wharton too and his wife hates him. https://t.co/sAp2HUFNaO
UBS: We believe $CENX offers the best leverage to a US Regional Premium that is sustainably higher. CENX currently trades at ~3.1x UBSe 2027 EBITDA estimates (below ~5x normalized 5yr average). We expect CENX to rerate towards our ~4x peak multiple driven by clarity… https://t.co/93RbEN5Ex7
Rayonier $RYN owns 4,003,000 acres across eleven states. Here's what happens when you value everything else on the balance sheet and subtract it. Enterprise value is $7.64B. Market cap $6.19B plus $1.45B of net debt. Now take out the pieces that aren't dirt: Six sawmills and a plywood mill, $1.0B. Cross-checked two ways. Replacement cost runs ~$700/MBF on 1,155 MMBF of capacity. Mid-cycle EBITDA of $175M at 6x gets you the same place. Three master-planned communities, $482M. Wildlight north of Jacksonville, Heartwood next to Hyundai's $7.59B plant in Georgia, Chenal Valley in Little Rock at 70% sold out. DCF'd at 12%. The rural land program, $650M. They sold 7,490 acres at $5,439 last quarter against a portfolio the market marks at $1,447. That 3.7x spread on ~30,000 acres a year, decayed and discounted over a 13-year runway. Solar options on 77,000 acres, $125M at a 25% conversion assumption. Carbon storage across 154,000 acres, $80M. Smackover lithium, $30M. Real geology, ten cents a share. The below-market debt mark, $130M, audited on the balance sheet. That leaves $5.14B for the timberland. Now subtract the trees. 188M tons of standing merchantable inventory at current TimberMart-South stumpage, with pine sawtimber at $23.34/ton and pulpwood at $5.40, is $3.57B. Residual: $1.57B of bare land across 4,003,000 acres. $393 an acre. Cutover land in the South, meaning ground that was just harvested with zero merchantable timber on it, transacts between $1,200 and $1,800. Three marks you can check yourself: In August the company sold 36,000 Washington acres at $4,028 and bought 57,000 Texas and Alabama acres at $2,561. Same month, same management. They paid 77% more than the market credits them for what they already own. Morgan Stanley's fairness opinion produced $47.55 to $55.80 on a DCF and $20.85 to $25.20 on trading comps in the same document. The stock is at $20.81. That gap is institutional cost of capital at 7% versus public equity demanding 9 to 10%, applied to an asset with thirty-year cash flows. Management bought back 4.9M shares for $103.5M in H1 and repaid a $200M term loan with cash rather than refinance it. I built the whole thing a second way, from transaction comps by state instead of tons and dirt. $31.80 versus $31.66. Bear case marks the entire South at $1,700/acre, puts the mills at a trough multiple, converts solar at 15%, and still lands at $24.74. Every case sits above the current price. One caveat I'll state myself: the $393 assumes rural HBU is a separate asset. Treat it as embedded in land value instead and you get $555. Still under cutover. The conclusion holds either way. Full work, every input shown, plus the part about the debt structure that I think almost nobody is modeling, linked below.
Mosaic’s potash business remains profitable, but negative phosphate margins, elevated sulfur and ammonia costs, and negative free cash flow…
 DCF Value Investor 3 clicks
Valuation firm finally appointed for $CPAC. This starts Holcim’s 60-business-day clock to launch the mandatory tender. Floor price firmly set at around $13/ADR, with some upside optionality from the independent valuation. https://t.co/hPCFKmYQvT
$GSM Ferroglobe up today on announcement of a European review of antidumping measures on Chinese silicon metal Has been in a volatile trading range for years, but potential bull points appear be stacking up. (I own long dated calls, watchlist stock)
I think my $ORR position is too large because I made the same mistake I see a lot of investors on here make. I didn't have enough good ideas, so I bet too big on my best idea.
@sophieanalytics Sweet thanks. Haven't dug much in $WY yet. Just been doing $RYN. So WY doesn't do much HBU?
Andrada Mining’s Uis ore sorter targets higher tin grades and lower unit costs after FY26 operating cash flow reached £4.7 million, but…
@valuedrift $LODE
Cleveland-Cliffs' 2027 upside depends on contract resets and Stelco earnings, while management directs free cash flow to deleveraging…
The Bullionaire 1 click GRLRF · long
Greenland Resources, a Canadian-listed miner valued near US$140 million, is developing the Malmbjerg molybdenum project in eastern…
Aduro funded R&D and pilot-scale development through equity raises, warrant conversions and $5.5 million of share-based compensation while its pre-revenue operating losses widened.
$CPAC is +16% since the SSI write-up, and the key tender-price ambiguity is finally resolved. ~$13/ADR now looks like a solid floor. With much of that already priced in, the remaining upside is mostly valuation/overbid optionality. Full pitch on SSI👇 https://t.co/J8Amvtfqou
Rayonier’s $1.86B debt costs 2.29% after swaps and Farm Credit patronage refunds, giving its four million timber acres a cheap fixed-rate funding edge through 2028-29.
