
junkbondinvestor on X
$FMC bonds down 70 points in the last year. Jeez. Generics took pricing, distributors sitting on expensive inventory, and FMC now taking a $625-675mm hit to clear it Bonds down 38pts last week alone... https://t.co/CL6xOPeSfD
Sector
Everything our editor has picked under this sector, best first.
178 stories
$FMC bonds down 70 points in the last year. Jeez. Generics took pricing, distributors sitting on expensive inventory, and FMC now taking a $625-675mm hit to clear it Bonds down 38pts last week alone... https://t.co/CL6xOPeSfD
@MeadowsPoppa @finviz_com definitely worth pulling up the "down 25% in a month" list and see what is getting hit: - a lot of biotech - data centers/HPC computing - entertainment ($SPHR / $MGM / $FUN ) - junior materials (lithium, uranium, rare earth, precious metals) https://t.co/X0XPLzILUX
Aya Gold & Silver quadrupled Zgounder production, lifting shares 331% since early 2025, while Boumadine targets another fourfold increase…
 Laurentian Research 2 clicks
Nexa Resources trades 2% below Boliden’s implied tender value after Boliden agreed to buy a 64.68% stake at a fixed 0.25-share ratio,…
 Sidharth Kumar 1 click
$CPAC played out as expected, returning +18% in six months. The remaining 2% spread should close with the offer, expected between mid-November and mid-December. Full pitch on SSI. https://t.co/p8kx8nA0hK
Alcoa Posts Higher Third-Quarter Profit, Sales on Increased Production $AA https://t.co/4VwFeELF1e
Adjusted EBITDA should be lower than Q2 and last year's Q3 (this year's Q2 was actually higher than last year's Q3!). But EPS should definitely be above analyst estimates and could possibly top Q2 EPS. Market doesn't understand how the hedges on the specialty alcohol work. Q2 EPS were penalized simply because the price of ethanol fell a bit during Q2. Well... during Q3, the price of ethanol rocketed higher. Therefore, even though Q2 had a much better average crush margin than Q3, it's possible Q3 could have higher EPS due to how these hedges work. To be clear - on an annual basis - the hedging has no impact. $ALTO is just locking in profit margin. But since it's not hedge accounting... it has an impact on each quarter's earnings. ALTO's business is operating very well. They're posting quarter after quarter of profitable earnings. Q4 should be solid as well and crush margins are strengthening again. Once California E15 kicks in (1/1/2027) then margins will strengthen further. Additionally: It sounds like passage of farm bill that includes E15 is very likely by end of this year. Check out this Politico article highlighting how the GOP is likely to pass a ton of stuff before the end of the year: https://t.co/3VL4DjDnzy "Such a bill, he added, would be “giant” and would include “all the Republican priorities that we can get done.” The House approved a framework for a party-line bill over the summer that includes war funding, farm aid and election integrity incentives. But the push has so far run aground in the Senate Moreno said the threat of imminent Democratic control of either the House or Senate would jump-start matters — and potentially push Republicans to include a debt-ceiling increase as well." "Moreno said if Democrats win control of both chambers, Republicans should stay in session nonstop to pass GOP legislation — which could be a tall order given worries about poor post-election attendance. “If we lose the House and the Senate, we should be here from Nov. 9 until Dec. 31 with no break at all,” Moreno said. “Like, we’ll have turkeys here for Thanksgiving because we have to get this done.”"
Example: $FMC down ~40% premarket on "horrendous" guidance https://t.co/EvQvUTqGV0
Wow - $GLND is uniquely positioned to capitalize on this! https://t.co/xjVZnf563K
@JCann777 @grok how has $TMC stock performed since this tweet on 8/23/26?
Albemarle posted a 20-fold Q2 profit increase and $638 million of free cash flow as lower lithium prices drove its shares down 40%.
 The Supercycle Investor 2 clicks
 ABSSF · long
AirBoss is a large North American rubber producer moving away from its existing business mix.
$OC: Trading at an $11B market cap and 5x EBITDA, Owens Corning (NYSE: OC) presents a compelling asymmetric investment thesis as a forecasted >90% probability 2026/2027 "Super El Niño" prepares to drive massive, non-discretionary, insurance-funded roofing repair demand across the Southeast United States. Historical parallels from the 2015–2016 and 2023–2024 El Niño cycles demonstrate clear operating leverage, where severe storm activity doubled roofing EBIT and generated 2x to 3x stock returns within 12 to 24 months. Modeling a 35% (base) to ~50% (bull) EBITDA expansion at a standard 9x EV/EBITDA multiple points to a 2x base-case to nearly 3x bull-case upside over the next 12 months, supported by a ~2.5% dividend yield and tactical plant expansions in Ohio and Alabama. Primary risks include asphalt input price spikes linked to high crude oil prices and ongoing integration or tariff friction from the $3.9B Masonite acquisition. However, the thesis features a deep margin of safety anchored by a elevated trough EBITDA margin floor of 24–34% (up from 13–16% in past cycles), cost-saving vertical integration via in-house asphalt oxidation, and strict insurance policy timelines that compel homeowners to replace damaged roofs regardless of broader macroeconomic weakness.
Brazil Potash has secured court support and a power agreement, but financing, dilution and potash-price-sensitive EBITDA remain central…
 Wolf Report 3 clicks
OceanaGold trades below its mine value despite US$655 million of cash and no debt, with production set to dip before Wharekirauponga begins…
 The Bullionaire 1 click
Namib Minerals posted H1 adjusted EBITDA of $19.0 million, up 76%, as higher gold prices offset lower production.
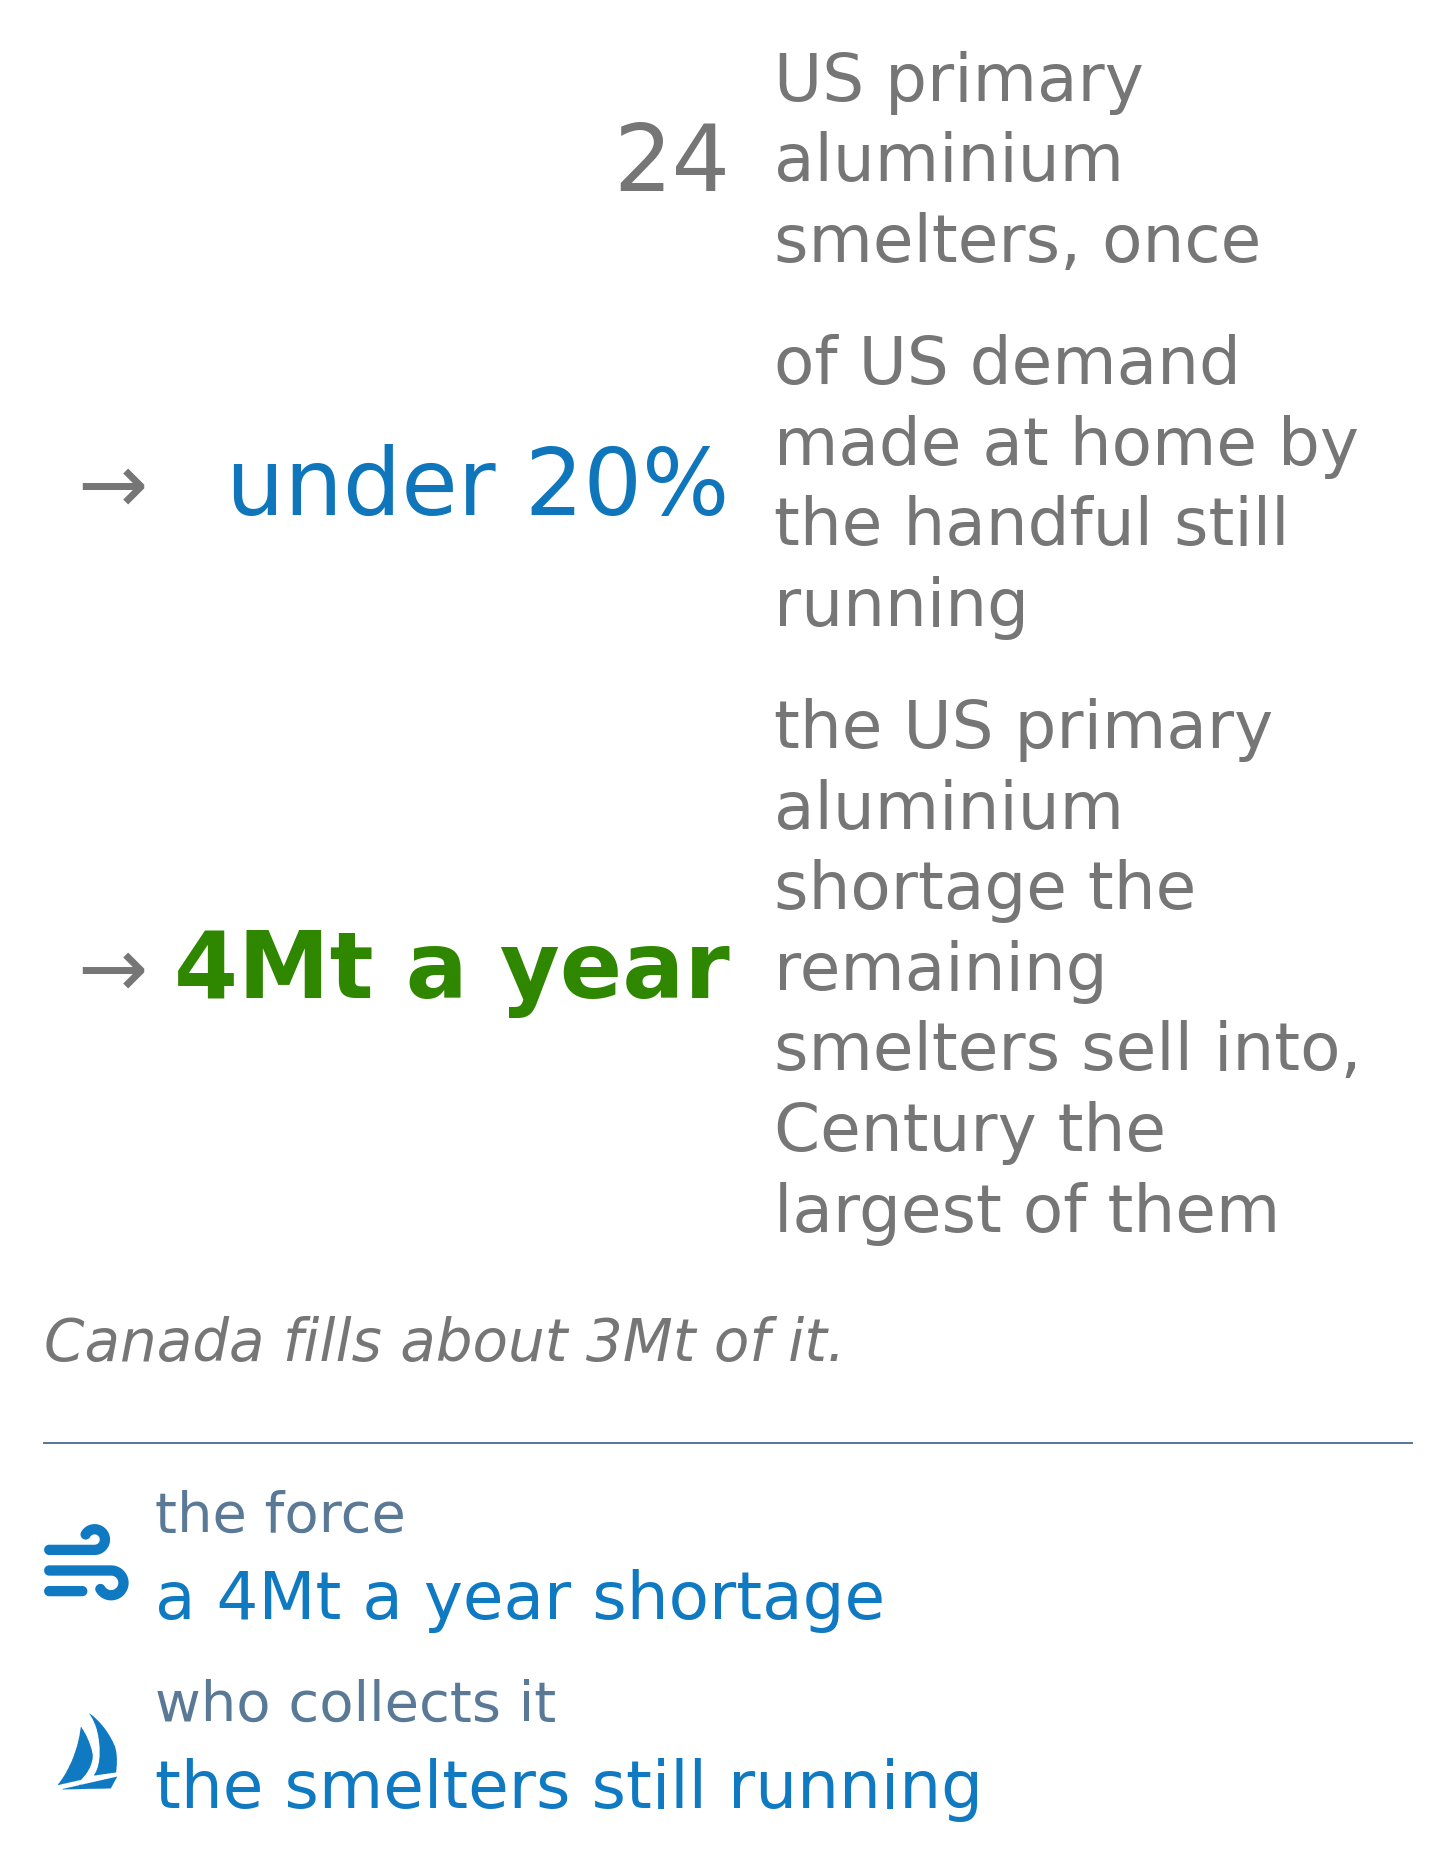
US aluminium tariffs, European glass automation and Foraco’s constrained drilling fleet create multi-year pricing tailwinds, with Century…
Bernstein on China aluminum ceiling: The ceiling has moved from distant policy to binding constraint. China introduced a 45mtpa aluminum capacity ceiling in 2017, but the limit only matters now. Operating capacity reached 44.8mtpa in 2025, with utilization at around 98.5% $CENX https://t.co/MO6I7y1m2W
I listened to ~17 interviews with Jason Jessup, the CEO of Magna Mining $MGMNF (TSX: $NICU), from October 2025 to September 2026 (for my deep dive). For context, Magna owns McCreedy West, a producing copper mine in Sudbury, Ontario, plus Levack and Crean Hill, two past-producing mines it plans to restart. Here are the most important takeaways I got from those interviews: 1) Levack could be 2-3x McCreedy West: Jessup expects “possibly two to even three times” McCreedy West’s payable metal from Levack (The Resource Update, September 8). 2) R2 isn’t in Levack’s upcoming study: R2, a high-grade zone Magna found at Levack in 2025, could produce “10 to 15% copper equivalent material” even with 1-2 tons of waste mined per ton of vein (KE Report, July 10), 3-4.5x McCreedy West’s grades, and Jessup says the zone carries “no streams or royalties on the precious metals” (KE Report, April 20). 3) No more equity raises, he says: With CAD$140M coming from Alpayana, a private Peruvian mining group, for 19.9% of Magna, Jessup said “we could have five mines in production in 5 years and not have to ever do another financing again” (KE Report, July 10). 4) But three timelines moved back: (1) Levack commercial production went from “a good possibility” by the end of 2027 (KE Report, February 20) to 2028 (KE Report, July 10), (2) Crean Hill grid power from as early as Q1 2026 to Q4, and (3) the R2 resource estimate from the end of 2026 or start of 2027 to “potentially by the end of 2027” (Mining Stock Daily, August 13). 5) Skin in the game: Jessup says he owns ~10.6M shares, has “never sold a share,” and wants “a $5 billion company” by 2030 (Natural Resource Stocks, July 20), 6.5x Magna’s CAD$768M market cap at CAD$2.45/share. Levack’s PEA and Crean Hill’s pre-feasibility study are both due in October, and Jessup expects a formal Levack restart decision “shortly after seeing the PEA come out” (Mining Stock Daily, September 24). --- Link in bio to find the deep dive.
need more $GLD $GC https://t.co/sC4KNVanQw
10 of the 11 insider trades at Magna Mining $MGMNF (TSX: $NICU) since November 2024 were buys, and its CEO says he’s “never sold a share.” CEO Jason Jessup owns 10,441,196 shares, 3.3% of the count, mostly held through Mine Management Partners, a holding company. Five of the 10 buys came from Magna’s November 2024 financing, where insiders including Jessup and Dundee Corporation $DDEJF, a Toronto investment company, took new shares at CAD$1.05. No officer or director sold shares in the open market between November 2024 and March 2026. The only open-market insider buys were incoming CFO Greg Huffman’s 5,200 shares at CAD$2.10-2.35 in March 2026 and director John Seaman’s 10,000 shares at CAD$1.41 in December 2024. The only sale came from TFG Asset Management, part of Tetragon Financial Group $TGONF, which sold 15,000,000 shares at CAD$2.62 (US$27.7M total) on October 3, 2025, two weeks after Magna’s CAD$2.40 share offering. TFG was a 10% holder at the time. Here’s the management team: → Jason Jessup (CEO and Director): 25+ years in mining at FNX Mining, Sandstorm Gold, Premier Royalty, and Inco. At FNX, he “led the team there to restart the mine in the Morrison deposit” at Levack, now Magna’s flagship restart project, and he says FNX returned “about 4200%” from 2000 to 2010. → Jeff Huffman (COO): Joined in November 2023; most recently President and COO of Dumas Contracting, an underground mine contractor. → Greg Huffman (SVP Capital Markets, incoming CFO): Global Head of Mining Sales at Canaccord Genuity $CCORF, the Canadian investment bank, from 2016 to June 2024, then CEO of Nuclear Fuels, a uranium explorer, until its sale in September 2025. Beyond Jessup, the five-person board includes chair Vern Baker, FNX’s former VP of Operations, and Jonathan Goodman, CEO of Dundee, which owns 16.0% of Magna. Greg Huffman will be Magna’s fourth CFO since early 2023, after co-founder Derrick Weyrauch, Ann-Marie Finney (who left in October 2024 after 17 months), and Scott Gilbert, who’s retiring by the end of 2026 after ~2 years. On mgmt's ability to execute, two of Magna’s timelines have slipped: 1) Crean Hill grid power: In November 2025, Jessup said Magna could have power at Crean Hill, its permitted nickel mine, in Q1 2026. In February 2026, he said power would come “hopefully by the end of Q2,” and in August 2026, he moved the target to Q4. 2) Free cash flow: In February 2026, Jessup said “we believe we’ll be generating free cash flow at these prices,” and Q1 2026 brought a US$14.2M free cash outflow, though US$11.0M of it was cash tied up in working capital, mostly money owed to Magna that came in after the quarter. Magna did deliver its other recent milestones, from the Levack resource estimate to the US$99M investment from Alpayana, a Peruvian mining group.
And the global half is already moving. $ELMT bought 4.99% of Masan High-Tech Materials for $124.75M on Oct 1, and expects the Vietnamese supplier to stay its key refiner even after Springer comes online. The ~$100M Refining & Trading bucket covers Australia and Spain on top of that. https://t.co/lTme3cYw9M
Crean Hill cost Magna Mining $MGMNF (TSX: $NICU) US$11.3M in November 2022, and a 2024 preliminary study put the mine’s after-tax NPV at US$137.0M. If R2, the high-grade zone Magna found at its Levack mine, is Magna’s copper and precious metals upside, Crean Hill is its biggest nickel exposure. Crean Hill’s 2024 PEA (preliminary economic assessment) outlined a 13-year, 2,200 tonnes/day underground mine that sells its ore to a third-party mill: → Resource: 18.4Mt indicated at 1.01% nickel, 0.87% copper, and 2.47g/t platinum, palladium, and gold. → Capital: US$34.2M for an advanced exploration phase (early underground work and bulk mining before full production) that earns US$11.6M of revenue, then US$19.6M before commercial production. → Economics: After-tax NPV (at an 8% discount rate) of US$137.0M and a 129% IRR, at $8.50/lb nickel, $4.00/lb copper, $900/oz platinum, $1,000/oz palladium, and $2,150/oz gold. Weighting each metal’s price change by its share of PEA revenue, I estimate Crean Hill’s revenue would be ~32% higher at Q2 2026 prices, even though nickel, 51% of PEA revenue, is the only metal below its PEA price. CEO Jason Jessup says the pre-feasibility study (PFS), due in the first half of October, will use “more realistic consensus metal prices for 2026” and update the capital costs. He expects the PFS to come in “generally in line” with the PEA, with “some additional costs.” Jessup also said in July that Crean Hill’s capital is “not going to be anywhere near $140 million.” Unlike McCreedy West, Magna’s producing mine, Crean Hill carries no precious metals stream. To fund the restarts, Magna now has ~US$124M of cash, most of it from Alpayana, a Peruvian mining group that bought 19.9% of the company in August.
Alpayana, a private Peruvian mining group, asked for 19.9% of Magna Mining $MGMNF (TSX: $NICU) when management was “thinking something probably below 9.9,” per CEO Jason Jessup. On August 28, 2026, Alpayana, chaired by Alejandro Gubbins, bought 62,356,682 shares at CAD$2.25/share for US$99M. The US$99M more than quadrupled Magna’s cash at the time. Alpayana runs six underground mines in Peru and Mexico, most of them bought from other miners, including the Los Quenuales mines from Glencore $GLNCY in December 2022 and Sierra Metals, a copper-zinc miner, for ~US$176M in 2025. While it holds at least 10%, Alpayana can join future equity raises and top up after dilution, and it gets one board nominee or an observer. Jessup says Magna’s pre-deal plan already funded Levack, its flagship restart project, from cash and the cash flow of McCreedy West, its producing mine. So the US$99M mainly spares Magna from “delaying the startup construction at Crean Hill,” its permitted nickel mine, “by 1 or 2 years,” and gives it “a bit of a war chest” for acquisitions in Sudbury, Ontario, where its mines are. He also says Magna “could have five mines in production in 5 years and not have to ever do another financing again.” Neither restart study is out yet (both are due in the first half of October), so the claim rests on capital budgets investors haven’t seen. After the deal, Alpayana holds 19.9%, institutions 47.4%, retail investors 26.9%, and management and directors 5.8%. The institutional stake includes the 16.0% held by Dundee Corporation $DDEJF, a Toronto investment company.
