

Three small caps from my watchlist (August 2026)
EverQuote, an $864 million digital insurance marketplace, and PAR Technology, an $808 million restaurant software provider, lead a…
Sector
Everything our editor has picked under this sector, best first.
94 stories
EverQuote, an $864 million digital insurance marketplace, and PAR Technology, an $808 million restaurant software provider, lead a…
Canadian Banks at 3x P/B again.. $RY ($FFH.to very close to 1x P/B when adjusted M2M) https://t.co/XwXAj84Mf0
If the $BHF deal goes through the SEC needs to investigate whoever bought 500 of the September 55's for $1.30 today
After Montgomery-Caribe and the impact on liability for brokers, and the general trend of dramatically higher insurance across the trucking space in recent years. How do people close to the freight market think about the truck rental companies like a U-Haul? If we are pushing liability on professional drivers, what is the case to give everyday drivers access to various side truck fleets and send them off to drive them on American highways? Clearly this practice seems unlikely to go away and U-Haul likely can pass escalating insurance costs on consumers better than the professional transport market but something to think about relative to margins and future demand in this space I think..... $UHAL
 CVS 2026-08-24
CVS Health’s insurance, PBM, pharmacy and clinical-care integration supports margin recovery as its valuation falls to 11.78 times earnings.
 Juxtaposed Ideas 3 clicks
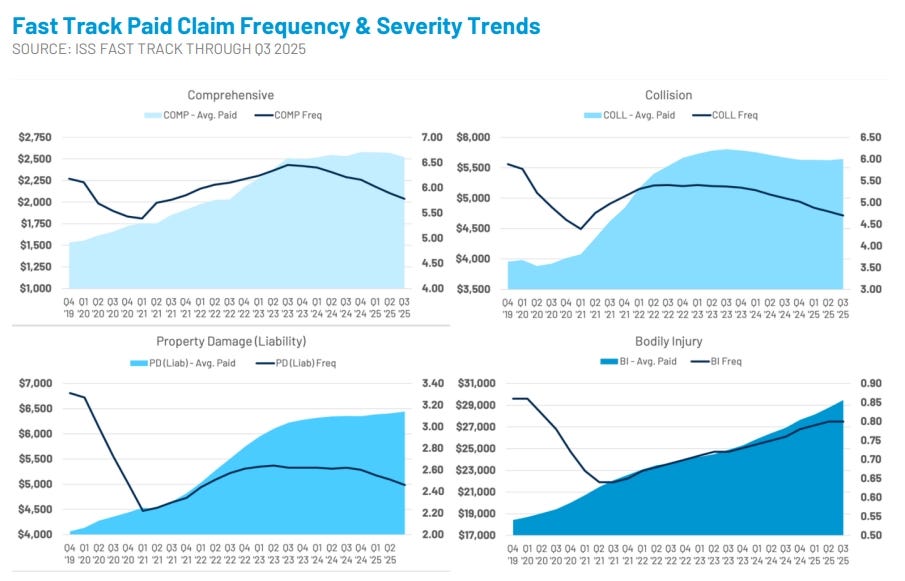
CCC, the dominant auto physical-damage claims estimator, connects 27 of the top 30 insurers with 31,000 repair shops as takeout rumors…
$KWY I have attached my notes on Kingsway. I think the company is at an inflection point based upon the excellent quarter they just announced. Very excited to see how the next few years play out for shareholders. I am optimistic. $10 per share should be an excellent entry point. https://t.co/j0rgEf3hUR
@MLedrappier @roadkillrecipes @CalgaryLeveen @FishOnCapital $NN No doubt the smartest people in the room think Sept and Oct are very live months. The SpaceX news is critically important great news. I may be wrong, but I love the company’s position right now.
ZhongAn Online trades at 0.57 times book after five profitable underwriting years, with a 95.8% combined ratio and ZA Bank’s first…
Honestly $C is pretty fairly valued now, I don't there is much upside at all aside from the entire sector carrying it up. $OPBK continues to be heavily disrespected, think we are entering the "on par with peers phase" where CUBI and OPBK and ASIC have a chance to trade in line with competitors. Implies 20-30% upside on each, but will take some time.
Aquarian won Brighthouse Financial despite a lower bid after higher offers failed to secure reinsurance for its legacy liabilities and thin…
Conference Chatter: NBT Bancorp $NBTB eyes bank M&A; Community Financial seeks insurance opportunities | S&P Global Market Intelligence https://t.co/L1NY5yUkBc
 GHTI · long
International General Insurance, IGIC, trades at 8.9x LTM earnings and 1.5x tangible book value, with a $1.1 billion market capitalization…
@ramahluwalia $GSHD ~double off the early June lows was easy money!
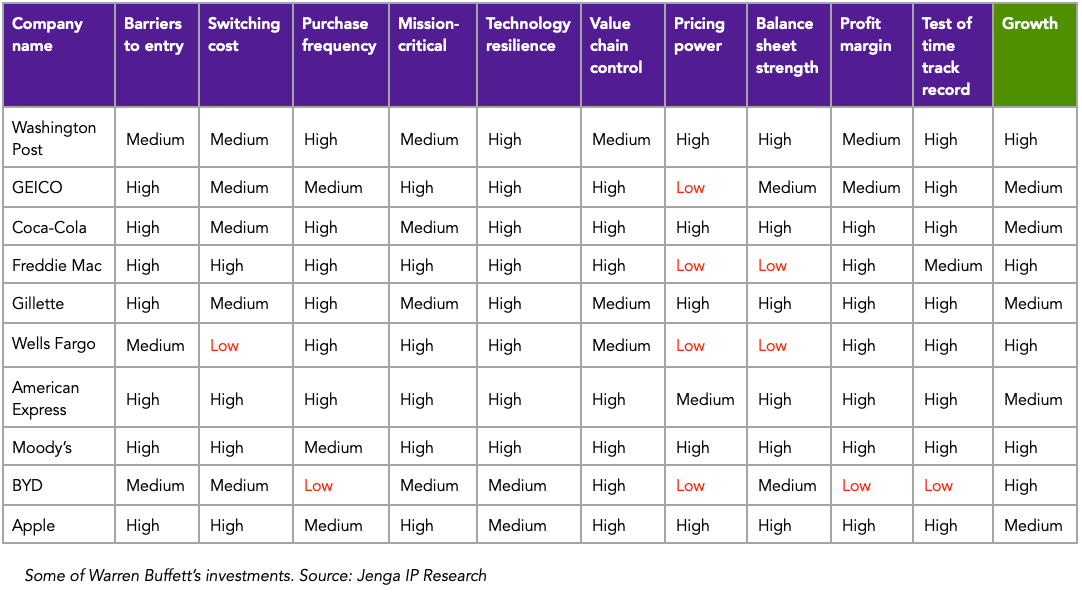
A 10-factor quality table ranks companies by moats, pricing power, balance sheets and growth, then applies it to 10 Buffett investments.
Molina Health is revisited.
$CB with some pretty chilling, but not entirely commentary on pricing on commercial property lines as the market continues to soften: Pricing on new biz or renewals (-12%) Pricing on the biz they chose not to renew or rejected (-40%) YOY! Otherwise, $CB was brutally honest about the softening across the marketplace in casualty lines and E&S in general. With MGA's flooding the market, this isn't a dynamic that changes overnight. Probably not a great market environment for our friends at $KNSL. Do bulls understand what they own?
Exceptional idiosyncratic short opportunities emerging from the on/off semi trade that is largely indiscriminately moving the markets and sectors each day. (been long opportunities that emerged too) Private credit exposed names have ripped off financial sector rotation and likely some short squeeze in heavily exposed names - names like $FG $MET $MFC (continue to tout these until their exposure is recognized by the market) Software - each name needs to be looked at on its own accord, the broad software is dead or alive from ai does not work. Big rally across the board has left more disrupted names like $PCTY and $PAYC up for the year now. Plenty of others that look good to build sort positions against (especially if you have long software/dats service provider exposure) Dispersion past quarter should set up some very interesting opportunities that should have to stand on their own fundamentals when earnings come
Good to see someone paying attention on life insurers from Bloomberg today. Private Credit and certain life insurers are deeply linked - $MET, Lincoln are just the tip of the sphere I would add https://t.co/Vcyt0RFlT1 and certain regional banks like $WAL in that mix too. *and sure 95% of all your pc loans are credit grade MetLife, can I ask how many were rated by Egan Jones?*
Little perplexed you get more negative redemption stories around private credit, and the market only sells off the the the pure play PE companies. First derivatives are up? $MFC $FG $MET $WAL all have sizable exposure to the same asset class.....
If it gets to mid to low 20s copart $Cprt seems like a good bet. Insurance mkt will harden and yes they have competition but duopolistic markets are still attractive and at 3-3.5x sales I think you’re good
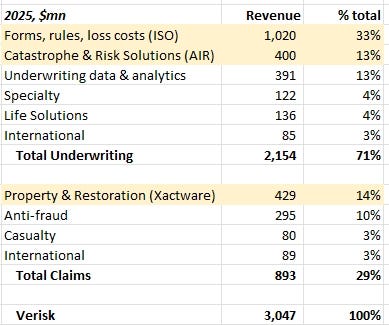
Verisk’s exit from healthcare, financial-services and energy data restored a pure-play insurance analytics model, but D.E.
Brown & Brown compounded revenue 14.4% annually since 1998 through more than 650 acquisitions, capped by its nearly $10 billion Accession…
$TIPT director buys ~1k shares at 17.45 on Wednesday and Fortegra deal should close today https://t.co/HYVSdjXcO9
