
Philip Morris International: Juggernaut
Philip Morris grew Q2 cigarette volumes 1.1%, revenue 9.8% and gross profit 11.5%, while IQOS retained Japan leadership despite…
Sector
Everything our editor has picked under this sector, best first.
243 stories
Philip Morris grew Q2 cigarette volumes 1.1%, revenue 9.8% and gross profit 11.5%, while IQOS retained Japan leadership despite…
@TidefallCapital I think macro beer is still deeply challenged, though I own a little bit of $TAP and $ABEV. I'm much more confident spirits will recover.
Philip Morris reported strong Q2 2026 trading, while U.S. ZYN growth barely increased. Shares rose 3.3% to a record high.
Let's congratulate the market and the investment community for a moment on filling the gap from $WDFC on that nonsensical earnings beat. I read the transcript twice and the magnitude of upside in the quarter still didn't make sense. For this kind of business it should have been a simple explanation from management. Instead it was innuendo and evasion.
Yeah, $CPB bulls trying to hold the line on the 2002 and 1995 lows. They have some solid brands for sure, but the management is moronic, the board even worse, they have no clue on capital management, and the balance sheet is a disaster. Everything but the last point is an argument for this business to be sold. However, that leverage.... I guess someone can come in and eliminate the dividend which frees up $450MM in FCF. From there you can probably delever this biz 2-3 turns in a few years. Tough sledding, but there's a lot of wasted advertising across this company, that's for sure.
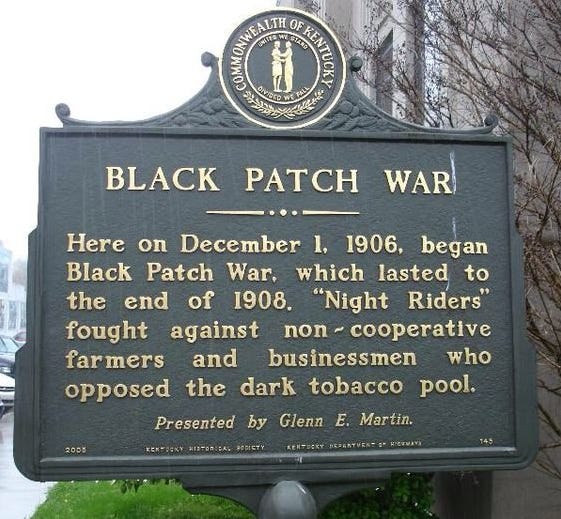
The Black Patch Tobacco Wars show how American Tobacco’s buying power drove Kentucky and Tennessee farmers to organize against below-cost…
$ALTO 🤷♂️ https://t.co/67lkE1qWvP https://t.co/JDe6p8IL4U
New 52 week high for $GPRE...
Molson Coors trades at 6.2x free cash flow and offers a roughly 15% shareholder yield, but declining beer volumes could make it a value…
@calleymeans @SecKennedy Seems like a tailwind for Lifeway $LWAY
$WDFC results are staggering when you read through them....then you get to the guidance and it does not reflect the monstrous quarter they just posted (relatively the same as the guide from Q1)....something is off with this company, they are either one of the worst non micro cap companies at forecasting their business (not a great endorsement of management and their processes). AND/OR they are playing games with inventory to influence the stock. I will reserve my own comments for private, but if you look back in recent years there are some odd swings in Asian /Chinese inventories in given quarters. Fascinated how a product that has been around forever with wide distribution posts a +30% print in Americas, 24% company wide. And the guide moves from 5-9% to 6-9% growth for the year?? What is going on?
Newest out. Pouches Poised for Prime Position $HAYPP $PM $BTI $MO $IMBBY https://t.co/GF4qYTJYXL
Molson Coors, a 7% portfolio position, is the world’s fourth-largest brewer with leading beer shares in Canada and the US through Coors and…
Newest out. The Nicotine Window $PM $BTI $MO $IMBBY $HAYPP $STG https://t.co/dsPhltOzUN
Wingstop generates most of its $697 million revenue from franchise royalties across a 3,153-restaurant, 98%-franchised system while…
Campbell's trades at 10-11x earnings and a 7% yield after shares fell over 50%, while 4x leverage, weaker volumes and margin pressure…
Newest out. Maker of Men "Buck Duke, American Tobacco, and an enduring legacy." $BTI $IMBBY $LOG $PM $MO $STG $HAYPP https://t.co/BwZC6I9Fth
James B. Duke built American Tobacco into a monopoly, then extended his legacy through Duke Power and the Duke Endowment.
Really interesting how $GO had truly massive insider buying and the stock barely reacted, allowing the investor to accumulate a sizable position. This one has worked quite nicely. https://t.co/iXfU4SCmt5
$UTGN looked promising as an illiquid deep value sit with buybacks at way below IV, but this relatively recent option grant struck below NAV seems like a thesis killer. Anybody know the name well?
Newest out. British American Tobacco: Affirmed $BTI $IMBBY $LOG $PM $MO $STG $HAYPP https://t.co/9BnZjicaDN
British American Tobacco targets more than GBP 50 billion of free cash flow by 2030 as Velo oral nicotine gains offset uneven vapor and…
??? Two things can be true at the same time. In that you can have a slow down from weak international travel (administration) domestically, weak lower end consumer, glp, and inflation that is dragging down sales. And yet you can continue to invest in new store counts if the economics of your model are intact AND you have the balance sheet to continue to invest in your business. The competitors you cited besides macro have other issues impacting their ability to invest; PTLO has a serious balance sheet issue SG has an economic model problem... *turns out 18$ salads is a tough business*. Mcdonalds increased store openings in 2008 AND 2009 even as SSS growth was slowing every year 06-09....those investments worked out just fine because the model works. $SHAK SSS still going to print solidly positive for the year while most chains won't this year (and thats without the added store count). Shak has issues, all restaurants are tough and tough to scale and Rob and the cfo are far from Mcdonalds level of execution, but at 1x sales and a +20% restaurant margin model with 4m AUV theres a lot more room to the upside then the downside at current levels. I don't think they get to the dream target of 1500 stores, but that would be a 10x from here, whats the downside, at almost 1x current....30% maybe? I'll take that asymmetric set up. (Entered shares today)
$BGS LOLZ! Just priced $475M sr notes at 11.625% to refinance 5.25% 2027 sr notes. Way worse than I expected. Circling the drain! Mark it zero! https://t.co/lwXYgOO069
