
Barbarian Capital on X
Accenture looks to sell Chinese operations for up to $1.5 bn $ACN https://t.co/0LrYwpiFkl
Search
Every story we have published, filed by the company it is actually about.
4884 stories about companies over $300M
Accenture looks to sell Chinese operations for up to $1.5 bn $ACN https://t.co/0LrYwpiFkl
Evercore appoints co-presidents for the first time in leadership reshuffle $EVR https://t.co/XTqr3gW9jX
Fair points, but I think you’re conflating capital markets access with the economics of the underlying contracts. A pulled equity offering doesn’t mean secured project financing has disappeared. And more importantly, $CRWV and $CIFR have fundamentally different business models, funding requirements and residual asset values. That’s precisely my point.
Excellent illustration of $CRWV capital structure https://t.co/fEZpy9xXbe https://t.co/9kK2aZS3Up
𝙒𝙝𝙖𝙩 𝙝𝙖𝙥𝙥𝙚𝙣𝙚𝙙 𝙩𝙤 𝙩𝙝𝙚 𝙉𝙚𝙤𝙘𝙡𝙤𝙪𝙙 / 𝘼𝙄/𝙃𝙋𝘾 𝙩𝙧𝙖𝙙𝙚 𝙡𝙖𝙨𝙩 𝙬𝙚𝙚𝙠: I like distilling complex topics down to plain English. Here’s my understanding of what happened. Please correct where wrong… $CRWV and its peers rent $NVDA GPUs to AI labs and hyperscalers under multi-year take-or-pay contracts. The capex is so large relative to cash flow that the model only works if they can keep raising tens of billions a year in new financing to build what customers have already signed for. Much of that comes from secured loans backed by specific chips and contracts, while the rest comes from unsecured bonds, converts or stock. Importantly, not all secured debt is non-recourse, and many of $CRWV’s GPU loans are guaranteed by the parent. Still, the secured facilities held up considerably better than the unsecured bonds, which went from ~12% to ~15% yields, while the cost of insuring them via CDS roughly doubled… Nothing fundamental appears to have caused it. No major customer walked, GPU pricing held up, and the quarter looks fine. What happened was a cluster of headlines landing on a nervous market with the 10-year near 5.2% and hundreds of billions of AI debt issuance expected: Chamath calling it a private-credit bubble, an analyst saying the equity could go to zero, Gartner forecasting that over 80% of neoclouds stop operating independently by 2030, a few smaller peers failing to get IPOs and debt deals done. Underneath sat the bigger question of whether neoclouds are durable businesses or really just financing wrappers that hyperscalers eventually insource and cheap open-source models undercut. Once investors doubt the parent can fund growth, the stock falls, which makes the equity leg more dilutive, which worries bondholders more. Credit and equity fed on each other and the whole group fell 10-30% in sympathy. Was it justified? In three parts. (1) The $CRWV unsecured bond move was likely overdone: a company with ~$17bn of liquidity and a $129bn contracted backlog doesn’t suddenly become a distressed credit because of a handful of headlines. But backlog isn’t cash flow, and secured lenders have first claim on specific assets and cash flows, with many loans also carrying parent guarantees. The question for unsecured creditors is how much cash actually makes it back to the parent after servicing the secured debt. Still, a move to ~15% yields looks more like aggressive HF de-risking with headlines as the accelerant than a sudden collapse in the underlying business. (2) The $CRWV equity move was more understandable, just not for the headline reasons: this is a levered financing business whose equity returns depend on the cost of the marginal dollar of capital. When financing gets more expensive, the residual value on every future GW shrinks, and any gap that needs to be filled with equity becomes more dilutive. That said, unsecured bonds trading at 15% doesn’t mean every new GPU deployment costs 15% to finance. A 20% haircut for a stock that may not self-fund until 2030 could be seen as fair, but it ultimately depends on how much parent-level capital is actually required. (3) The group ($CORZ, $CIFR, $WULF) selloff was the least justified: $CRWV finances depreciating GPUs and bears the risk of obsolescence and replacement. The miners converting to HPC are increasingly financing long-lived power and data center infrastructure leased to hyperscalers under 15-20 year contracts, often with the customer owning the GPUs. Their risks are construction, power delivery and financing, not GPU replacement or compute pricing. Different assets, different contracts, different capital structures. Yet the market sold them as though they had the same problem, and that’s where the mispricing most likely sits…
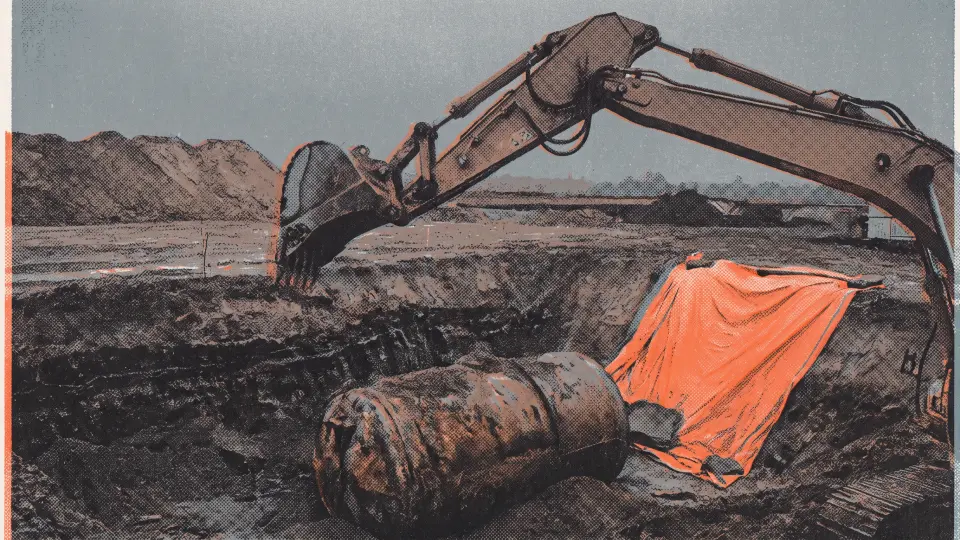
Digital Realty paid $120 million for Atlanta-area parcels including a former Army dump with buried carcinogens and military ordnance.
HY bonds losers from last week. Some familiar faces. $FMC $JBLU $UNIT $FUN $CRWV https://t.co/MvkKq0lssG
$FMC bonds down 70 points in the last year. Jeez. Generics took pricing, distributors sitting on expensive inventory, and FMC now taking a $625-675mm hit to clear it Bonds down 38pts last week alone... https://t.co/CL6xOPeSfD
Crews at a data center construction site in Georgia unearthed incendiary white phosphorus late last year. Police sent in a bomb squad. The site: a former Army dump near Atlanta, where Digital Realty ($DLR) is building a $3 billion data center campus. https://t.co/BSLbwjk7cE
Feels like shorting Taiwanese AI stocks is probably a good hedge right now. Positioning remains extremely elevated = highly exposed to short-term downside. Just look at how the market responded to $TSM's awesome earnings/guidance....-2.5%.
I’ve spent a few days thinking about the Tesla Roadster reveal and landed somewhere I haven’t seen much discussion. I’m neither a Tesla fanboy nor a Tesla hater. And I couldn’t care less whether what we saw technically qualifies as a flying car. Three takeaways: (1) The risk of that live demonstration going horribly wrong was real. Almost no CEO would willingly expose their company to that kind of public humiliation for a product with so little financial upside. Elon did. (2) That willingness to attempt the seemingly impossible is what makes Tesla special. It’s also arguably Elon’s greatest contribution to America. He’s helped bring back something we’ve lost. The American spirit of chasing big scary ideas that most people think are impossible. That mindset is spreading across a new generation of founders and its long term impact on America’s future could dwarf anything Tesla ever sells. I think this is deeply underappreciated. (3) Can we just acknowledge how insanely cool that moment was? We’ve reached a strange place culturally where even extraordinary feats of human ingenuity immediately become arguments about why they don’t count. Not everything needs to be a debate. Sometimes we should just be able to stand back together and marvel at what humans are capable of. I’ve been both bullish and critical of Tesla’s ambitions over the years. But watching Elon and his team push the boundaries of what’s possible reminds me why I’m glad we have him. Whether the Roadster ever makes Tesla a dollar or impacts $TSLA stock price is almost beside the point. We need more people willing to risk failure in pursuit of things the rest of us think are impossible. Because when they succeed we all win.
Wells Fargo’s Q3 EPS beat and $12.5 billion net interest income failed to move shares, while WFC.PZ preferreds yield 7.10%.
 Jeremy LaKosh
Cerebras, a wafer-scale AI chipmaker, is forecast to nearly 10x sales by 2028 as capacity expands, while its shares have fallen on capacity…
 Stone Fox Capital 1 click
@DivinelyLevered @ACapitalLP @YetAnotherValue Well.. they have a $100 mm buyback in place. The float ex Roark is 66 mm and at these prices you can buy almost 15 pct. When you back out our stake and a few other chunky holders they could do some damage if they actually want to drain the swamp. $drvn
Oruka Therapeutics’ ORKA-001 posted PASI 90 and PASI 100 psoriasis responses at week 28; $1.1 billion of cash funds development through a…
 Equity Eagle
First Financial’s merger with First Illinois Financial is expected to lift net interest income and ROE from 2027 after Q2 net income rose…
 Sorrento Research
 Dividend Power
 FINV · long
FinVolution, a China and ASEAN unsecured consumer lender, trades at 4x earnings and 0.5x book value.
 MG · long
Mistras Group is a rare publicly traded US non-destructive testing pure play, providing quality assurance for materials, components and…
DexCom’s 15-day G7 sensor lifted Q2 2026 gross margin 400 basis points to 64.1%, lowering CGM costs ahead of broader Type 2 diabetes…
Equity Eagle 4 clicks
Semtech raised Q3 guidance and targets $3.2 billion of fiscal 2030 revenue, excluding upside from its AI data-center optical and copper…
DigitalOcean’s CEO says the cloud company will not take on extraordinary leverage to fund its AI push.
Optical-component vendor call covers 800G and 1.6T demand, AI cluster optical density, market share, pricing and 2027 growth for Coherent,…
$CRWV has ~$10bn of unsecured HY notes, all yielding 14-15%. There’s also another ~$11bn of converts. That’s ~$21bn of unsecured claims, sitting behind the secured debt that funds the GPUs. Here's the latest market pricing on the HY notes (converts excluded): https://t.co/vVxKgKVCRc
