
Speedrun | Upcoming Events This Week - [September 28 - October 2, 2026]
Micron’s DRAM margin commentary, Core PCE and payrolls headline a week also shaped by Iran ceasefire talks over the Strait of Hormuz.
Sunday, September 27
Everything we published on this day.
30 stories — the front page that day →
Micron’s DRAM margin commentary, Core PCE and payrolls headline a week also shaped by Iran ceasefire talks over the Strait of Hormuz.
Here's a cheap but (kinda) funny jab... if my thesis above is correct, and if $ABVX was acquired in August/(early Sept)... it would have saved the whole biotech market...🤷♂️
@mopar_momma @robert34846 I thought @CEOAdam had stuck the $AMC stock up the Apes arse... but whatever...
A contrarian pick, for AI-like return in real estate. $STWD (Starwood Property Trust) has an asymmetric setup for a possible ~50% total return over the next 12 months If Treasury yields peaks and then declines back within the next year, then a combination of the current 13.3% div yield + rerating back to above its undepreciated book value ($19/share) results in close to 50% return for this best of breed lender. True Multi-Cylinder Engine: Unlike pure-play lenders exposed to a single-sector, $STWD operates across commercial lending, infrastructure, and owned real estate. Built-in Counter-Cyclical Hedge: Its Special Servicing and Investing arm actually benefits when market volatility rises, collecting servicing fees that insulate cash flows when traditional credit tightens. Office Risk Is Overblown: U.S. office makes up less than 8% of its total asset base, with the balance anchored in residential, industrial, and essential infrastructure. Unmatched Dividend Track Record: Management has maintained its quarterly dividend for over 17 yrs without a single cut through multiple rate cycles. Collecting a 13.3% cash yield while waiting for a yield-driven rerating could deliver an equity-like upside with institutional downside protection.
A contrarian pick, for AI-like return in real estate. $STWD (Starwood Property Trust) has an asymmetric setup for a possible ~50% total return over the next 12 months If Treasury yields peaks and then declines back with the next year, then a combination of its current 13.3% div yield + rerating back to above its undepreciated book value ($19/share) results in close to 50% return for this best of breed lender. True Multi-Cylinder Engine: Unlike pure-play lenders exposed to a single-sector, $STWD operates across commercial lending, infrastructure, and owned real estate. Built-in Counter-Cyclical Hedge: Its Special Servicing and Investing arm actually benefits when market volatility rises, collecting servicing fees that insulate cash flows when traditional credit tightens. Office Risk Is Overblown: U.S. office makes up less than 8% of its total asset base, with the balance anchored in residential, industrial, and essential infrastructure. Unmatched Dividend Track Record: Management has maintained its quarterly dividend for over 17 yrs without a single cut through multiple rate cycles. Collecting a 13.3% cash yield while waiting for a yield-driven rerating could deliver an equity-like upside with institutional downside protection.
I have been bullish on China’s WFE localization after reading Chip War in 2023 on my couch $ACMR
NAIC oversight missed Delaware Life’s $13.34 billion affiliated-bond exposure and permits capital treatment that props up Brighthouse’s…
7/n the CEO of $SHEL on the @TRowePrice podcast Interesting at several levels: global energy mix/growth, geopolitics, asset diversification, management skills, AI applications
$GEN making a run at buying $GDDY Shares of GEN selling off ~30% from $31 to $22 Likely in part from this takeover news and perhaps the influx of Muse-driven subscription cancellations? I own shares of GEN
Some of the more interesting opportunities in credit are the Bitcoin miners (now AI datacenter developers) that issued converts before signing a major lease. $KEEL is one of them. The stock ran up in June, then collapsed, and has barely recovered since. The converts are in the 80s/low-90s. Not distressed or even yield equivalents but something I'm keeping my eye on. Traded as low as 60 earlier this year.
@ChrisAngelini11 @AFMBlog @GameStopKing @trvsrdrgz2 probably, but I have not held $AMC down 99 percent.
Another issue with $ROL is that now that it is becoming easier to set up a business and website and market on the web, if i was a pest technician I'd think about how to go solo so that I don't need to give up all my margin to someone else just because they are setting up all the lead gen infrastructure. Not surprised to see pretty bad non-compete terms with $ROL imposes on their technicians. Already seems to be another advantage that is facing pressure.
This is why X is awesome! Check out this writeup on $BMBL that outlines the worst case scenario well and how the stock could still work. “I like to look down before looking up when I invest” -Joel Greenblatt
It was not looking good even in 2024 there was a lot of evidence for structural pressure on web traffic viewership and thus the value of led gen website providers, which primarily provided content and information. Never expected $ROL, a provider of pest control to become an AI loser But with Muse being able to negotiate prices and price transparency issues now becoming much more efficient a lot of business models could shrink pretty significantly that relied on lazy consumers. I remember in NYC i was once had to call pest control and negotiated with maybe 5 providers, the prices were absurd and it was such a waste of time. Deploying a muse agent to do this dirty work would have been so helpful
Circumstances for Burry to buy $GME is exiting the eBay deal which I think happens.
U.S. Treasury yields climbed above 5% as markets priced further Fed tightening, while Meta’s AI-agent announcement lifted risk appetite…
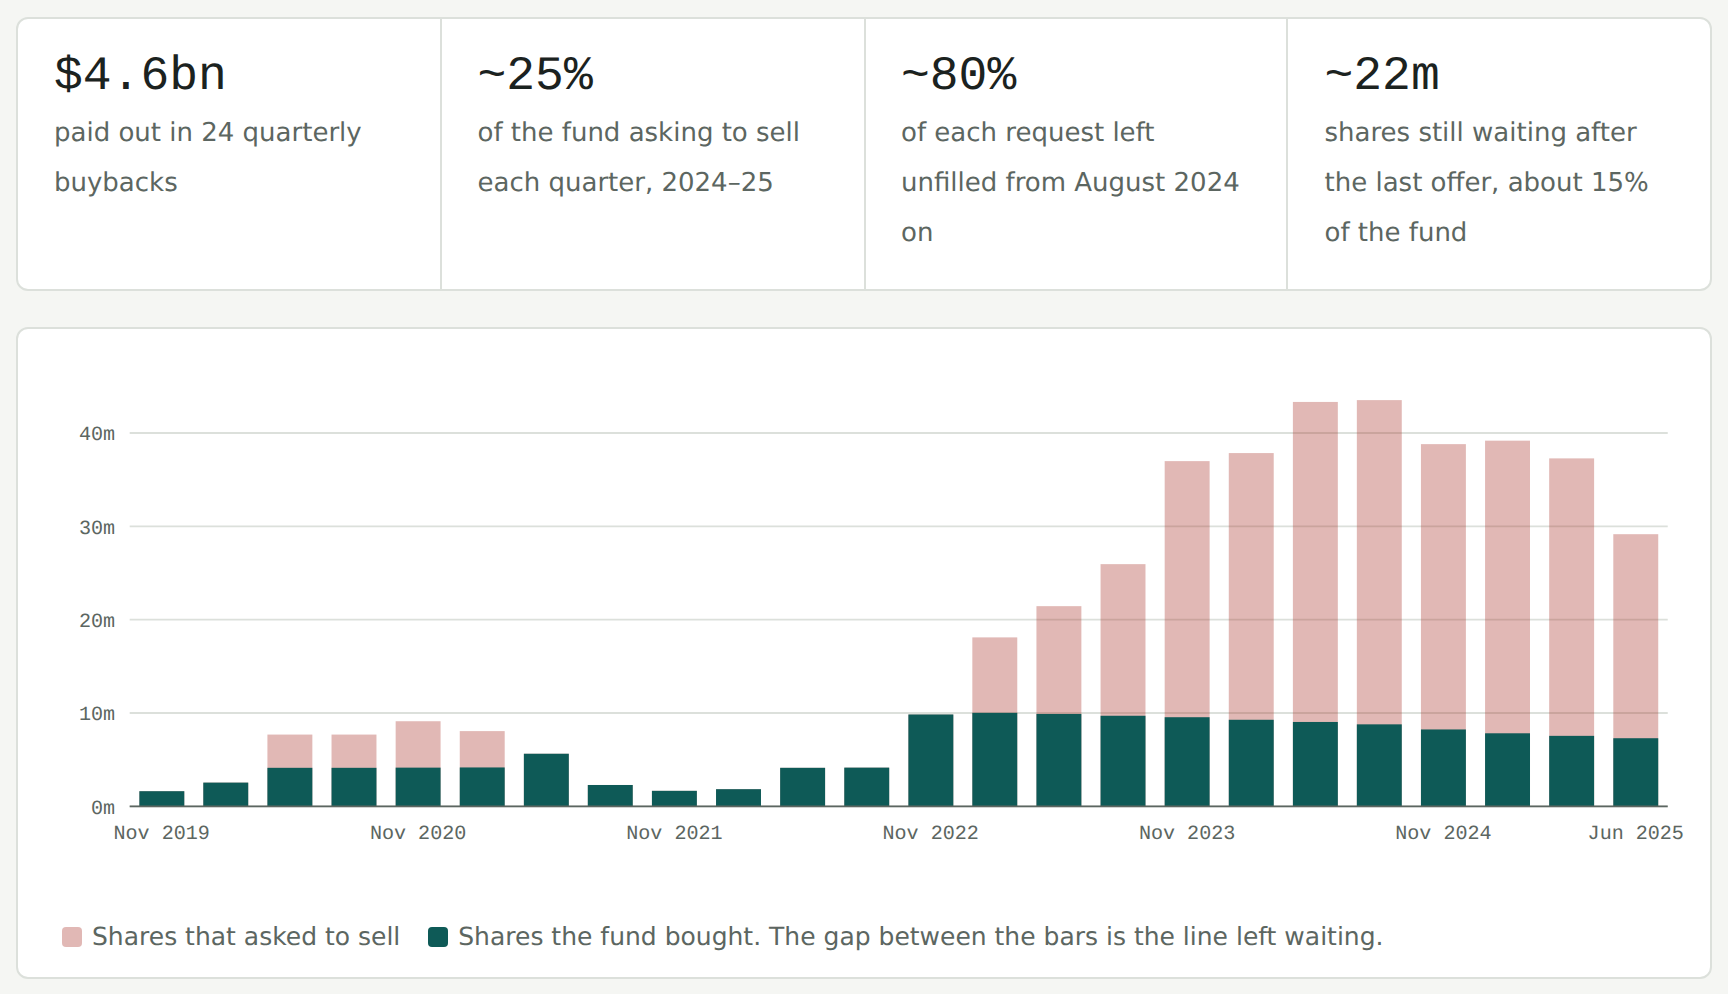
BPRE trades 45% below NAV as Saba and Bulldog press for buybacks or a manager change, challenging Bluerock’s incentive to preserve…
@TexDoggie I lived in Queretaro for years, loved weekend trips to Guanajuato. Very cool city with all the mines and tunnels and punches way above its weight with stuff to do thanks to the university. That airport has been one of the fastest growing ones for $PAC, love Bajio region.
Greenland Energy Company holds 2.1 million acres in the Jameson Land Basin, but drilling permits, political risk and warrant dilution cloud…
 Ron Ferrie
Hindsight Capital tests crisis-era investment decisions using anonymized company financials, including TransDigm, Halma and Texas Pacific…
yes I am a miserable fuck. There are several things I like. I like that hedge funds bought $AMC debt at pennies on the dollar. I like that Apes kept buying $AMC as the stock count 20x - and the money went to hedge funds. I like that Apes have thus lost a lot of money to make hedge fund managers richer. And I will especially enjoy it when $AMC eventually fails. Now you know what makes me happy.
Neighborhood Intelligence, NXH, faces a cash shortfall after failed and restructured acquisitions, as losses and limited financing options…
 Vince Martin 1 click
Sezzle’s Q2 2026 revenue rose 51.7% and adjusted net income 58.4%, while revenue per GMV reached 11.7% as Premium subscriptions lifted…
 Blake Winiecki 1 click
Brookfield’s BN, BAM, BIP, BEP and BBUC span asset management, infrastructure, renewables and private equity, with BN valued at a 15–20%…
 Brad Thomas
Warrior Met Coal’s Blue Creek ramp lifted Q2 sales to 3.7 million tons and cut unit costs to $92.53 per ton, shifting earnings growth…
 Capital Connoisseur 1 click
Encore Capital Group’s shift to higher-yielding U.S. debt portfolios lifted cash efficiency margin to 60.2% and ROIC to 13.7%, despite…
 Growth Stock Hunter 1 click
Mastercard’s VASS segment reached roughly 40% of net revenue and grew 20%, while AI, digital-wallet and stablecoin partnerships expand its…
 IWA Research
Annexon targets functional recovery in geographic atrophy and Guillain-Barré syndrome, with ARCHER II vision-endpoint data due in Q4 2026…
 Equity Eagle 3 clicks
Legacy Education's Q4 revenue growth slowed to 12% as student starts fell, while Texas expansion and margin gains underpin its next growth…
 Fernanda Galvez Jalil 2 clicks
Lime guided Q3 revenue of $340–$360 million and adjusted EBITDA of $120–$130 million, targeting positive full-year free cash flow despite…
 The Market Auditor 1 click
