Berkshire Hathaway completes its succession plan: Warren Buffett becomes Chairman Emeritus, Howard Buffett takes the chair, and Greg Abel…
S The Rational Walk
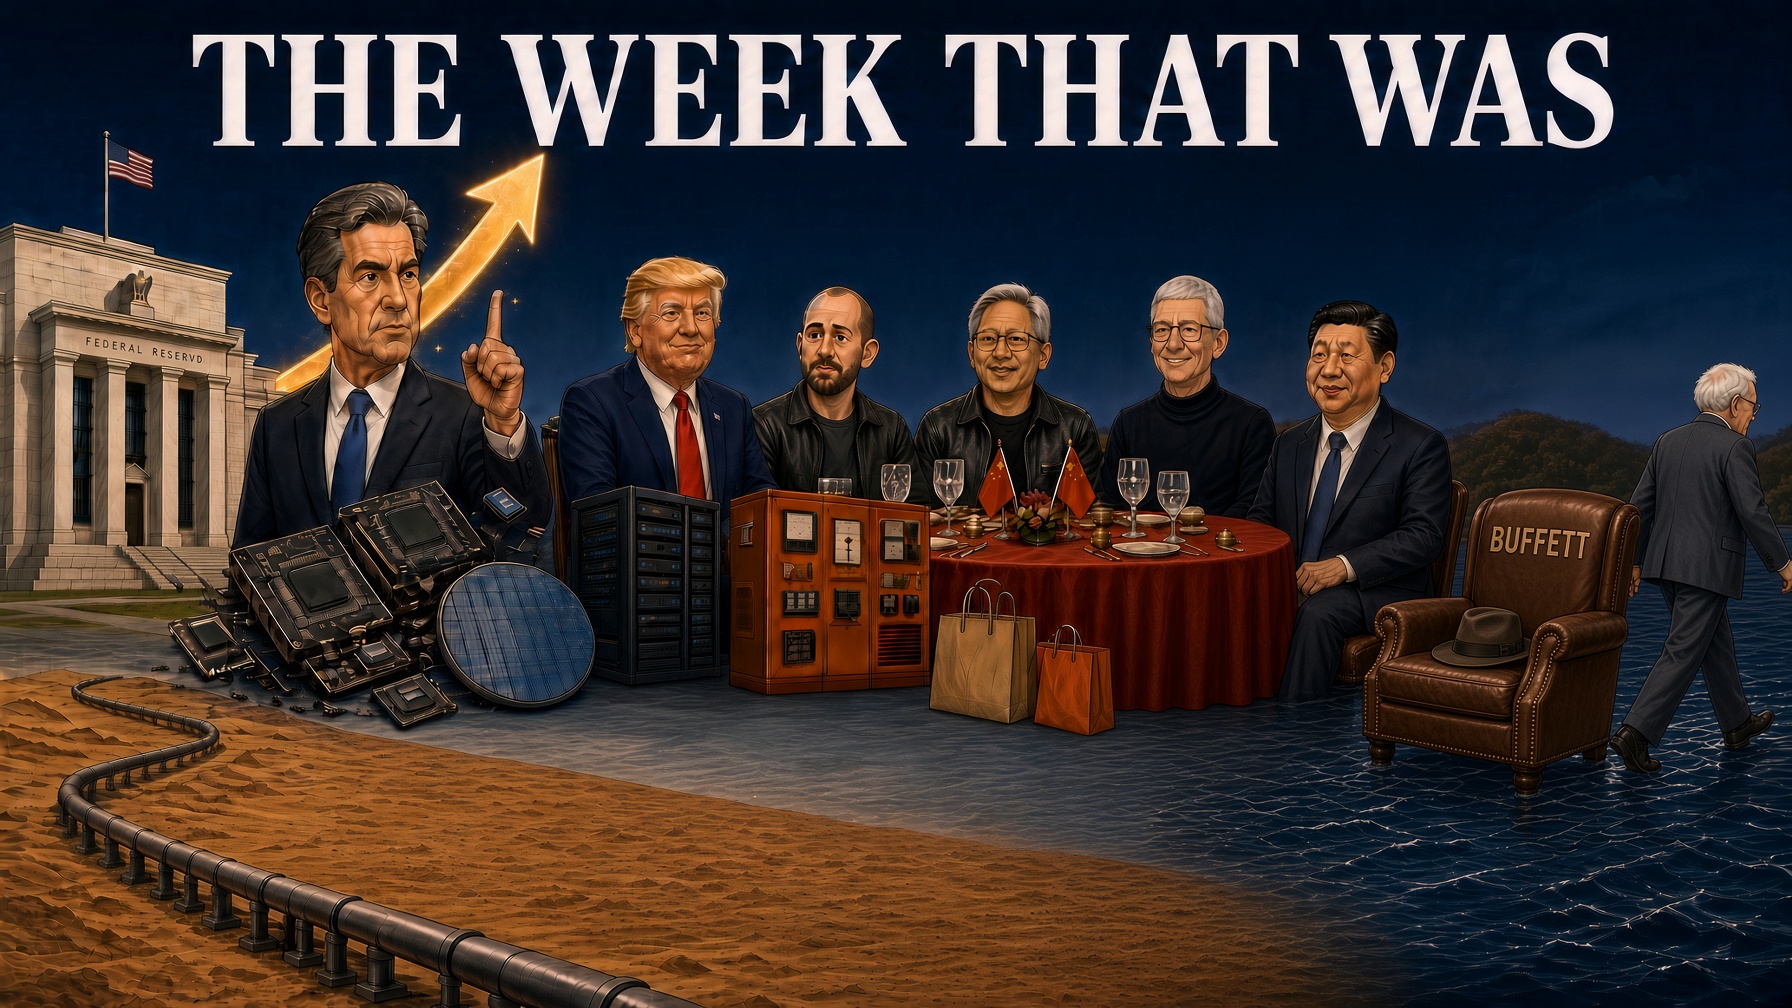
Federal Reserve’s quarter-point hike failed to contain 10-year yields above 5%, while rising legacy-chip rentals and AI safety compute…
Evolus posted 21% quarterly revenue growth as U.S. facial-injectable spending bottoms, while making progress toward GAAP profitability.
S Emerging Moats Research 1 click
Ultra Clean Holdings targets a $4 billion annualized revenue run rate by H2 2027 through manufacturing expansion and a broader…
S Monte Independent Investment Research 2 clicks

Steve Eisman argues AI extinction warnings from Dario Amodei and Sam Altman seek regulation that creates pricing moats.
YT Steve Eisman 2 clicks

DoorDash's grocery push targets a shift from weekly stock-up trips to frequent online fill-in orders, though smaller baskets complicate…
S MBI Deep Dives 1 click
Planet Labs’ $116.1 million second-quarter revenue, 70% defense mix and planned Owl constellation position satellite imagery and AI data as…
SA  Petri Dish Reports 2 clicks
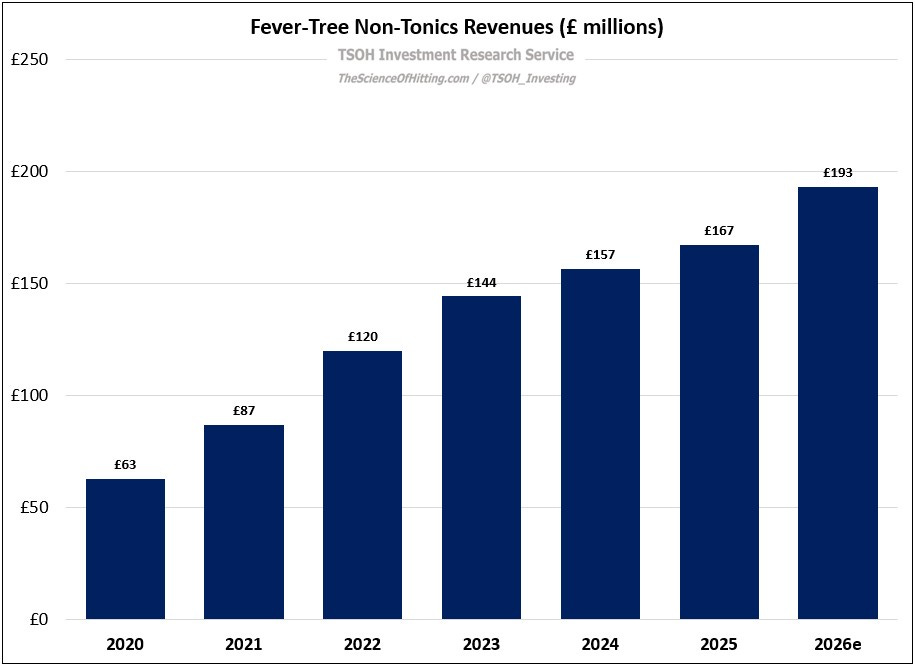
TSOH Weekly Roundup covers organized retail crime, Home Depot’s centralized operating missteps under Bob Nardelli, and research updates on…
S TSOH Investment Research
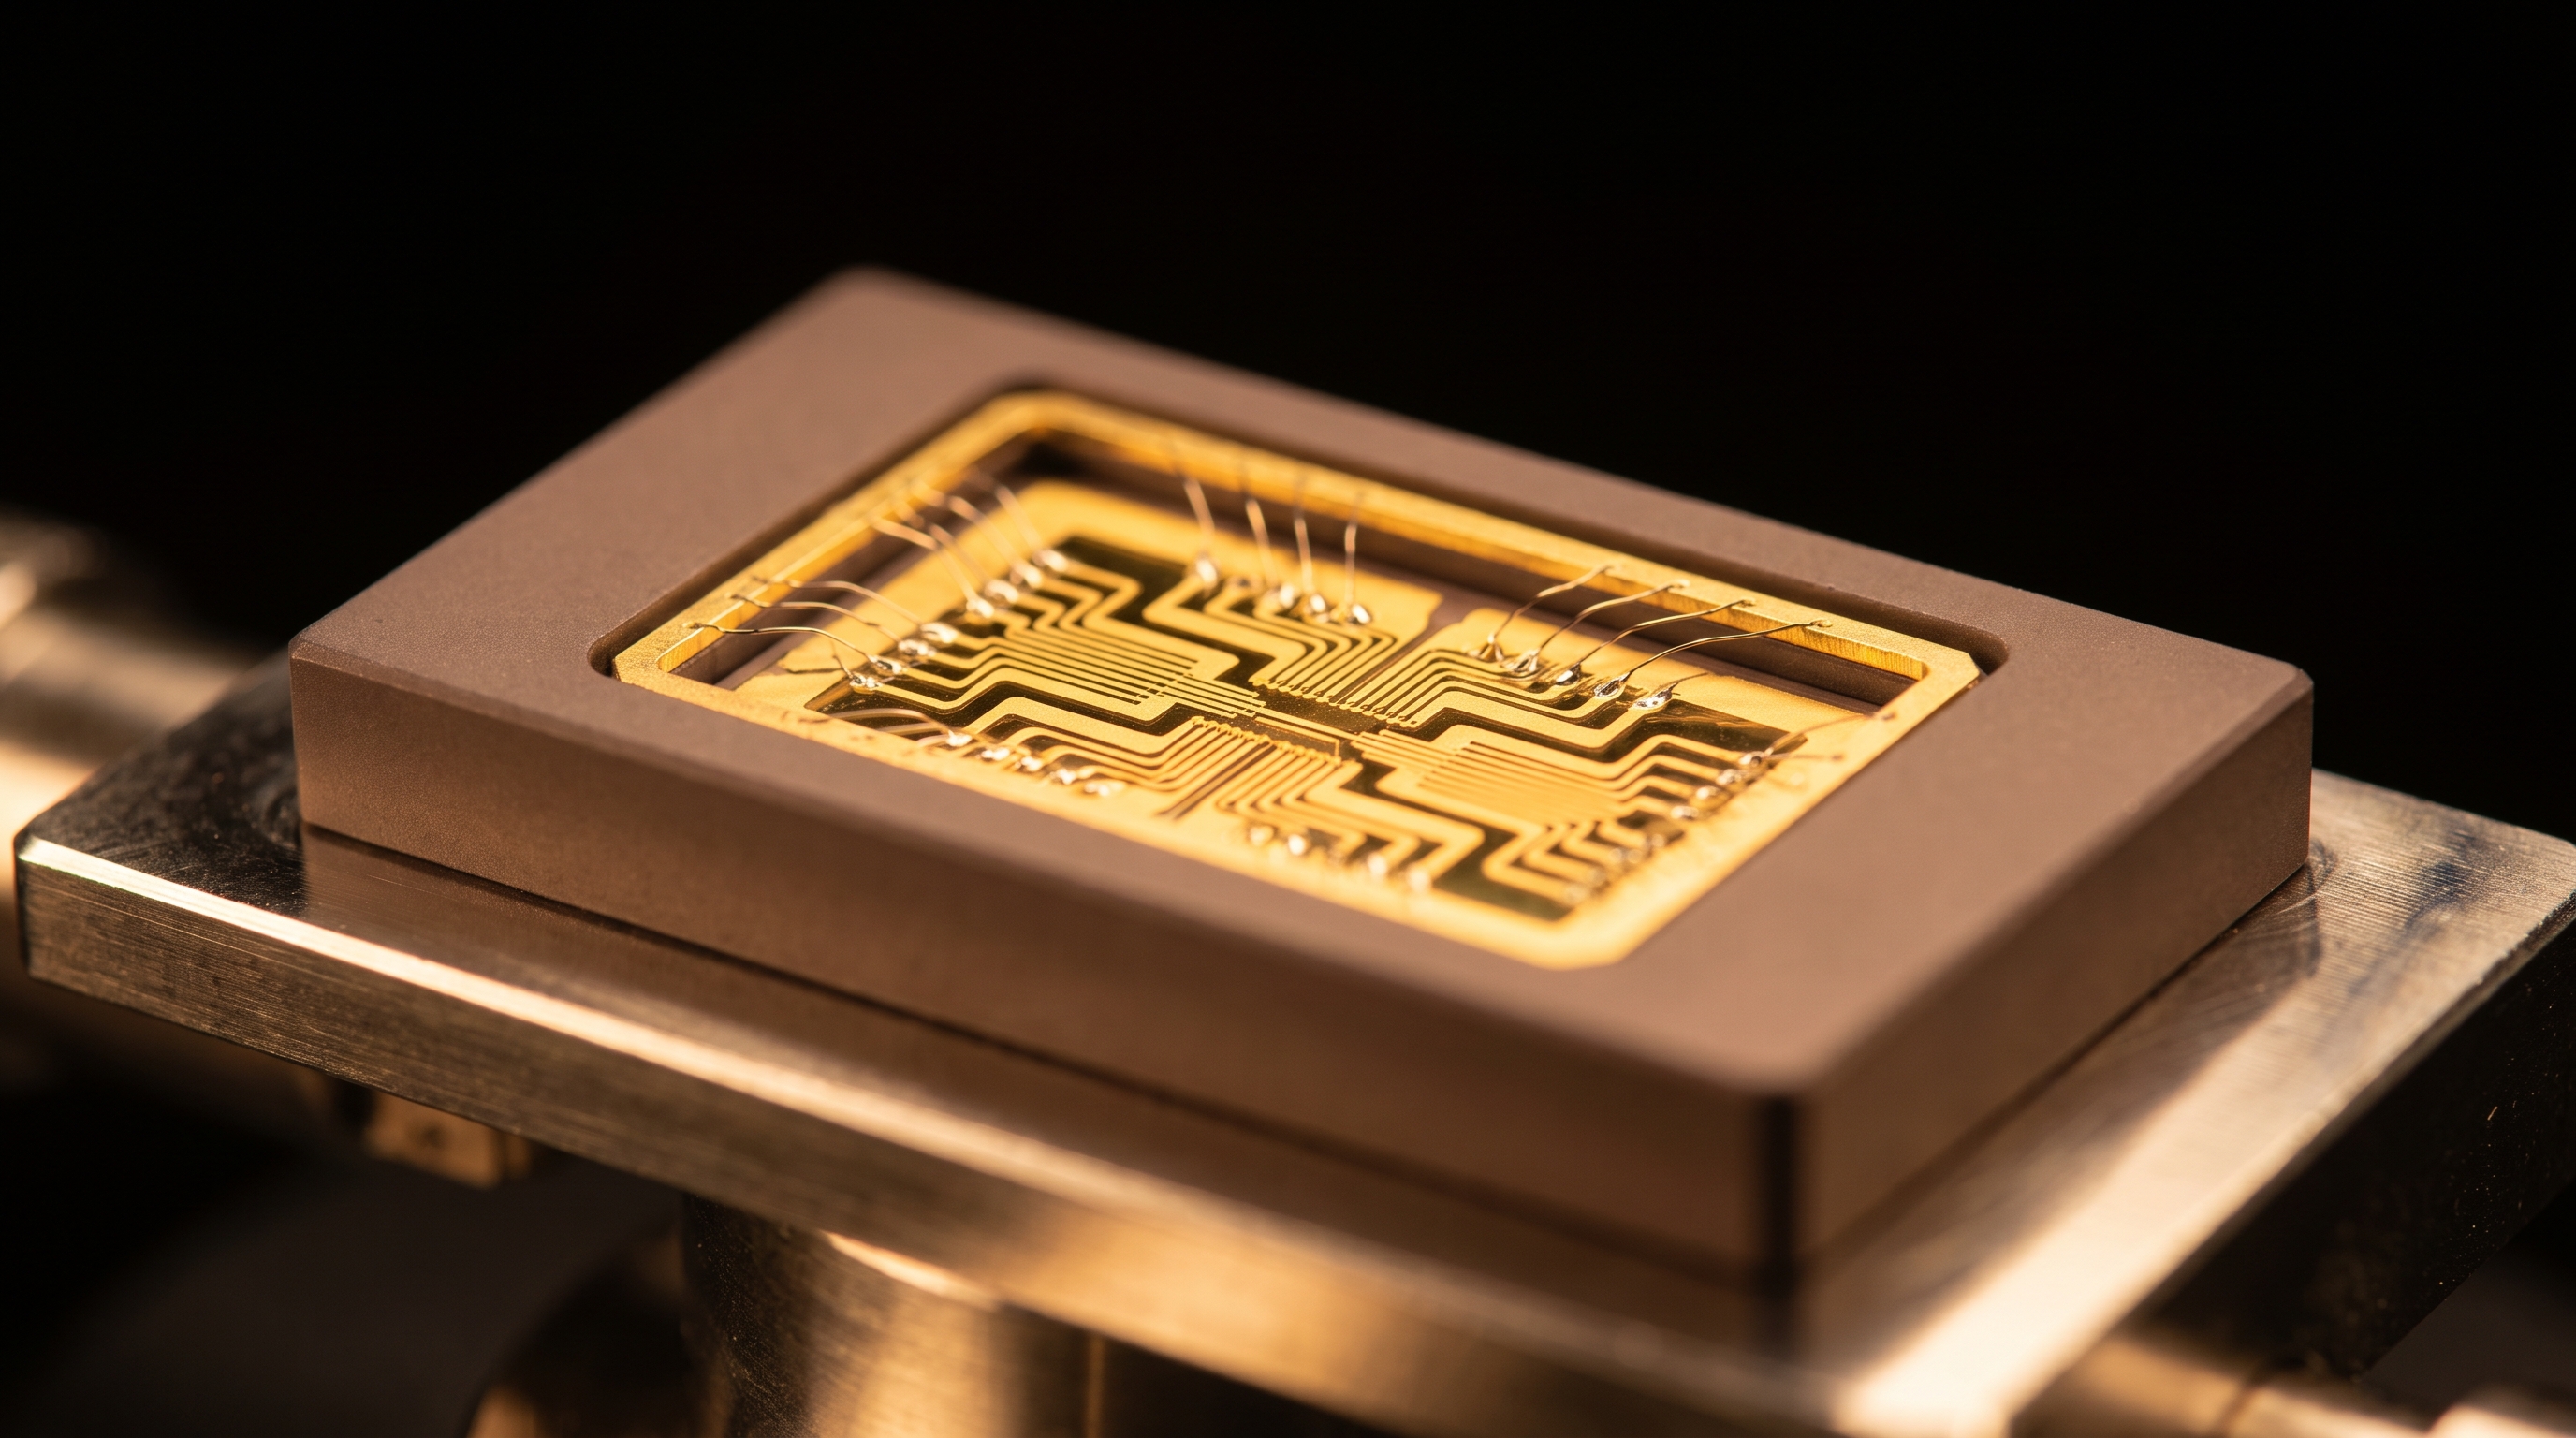
Quantinuum's improving logical-qubit error correction, 1,504 successful-circuit benchmark score and paid deployments at RIKEN, BMW and…
S Mispriced Assets 3 clicks
Nintendo's Switch 2 attach rate, flat Switch Online accounts and rising memory costs fuel a bear case, while Spotify and Netflix margins…
YT Yet Another Value Podcast 1 click
Nintendo's Switch 2 launch delivered a lower attach rate than Switch 1, while flat Switch Online accounts and rising memory costs challenge…
S Yet Another Value Blog
Generac’s $2.4 billion Amazon generator agreement for 2027-28 anchors its data-center growth thesis, with 30% projected revenue growth in…
SA  Fernanda Galvez Jalil
Grab generates 53% of revenue from delivery, 36% from mobility and 10% from financial services, using its Southeast Asian marketplace to…
S Rebound Capital 1 click
DeFi Development’s Solana treasury strategy faces dilution, preferred dividends and tight liquidity after a 50% rally, with $4.3 million of…
SA  Dorine Cherop
Chicago Atlantic Real Estate Finance's NAV-for-NAV merger with Chicago Atlantic BDC could reset its dividend to $0.37–$0.40 quarterly,…
SA  SiliconBytes Insights
Quantum Computing, QUBT, sold its first Dirac-3 system, added a second fab through acquisition and is building photonics capabilities…
SA  Marc Gerstein
Wheaton Precious Metals trades near $150, above its $99–$139 DCF range, despite 61% net margins and 88% year-over-year revenue growth from…
SA  Alexander Grover
OptimizeRx's gross margin reached 76.5% in Q2 2026, its fifth straight quarterly gain, while it reaffirmed $95 million to $100 million in…
SA  David Zanoni
Anterix’s 900 MHz spectrum could be worth $2.5–$7 billion, versus a $1.41 billion enterprise value, but insider selling and lumpy…
SA  The Market Auditor 3 clicks
Special-situations survey flags Cooper’s $3 billion buyback, Grab’s $900 million repurchase, and Beretta’s $44.80 partial tender for Sturm…
S Latticework by MOI Global 1 click

