
🎙️The Race to Build the Next Trillion-Dollar AI Chip Company
Nvidia’s rack-scale AI systems lock GPUs, networking, power and software together as trillion-parameter models push inference spending…
Thursday, September 17
Everything we published on this day.
73 stories — the front page that day →
Nvidia’s rack-scale AI systems lock GPUs, networking, power and software together as trillion-parameter models push inference spending…
Turning Point Brands awaits FDA pouch approval, Meitec benefits from Japan’s engineer shortage, and Viemed gains from Medicare’s…
Wrote about the Medtronic - MiniMed $MMED $MDT split-off for our mid-month update yesterday: https://t.co/V0EGS81yam
@MrMojoRisinX @ArbSensei @Msp194 Also worth visiting what happened with Johnson & Johnson/Kenvue a little over three years ago. $JNJ $KVUE Proration in that case was 23.23%
Sold $AER too soon from our model portfolio during the tariff tantrum of April 2025 but thankfully still have it in a personal portfolio. Took a while to play out but it worked out great. Looking at $GILD in the same portfolio today, realized that sometimes patience pays off. Now if only $LION could start behaving.
Beasley Broadcast Group's equity hinges on repaying or arranging sales for roughly $115.5 million of debt by September 2027, before PIK…
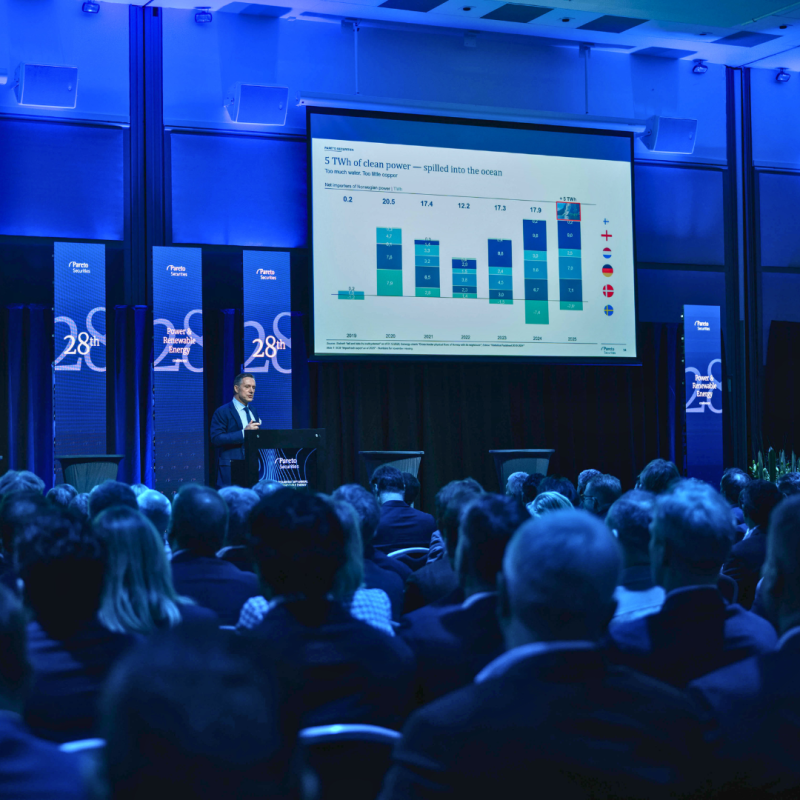
Offshore drillers have secured 105 rig-years by September, 42% above all of 2025, as national oil companies lock up long-term capacity.
$ZD doing well lately, been thinking about closing out my position but wondering if something’s up… Hmm… https://t.co/ytvQSD6x7y
@breadcrumbsre $FERG is already what $QXO wants to be! $QXO…raise tons of equity at inflated values (while Brad buys stock for peanuts). Buy companies in auctions at high prices. Pitch magical synergies to double EBITDA to raise more equity at high valuation….profit?
Broadcom’s AI semiconductor revenue rose 221% year over year, reaching roughly 80% of $21 billion in Q3 Semiconductor Solutions sales as…
Diamond Estates Wines & Spirits plans to expand grocery and export sales, invest in six brands, and improve winery operations through FY29.
Pioneer Bancorp’s acquisitions lifted loans 13.6% and Q2 net interest margin to 4.30%, but expenses, weaker profitability ratios and a…
 Crimson And Gold Research 4 clicks
But if returns on capital are declining for everyone, the choice is whether to eat or to be eaten? $T is willing to subsidize fiber as a loss leader to protect their wireless margins. $CHTR / $CMCSA are likewise willing to give away wireless to protect their broadband margins… which comes back to the question: which is stickier, your phone or broadband line? I think $CMCSA works because of the spin unlock and sheer strength of their balance sheet. $CHTR is a very long dated call option with more risk, but much more upside if broadband losses attenuate and/or they allocate capital intelligently (although $CHTR’s balance sheet is more levered, there is tremendous optionality in its duration, cost and structure).
@orrdavid Thanks for sharing this interview. Interesting that he thinks prediction markets will ultimately be a majority of $IBKR’s business.
STMicroelectronics, Navitas and Wolfspeed offer contrasting power-semiconductor cases tied to NVIDIA’s 800V AI data-center architecture,…
@kingdomcapadv @ACapitalLP $MHGU filed chapter 11 today.
The fun has just begun… $COO https://t.co/OMPI29HbQG
Do you see it? $COO https://t.co/qydMW4xaH9
@jiahanjimliu @JKeynesAlpha @PSInvestor Valuation seems a bit stretched here. I get the thesis, it’s just things don’t go straight up forever. Someone is going to cut $TEM at the knees soon.
Disclaimer: I have sold this position and have no view on the valuation or future prospects My craziest OTC adventure this year was discovering a single-asset refinery that sells Jet Fuel to the US Military. It sounds kinda crazy, but it's the exact type of ridiculous setup funny enough to look into. In July, refining crack spreads were blowing out, and nearly every refiner $PBF, $PARR, $VLO, $PSX were steamrolling. I wanted some exposure, but I felt sheepish chasing names that were already tearing it up. I started looking at smaller refiners, but nearly everyone was in the 3x - 5x forward earnings range, not expensive, but for a cyclical, also not really that cheap. It turns out that, aside from the megacap refiners and $PARR, there's only one other US listed microcap refiner, Blue Dolphin Energy $BDCO. The stock is heavily insider owned, and at the time, was trading at just over 4x Q1 earnings ($0.99). Crack spreads are publicly viewable, and other refiners were demolishing estimates - $PARR came in at $11 in Q2, triple Q1, so it didn't take too much math to realize BDCO's Q2 was gonna be strong given jet fuel prices, and that the stock was potentially trading under 1x forward earnings. Of course, it's an OTC name with limited liquidity so you can't realize size it up, but how often do you get a chance to buy someone who supplies jet fuel to the Department of Defense under 1x annualized earnings? It was almost comedic, the story was funny enough to swallow the OTC stigma and just pick up a little bit up. About a week later, Q2 results came in at $1.19 (putting 1H earnings at ($2.18), and the market suddenly realized a stock trading at $4 on $2.18 of two quarter's EPS was just too cheap. The stock hit $18 today - I've been trimming since entry and am finally out. It was a tiny position, but I continue to find it ridiculous that these OTC setups exist. With a small amount of capital and a love for reading filings, you can probably find a slew of OTC names that are actually decently profitable that are simply too small for larger investors to take a stab at. I have no position in BDCO and have no opinion on it, $4 and $18 are totally different prices, but the fact this setup existed and somehow flew under the radar until earnings is pretty entertaining.
@mike_astarita Yes, $BNCC shareholders approved the merger.
@Jason @evanspiegel "After Elon Musk acquired Twitter in 2022 and re-organized the management and governance structure, Calacanis helped transition Twitter along with David Sacks.[25]" Jason - time to help transition $SNAP/Specs. Run the same playbook.
@Jason @evanspiegel The progress is impressive. But mass market adoption remains years away. They need a size minority equity investor. If they get it, $snap goes up 50%.
Huawei just updated the Ascend 960 & 970 roadmap. $NVDA's competition pressure is increasing from both $AVGO and Huawei continuously as we've anticipated. → 960DT rollout pulled forward from 4Q27 to 1Q27. (Seems like they are finally getting the HBC-like, tailored-memory approach closer to high-volume production.) → 960PR by 3Q27 with 8 PFLOPS FP4—double the 960DT’s FP4 compute. (Closing in on NVDA’s Blackwell Ultra, which tops out at 15 PFLOPS dense FP4. Rubin moves that target to 35 PFLOPS dense FP4.) → 970 by 2028 with 14 PFLOPS FP4, up from the previous 8 PFLOPS target. Overall, this looks consistent with our Tau Scaling thesis: a higher compute ceiling, more tailored chip designs, and a faster path to production. Not every specification has doubled, but a near-doubling of the 970’s planned FP4 compute alongside an accelerated 960 rollout is a meaningful change. The bigger story, in our view, is Huawei’s CIDM model. Optimizing the entire vertical—not just the logic die—creates more room to change the compute design and shorten the development cycle. Huawei’s disclosed co-optimization already spans devices, circuits, chips and systems. This is the kind of vertical integration Elon Musk is targeting with Tesla and SpaceX’s Terafab. But Huawei is already putting its ecosystem version to work. (Would be quite funny if the Chinese ecosystem gets accelerator-based EUV into production lithography first, too.) Against NVDA, our thesis is that the single-chip gap narrows from roughly three years toward two—and potentially less as the roadmap accelerates. From a PPAC perspective, Tau Scaling could bring the logic die within a year—or less—while memory remains further behind. Bandwidth, not simply capacity, looks like the harder bottleneck. But Huawei may be able to lean into memory capacity and co-design the LLM and serving strategy around that constraint, rather than simply copy something optimized for NVDA’s hardware balance. System-level performance still needs to be proven at the cluster sizes Huawei is targeting. But we would not be surprised if it works better than expected. Even before the full UnifiedBus vision is realized, we think Huawei could gain system-level performance leadership on some large-model workloads sooner than many expect.
$CAR: its hard to believe that the largest, most violent short squeeze of the year was in a stodgy, underperforming rental car company. https://t.co/yuRYzlSmmQ
@patientinvestor $CHTR too! ;)
The $FNDM story just keeps getting better for shareholders and weirder at the same time. After the large dividend in December FNDM still held Bitcoinica BTC claims from the settlement with Thomas Braziel. The receiver decided to sell the claims now rather than wait. He hired a firm to solicit bids in an auction. The winning bidder was an entity formed by ..... Thomas Braziel. The proceeds from the winning bid is why another $5.60 per share dividend is coming this week. A final small distribution is expected later.
Bank7 Corp. $BSVN to Acquire Century Financial Services Corporation and Expand Southwest Franchise into New Mexico https://t.co/EBkIPiIu5X
What’s the bear thesis on $MGM here? All of the $PPLI Barry deal premium has evaporated. Even if his bid was fugazzi, it highlighted a valuation disconnect especially as it related to Asian assets… What am I missing?
Energy Storage / BESS systems are really getting to be a big deal. Mover today on $TURB. https://t.co/eWx8SYvodP
@scottfelsenthal thanks - bought $MRP a few months ago
Greenhaven Road @GreenhavenRoad took a full position in Burford Capital $BUR on the economics of its protein price-fixing book: Burford has put more than $150m of its own capital into the chicken, beef, turkey and pork cases, so it keeps all of the upside rather than sharing it with a client and it controls when the cases settle. The track record behind that underwriting: 285+ concluded cases, 90% won or profitably settled, an 82% return on invested capital over a 2.6-year weighted average life for a 25% IRR. The catalyst is dated — the chicken trial against Tyson Foods, Pilgrim's Pride, Koch Foods and Cargill is set for 2027.
Progyny's Q2 revenue rose 11% excluding Amazon, with margin expansion and nearly 100% EPS growth guidance for 2026 supporting…
 Robert J. Lake
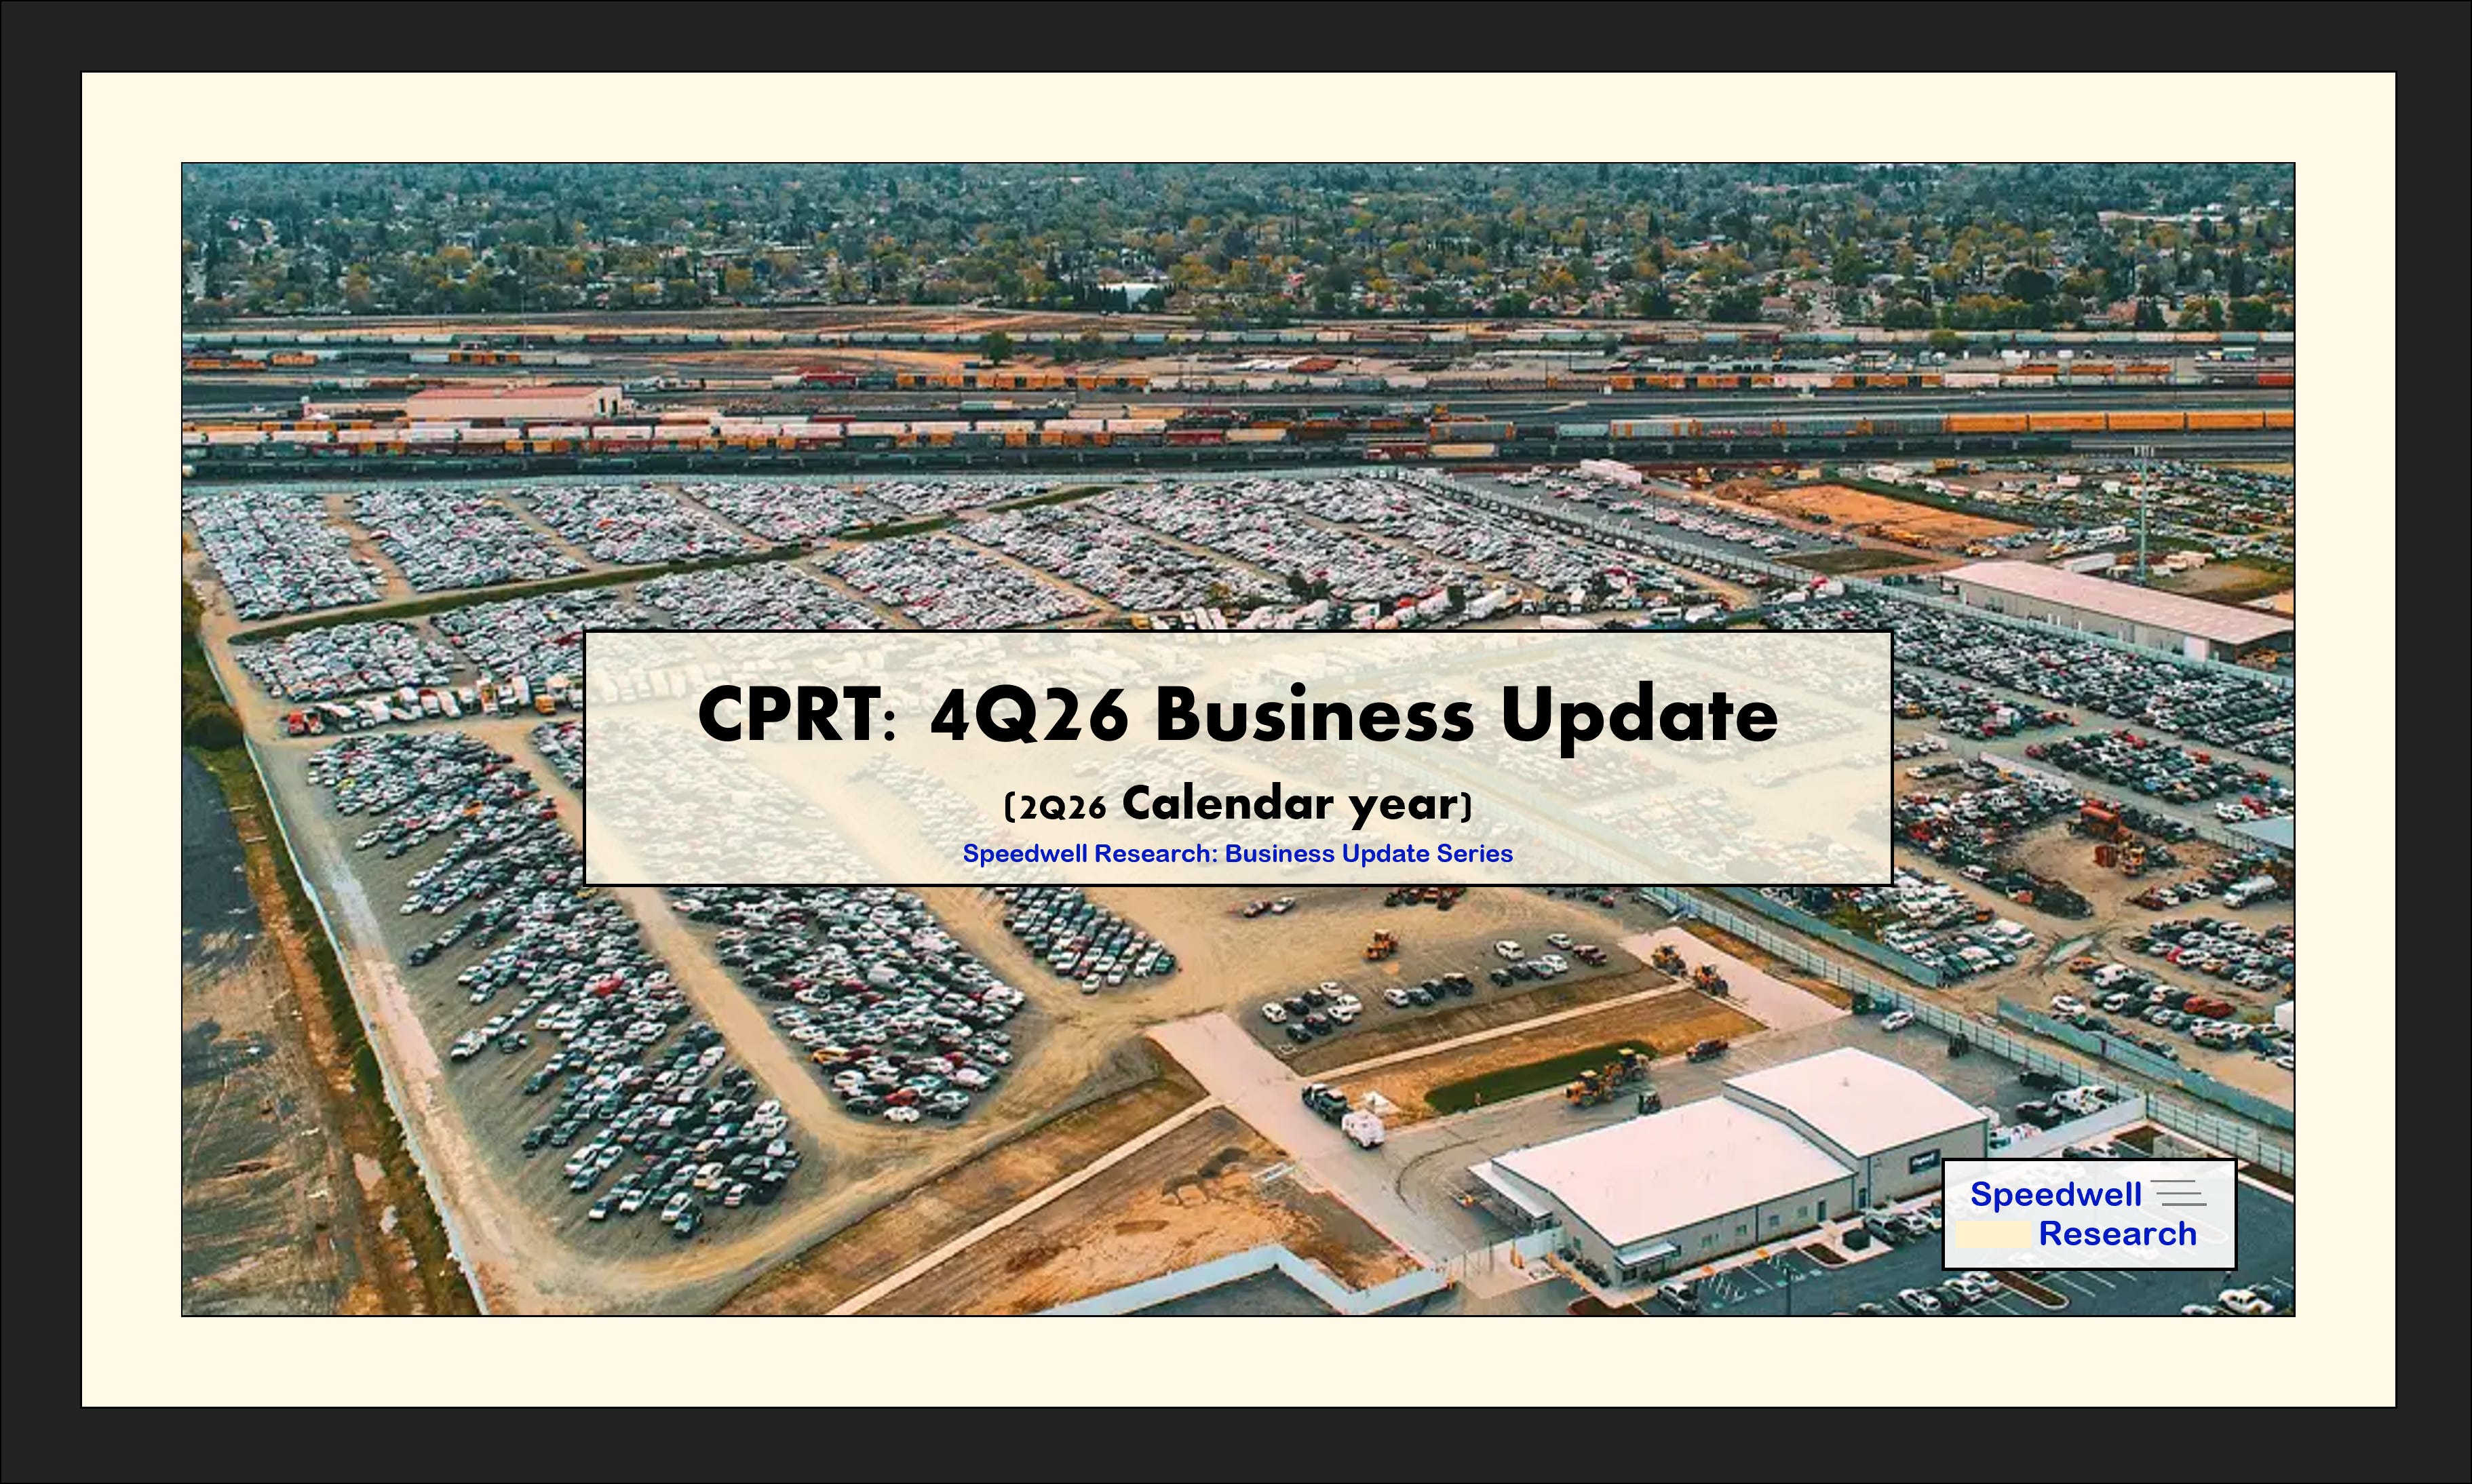
Copart's U.S. insurance volumes fell 7.5% in 4Q26, largely from one customer loss, while international insurance units rose 11.2% and…
A “gift” is when some person and/or organization creates a narrative misperception that creates a dislocation in an equity. Dario did it with $CORZ / $CIFR this weekend. Bloomberg News continues to do it with $OWL https://t.co/z7VfaqffDk
Viridian Therapeutics is building a shared commercial platform for Lumvoa and investigational elegrobart in thyroid eye disease, with…
 Equity Eagle
Jackson Financial administers $287 billion in retirement accounts while a report says its captive, hedge-loss installment plan and…
What price does $GFL get acquired for?
I will add after this weeks 30% rise in man of these names. A lot of them need cash, they are low on their cash balances with cash burn businesses. $TXG through 70m already this year with only 200m in cash, plenty others that are similar. I imagine they are about to hit the bid and soon
SMR reactors last year or quantum...appears the current moments basket of trash stocks with a narrative that doesn't fit the companies is 3rd derivative ai drug discovery plays (genome, simulation software, etc). $TWST $TEM $SDGR $TXG and theres more My favorite is $WGS - opko rehash with key players from there somehow sitting on a multi billion dollar valuation currently. There were caught with billing schemes multiple times at Opko as well as other serious problems (see Philip frost and opko). A member of the board actually still sits on Frosts charity and the CEO was the CEO of Cathie Wood favorite Invitae, that went bankrupt a few years ago. The short story writes itself, seems like a CVNA almost where the setup is pretty opposite, and yet it probably continues to work against you
@jrkelly @Ginkgo why have $DNA sales imploded under your leadership? https://t.co/E8nrXG5pSl
Alpine Capital @jdsdebruyn reduced semiconductor exposure and added hyperscalers after the June pullback, citing combined hyperscaler capex of approximately $416bn in 2025 projected to exceed $750bn in 2026. It initiated Oracle $ORCL, and concedes the entry has not worked yet: “Oracle’s price action since initiation has been disappointing, but we believe the valuation is attractive and the current view on Larry Ellison (co-founder) is probabilistically asymmetric given the entry point. Oracle can slow spending if AI reverses (which we do not think will happen).”
PBF Energy benefits from elevated crack spreads as refinery capacity cuts and oil prices support margins, with 67.5% of spread increases…
 Andres Veurink 4 clicks
5/X The Setup: At ~10x earnings and a sub-$1 B market cap, $PSIX is being priced like a distressed Permian parts supplier, ignoring its structural position as a pick-and-shovel toll road for AI compute infrastructure. Full deep dive on Weichai’s global playbook and the $PSIX setup on our website:
3/X The $GNRC Generac / $AMZN AWS Trojan Horse: Tier-1 OEMs ($CAT, $CMI, MTU) are locked in 24 month+ lead-times. $GNRC stepped in with an $8B Amazon backup deal, but GNRC lacks large-bore diesel blocks and enclosure capacity. Who bridges the gap? The Weichai Ecosystem. PSIX monetizes the buildout whether AWS buys through Cat dealers or Generac.
4/X The Prime Power Endgame: Backup power is just the wedge. The prize is prime power. SemiAnalysis recently flagged $META and Anthropic deploying 300–500MW sites using 21.9L gas engines— the exact spec $PSIX supplies. As Weichai pushes its larger 12M55 and 20M55 gas engines through North American UL certification, $PSIX becomes the domestic vessel for low-cost, off-grid power generation.
1/X Weichai Power has compounded at >20% p.a. since its 2004 IPO. Yet its most asymmetrical asset isn't trading in Hong Kong—it’s hiding on the Nasdaq: $PSIX. Down 2/3 from its highs and trading at ~10x FY26 P/E, the market is completely mispricing its role in the U.S. power crisis. 🧵👇
2/X The Blind Spot: Everybody left the game when $PSIX began missing earnings since 3Q25: Jim Cramer advised people to "cut your loss" after 1Q26, thats despite telling investors to be a "Buyer Down Here” post 4Q25. Leopold left the game post 1Q26, after first buying 4Q25. Meanwhile, Maius has continuously been in the game since 2024!
$SVM out with a new repurchase program. I'm still long. https://t.co/qk02dmc1q8
You know it’s gonna be a good day when even $AMZN is getting bought
@Fwenen $QXO vs. $XHB 🤷♂️ https://t.co/ueiuutNvlX
Just surfacing this one to demonstrate we are not and never were $snap absolutists. We will go long and short and when facts and circumstances change our opinion changes too. And NO - Specs will not be a mass market hit this holiday season. Too expensive and awk form. But here's the bull case from here: 1. FCF/Share is the metric mgmt now focused on. By definition that requires fresh cost and SBC discipline. 16% hc reduction and flat share count already in place. $500mn in opex savings about to flow through. 2. Ads biz stable enough. 9% growth in Q2. Guide implies so decel. But ad checks stable vs Q2. Decent enough. Some progress on ad tech. Only needs 5% growth next year to hit our numbs. 3. Sub biz $1.2B rr, growing 85%. Needs 50% growth next year to hit numbs. 25mn paid subs, still well below penetration threshold of 7-12%. 4. Specs tech is real. 7k+ patents. Real use cases. What's that worth? $META or $MSFT or $AMZN could buy Specs for the patents alone and pay $2B and it would be nothing to them but all the call optionality which could incubate until form factor is mass market. 5. Lets just say Specs is worth $2B to a strategic buyer or partner. That implies $snap 7.5B or $4.5/ share. In this scenario then FCF/share at SNAP goes to over $1/share, easily. So 4.5x FCF on a business still growing revenue mid teens. @evanspiegel Specs are cool. But can't keep spending $500mn a year on them. Bring in a minority investor please and lets make SNAP stock great again. @IrenicCap
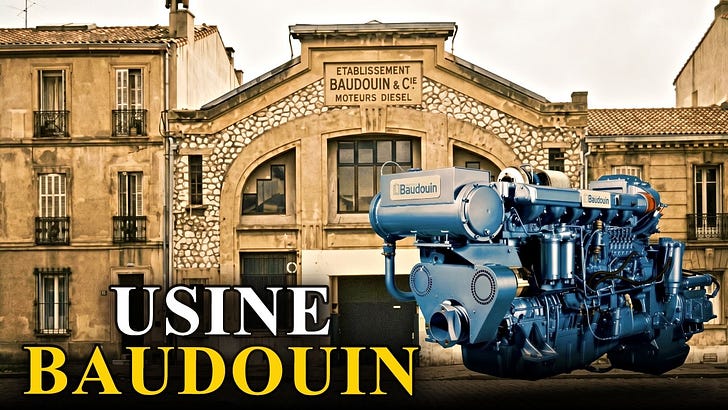
Weichai Power built a global engine group through Baudouin and a 46% stake in PSIX, positioning both for large-bore generator demand from…
Pool Corporation trades at a claimed 33.8% discount to fair value, supported by a 64% recurring-revenue base, buybacks and a rising…
 Mark Bern, CFA 4 clicks
BERETTA HOLDING S.A. COMMENCES CASH TENDER OFFER FOR SHARES OF STURM, RUGER & COMPANY, INC. FOR $44.80 PER SHARE $RGR
When Spiegel sell $SNAP to Bending Spoons? They could crank up the Premium+ prices by threatening to delete everyone’s memories if they don’t pay up Valuations pretty depressed, seems right up their alley
Vizsla Silver's Panuco project in Sinaloa remains shut after nine workers were found dead, delaying construction of a fully funded 17.4 Moz…
@taobanker I hate to be that guy, but it's all Yen depreciation. The good news though, is at least it isn't $ARCO. https://t.co/qlBUlAF63w
I can see that being true. But when you’re playing in the smaller cap universe, the information disconnect edge is crazy huge. Because less investors are looking at these stocks, no one‘s really finding the information. But yes, when people discover the info, the interpretation phase kicks in. With big caps it’s more about the interpretation phase because everyone is looking at the same information. With microcaps, you have two MultiBagger forces happening: Early information discovery + interpretation. By the way, let’s not forget that there’s so much information out there to interpret, that it creates “brain” overload. It’s going to be interesting to see how AI plays a part in solving some of that problem. 👊But generally, I do like your interpretation angle. It’s funny because when you find information arbitrage in microcaps… that’s so obvious… sometimes you have no movement in the stock because people are either interpreting it wrongly or just don’t believe it, etc. By the way, $HPE would be another good Bigcap Case Study you could use to support your interpretation argument. It just sat there at 15 bucks, as people debated their relevance in AI… And then overnight it goes to $50. I rarely buy big caps, but I got lucky and actually bought some call options ahead of the move.
https://t.co/5BLPWc2ddm $ALTO $GPRE
DiamondRock Hospitality raised 2026 guidance after Q2 RevPAR rose 7%, AFFO climbed 25.7% to $0.44 a share, and net debt to EBITDA reached…
 Philip Wang
This is actually a great point. $QXO is an opportunistic acquisition vehicle, not a plain vanilla building products company like $BLDR. If it’s just trading with rates, that could be the opportunity… https://t.co/yhGuyFWQAT
Did you see $OWL dip below $10 again yesterday? Even in a pretty draconian case, this thing is worth ~$9 at ~14x FY27 FRE (upside is $15+). Credit remains stable, redemptions are moderating, fundraising is strong and AI infrastructure demand isn’t slowing… That’s asymmetric opportunity.
$RGR have been out of this name for a while but will take a closer look on today's news that the Beretta agreement will proceed. https://t.co/wKoJJ0N85w
Uber trades at 14.5 times trailing free cash flow, while robotaxi competition and a Delivery Hero acquisition test its growth and leverage…
 M&M Capital
10% owner too $BUKS https://t.co/Jko5en4Z0h
$BUKS insider buying https://t.co/UGTZeMIqV0
great article - thank you for sharing $DFH https://t.co/XCJH6QOE9u
Zoetis faces U.S. companion-animal competition and softer demand, pressuring key franchises despite strong cash flow and a nearly 50%…
 PV Research 4 clicks
Enbridge’s 5.1x leverage and $6.45 billion of 2027 maturities raise refinancing pressure as Venezuelan exports and new Canadian pipelines…
 Melissa Tucker 4 clicks
Figure Technology's HELOC platform grew Q2 2026 revenue 113% with a 54.6% adjusted EBITDA margin, while shares trade 57% below January's…
Vistra’s Q2 2026 results reinforce its PJM and ERCOT generation advantage as AI data-center demand tightens power supply, supported by…
 The Curious Analyst 1 click
A few take aways from the $CRM Dreamforce keynote today.... It is difficult to watch at times with all of Marc's promotional showmanship but still worth it to understand how a bunch of legacy software companies are attempting to reposition themselves in terms of the AI era. The sell side will defend this tomorrow, thats the business they are in, but you should look at it for yourself unbiased. Ask yourself this first: .....you can claim SaaSpocalpyse over, the V shape rebound came, ARRs didn't plummet overnight.... That was never going to happen, the newspapers are still here, but their subscriber bases are decimated, or they moved online and the pricing models were drastically decreased. Reach potential increased, but so did competition (exponentially) and barriers to entry were and are radically lower then pre internet. If this was not existential and just a panic and the rebound is entirely justified why did the largest SaaS application company just remove their ui, conceded their metadatabase to their biggest competitor and is undergoing a pricing model change in real time, so change is upon us, time to look what happens next CRM going full force into being basically a database company now, hoping the underling data you built with salesforce over the years and the legacy connection will be enough to keep you around and paying them to essentially host your data for you with a Claude or other ai intelligence on top doing the work. Slack is the most relevant product they have and the biggest sticking point in those conversations, but how long will that last? Zoom should have died off by now, with Teams and others giving away video conferencing which shows you entrenched behaviors and a narrow network effect can defeat economic interests. Time will tell on slack. Ultimately I think a layer like snowflake that can tap data structured and unstructured across applications is the data layer and governance apparatus to build wrappers and dashboards from using multiple Ai models. Versus keeping the data siloed into the old applications from the prior generation and having to access them, or pay them all individually as databases and then building a mass MCP through all them to get to the unified data solution (much easier then ever before to migrate and move data the friction has dramatically been lowered). Seems a lot easier to have one data layer across an enterprise versus taking a salesforce, connecting it to Claude then having to connect that to Gong, granola, gmail, etc for your sales force and cs reps. Then creating channels with workday or paycom and connecting special channels for intuit and adp separately. And so on with each roles/departments specialized applications they use in a given day and giving database, governance, ai training, security etc and having to manage and permission all of these ai/database modules versus a central one stop shop with Databricks or snowflake (id say amazon or google, but no one is going to go all in on one cloud storage for outages and pricing reasons if large enough but I think they have a better argument/permission to win this space if they wanted to then Salesforce or worse a Paycom)....see the snowflake Q2 call to better understand their vision as competing to Marcs strategy laid out today. End of the day, I don't think when you look out three years these SaaS applications have the same relevancy in terms of users but more importantly on pricing (dropping the UI works for AI and looks cool in a demo, but it also erodes your brand and shared user behavior across organizations which was a piece of the stickiness of the solution over these SaaS years). CRM is likely better suited then most of the other applications ironically due to their largley paned at the time acquisition of Slack. I don't think it provides immunity but a solution to cling to in bundled conversations where their numbers may slow slightly less fast then some of their contemporaries. Point solutions continue to be first in line, communications too. These businesses are not impaired to zero today, but their pricing and expansion (new logo and NRR) that is going to be continued to be eroded. Newspapers are still here, magazines too but their subscription based was drastically hollowed out. My view is the SaaSapocalypse was directionally correct and narrative largely holds, the markets in short term may have over run with that theme (some single digit true ebitda multiples) but thats on old business models and we have largely filled the entire gaps to where its attractive to take the outlook of where these businesss are likely to head in the coming years again. They will show amped AI revenues (as they rename and push anything named AI for the sake of all other revenue and rename, bundle to get to say "AI revenues up 80%"....but total ARR, NRR still continue to be flat to declining), they are pushing duration and discounts to achieve this as they themselves scramble with ai models and solutions and rush to make with large over promises, and leave clients with messy solutions that frequently break, have real security issues, and underwhelm the capabilities the sales team pitched (I listen to this daily from my wife whose a cs manager at a software company, and the majority of my friends who work in software in various capacities).
