
Todd Wenning on X
I is the quality-value investor answer A is the quality-growth investor answer F is the dividend investor answer E is $JKHY https://t.co/bYF8O8zbSl
Sunday, August 16
Everything we published on this day.
16 stories — the front page that day →
I is the quality-value investor answer A is the quality-growth investor answer F is the dividend investor answer E is $JKHY https://t.co/bYF8O8zbSl
Newest out. Haypp Group: Welcome to the Jungle $HAYPP $PM $BTI $MO $IMBBY $STG https://t.co/KwDvNgLwKY

Trinseo PLC’s Chapter 11 trial centers on a potential settlement as Judge Lopez urges peace among the debtors and creditors.
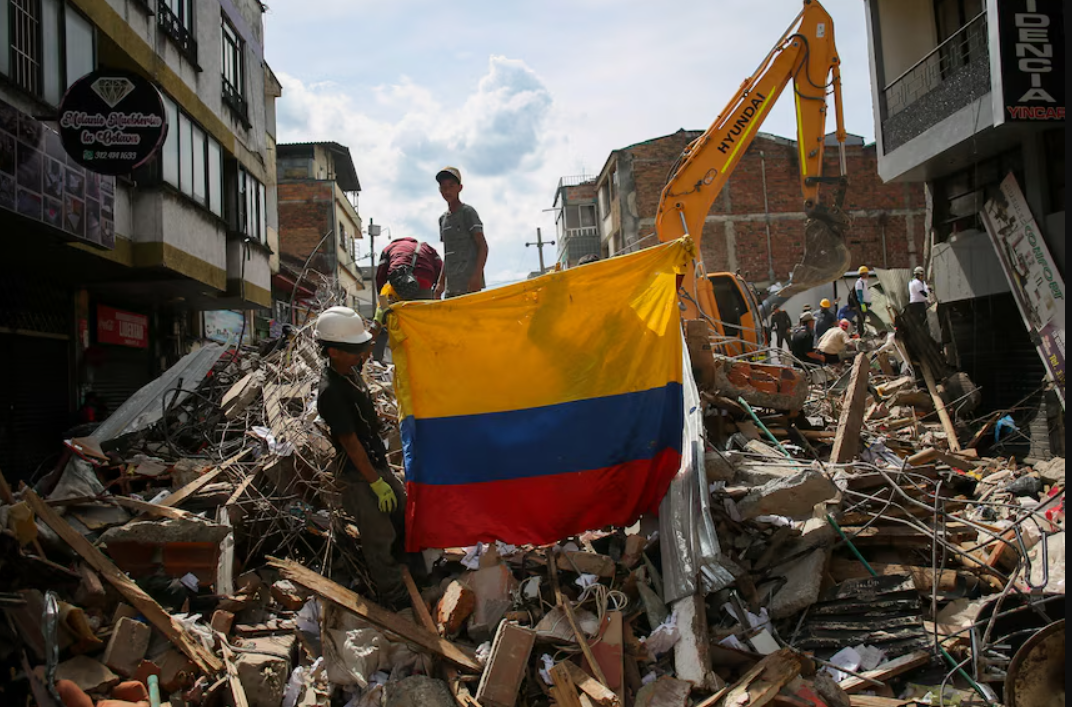
Colombia’s earthquake frames risks for Tecnoglass as Grupo Aval, Bancolombia and Nu report strong earnings, including Nu’s 67% EPS growth.
Uber generated $52 billion of FY25 revenue and $10 billion of free cash flow as investors weigh whether autonomous vehicles can erode its…
Cerebras Systems’ WSE-3 wafer-scale chip targets low-latency AI inference with faster decode than GPU racks, while higher per-token costs…
@TheBigLong2019 Humanoid robots is AI adjacent, but I agree with you on $OUST
$RKLB at $5 - $2.5b valuation for the only real launch vehicle business that is competitive with SpaceX. Founder led, engineering focused, good M&A deals. Sold at ~$50 last year. $PNG.v at $1.2. Subsea batteries moat, co-developed products with Andruil, huge ramp, good management.
Whirlpool's credit curve is interesting because the belly of the curve is much wider than the long end. Typically, the further out a maturity is, the higher the credit spread required to compensate you for the additional risk. Here, the dollar price of the long bonds is so low, they carry less downside per dollar to the same recovery, plus all the torque to any good outcome (asset sales, M&A, turnaround, etc). Investors are paying a premium for that $WHR

Hyperscalers’ off-balance-sheet lease and purchase obligations rose from roughly $1 trillion to $1.5 trillion, turning the AI buildout into…
@keisan_15 Yes that is why I liked $MEDP
I privately told a few fund managers I respect these investing themes/theses privately: "AI is going to drive far more medical/biotech research in pursuit of age reversal technologies than we had before. In fact, at least a couple of these are reasonably likely to be the most valuable companies on the planet in 10-20 years." and related, "Many of the old medical research companies are dinosaurs, since their tech will not keep up with the new age of AI driven medical research." I told them this at the start of 2025, and for example mentioned they avoid shorting $ARKG type stocks. I could tell they thought I was completely retarded, out of my mind, etc. A couple thoughts: 1. I bet those people don't think the idea is stupid at all today. and 2. Having a thesis that seems insane but is often wrong is *awesome*. It's a heads you win, tails you lose nothing situation. Besides $MEDP long, I didn't really know how to play the idea other than avoiding a bunch of shorts. These are theses I still very much believe today, and still today I don't see people talking about them.
@olliejmorgan $MEDP was like this.
@MoodyWriter13 I think $NBIS is as viable of a business as $OKLO is -- that is to say, a clear stock promote as opposed to a for-profit business. But little reason to post about it. The bulls have their view and reality will come for them in due time. I'm not going to change their mind.
New writeup on the 'Stack. MegaChips (TYO 6875). After-tax stake in $SITM in the U.S. + NCAV is ¥19,842 vs ¥11,250 stock price. Operating biz is capital light and management aims for ¥10bn in OP in FY30. There's other financial assets too. mcap: ¥158.3 billion ($1 bn USD) https://t.co/gPhHG8P5nY
HubSpot trades near its 2020 share price despite quadrupled revenue and $750 million in free cash flow, with Breeze AI upside weighed…
