
Nintendo: Churning Recovery (Ticker: NTDOY)
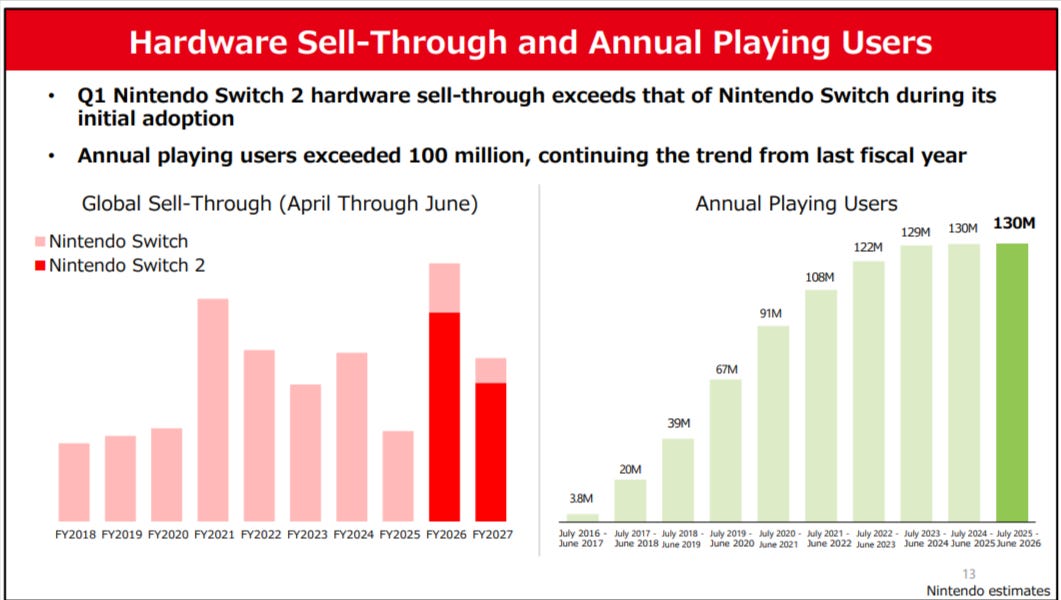
Nintendo’s Switch 2 sold 23 million units in its first year, but software delays, memory-chip costs and yen weakness drove NTDOY from $25…
Friday, August 14
Everything we published on this day.
34 stories — the front page that day →
Nintendo’s Switch 2 sold 23 million units in its first year, but software delays, memory-chip costs and yen weakness drove NTDOY from $25…
@Gubben89 Replacement cost for $MU production capacity is probably $100-150B today. Why doesn’t @elonmusk announce that he is going to spend $50-100B building DRAM/HBM in US? A pittance for $SPCX and resolves the bottleneck? Even if it takes years, it helps alleviate current price gouging?
Coherent’s Q4 FY26 results prompt claims that poor 6-inch InP laser yields are limiting margins versus Lumentum in co-packaged optics.
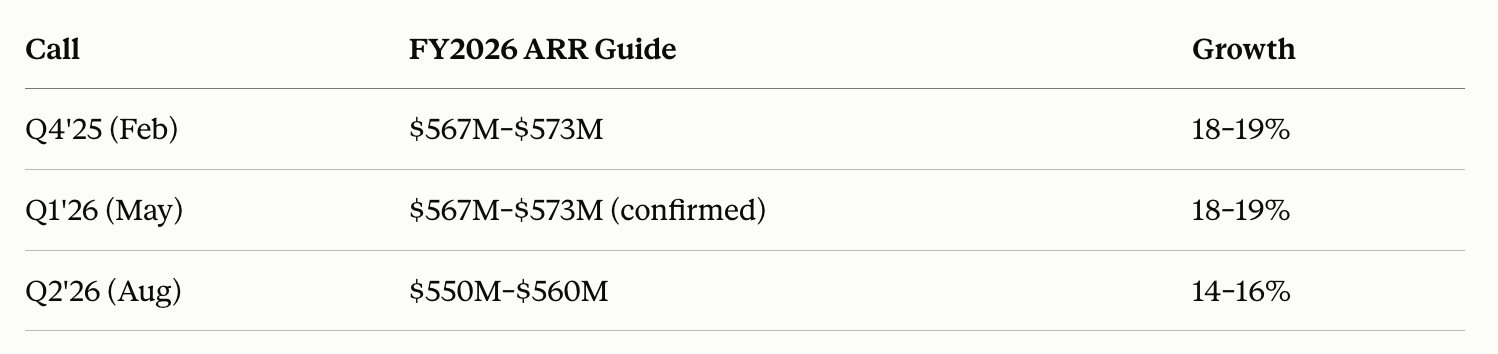
Cellebrite cut 2026 ARR guidance by $15 million, replaced its CEO and saw shares fall 30% as elongated sales cycles raise execution…
Looks like a nationwide bankruptcy... Huge for $PBI presort business... https://t.co/giIQNCyH2Y
Tiny, but perhaps interesting. Neuphoria $NEUP will be acquired by Scancell in an all share merger, resulting in a Nasdaq-listed Scancell (SCLT) alongside Scancell’s AIM listing. The current ratio implies $4.55 per NEUP share (~16% gross spread), plus a few CVRs tied to several milestones. partnered asset milestones. The deal is paired with up to $89m of new financing, plus $10m of Neuphoria cash, to fund Scancell’s Phase 3 iSCIB1+ lead melanoma trial through key readouts into 2029.

NRP has retired debt and preferred stock, leaving 13 million acres of mineral rights to fund higher cash distributions, buybacks and soda…
Nvidia GPU rental prices are rising across generations, supporting a $500 billion push to finance AI compute as a durable, rentable asset…
“Just buy $NVDA and let Jensen allocate” https://t.co/HZXjfyro5e
$CLBT - You can make a pretty compelling case that the guidance cut was to kitchen sink the expectations for the new CEO so he has a bottom base to build off of. From the call 4-5 major deals slipped out a quarter, and Genesis isn't ramping as fast as originally thought, but new products are growing +25% & they have tailwinds in terms of FedRamp & YoY US federal basically didn't grow last year. Next quarter they beat, and re-raise guidance and stock is back to $16. 50% return from here in a quarter. Clearly if they can't close deals in Q3 at a faster pace then the recovery takes longer, but seems like good risk-reward here. Full disclosure: I added some at $10.5
Artemis is going to be a huge driver to $LUNR growth over the next 5 years. $2b market cap @ $13 / share kind of feels like early $RKLB at $2b @ $5/share. https://t.co/KaaQ7mFlSt
Honestly $C is pretty fairly valued now, I don't there is much upside at all aside from the entire sector carrying it up. $OPBK continues to be heavily disrespected, think we are entering the "on par with peers phase" where CUBI and OPBK and ASIC have a chance to trade in line with competitors. Implies 20-30% upside on each, but will take some time.
Blackjack 21 hits 36% YTD, 29% above financials. Performance would've been a bit better actually, but I paper handed $WSBF, $HRTG, and $SNEX. Next week, will be adding a small cap financials name to the list, first new member of the Blackjack 21 in months. Below book, repurchasing shares, extremely niche, it'll be a fun one.
Must read imo on $OPEN. Scott raises some great points about the potential if things go right. I have no position rn, and have a more pessimistic view than Scott on the value of Eric Jackson's involvement (my view: he certainly kickstarted but unfortunately showed his true colors stalking a random celebrity for no reason. He is a liability now).
I’ve always felt that shares outstanding in microcaps tells you about the soul of Mgmt. So I instantly connected with @bmb21 when he made a similar comment pitching $AMNF at @MSmicrocaps summer virtual: “Share count tells you how Mgmt. feels about the sanctity of the shares.” https://t.co/88XsqxHLKB
This is the kind of stuff that gives microcaps a bad name. $SURG cites a large income number in their press release headline, but the adjusted number is a loss. GAAP accounting allows this, but it’s so wrong and shouldn’t be allowed. Shares are up. Someone’s going to get hurt. https://t.co/kYsB4WXMND
Not bad earnings at $MCCK. Gold book took a mark to market loss. But core business is kicking at. Revenues up 8.9%. Gross margins expanding. Customer deposits and deferred revenue up 33%. Back out all the cash and gold and this is trading at a dirt cheap multiple.
I was lucky enough to get to pitch $BUKS at the MS Microcaps Microcaps Summer Virtual Conference. You can now watch the full video now. https://t.co/JZf2c2dTIS
$LUXE keeps going no bid in this market, but I think the risk/reward here is excellent https://t.co/fCvW4k7PEI
My take from the $PUBM call is that TradeDesk disrupted their business and now other DSPs are taking share on their platform. If you dig through TradeDesk results, they really messed up. I think there is significant amount of white space for other DSPs to take share from there. https://t.co/5eYrLcwNft
I posted this mental model of $EVC in May when the stock was in high $7s. My price target for the company is $10 billion equity value or around $100 per share. Apparently some funds bought into Entravision based on this and didn’t do much of their own homework. I didn’t think I needed to say this but do your own homework if you buy a stock. I’m just some dude in rural America. I never went to college. Worked third shift in a factory all my adult life. Now I talk about stocks I like, invest my money and tweet jokes. That being said, nothing has changed with my thesis on Entravision being a potential multi-bagger. Q2 was an amazing quarter. Q3 will be an amazing quarter. You don’t measure a businesses success over a quarter, which it seems like many are doing. The best investing is done over long periods of time. Patience is the best tool for the best success. Tell me, has anything changed with the thesis? The industry is growing at a 30-50% annual rate. As long as Entravision can keep improving their models they will likely continue to grow at the industry rate. And over the past few years they have smoked the industry. One quarter of deceleration? Who cares. They probably had a model breakthrough in Q2 that accelerated revenues and I’m sure the World Cup also helped their CTV business. And to be frank, this management team is one of the most conservative teams I know. They literally start every call talking about the dying media business. Do the math on what Q4 implies if you think it’s over. Just do it. The DSP business model is one of the best I’ve ever seen. Low capital costs. Extremely high incremental margins. Scalable. Negative working capital. Back out of the media business and the spectrum assets - which are looking like they could get bid over near-term (near term is way different for me than Wall Street’s two second of pleasure btw) and you are buying Ad-Tech for an extremely low multiple, or close to nothing. I could be wrong. I don’t think there’s crazy downside here. But just remember, I’m not from the industry. I made bathtubs for a living until I started blogging. So definitely do you own research before buying blindly based on my thoughts. It is hilarious though that hedge funds were buying because of my research. Can’t wait to tell some of the guys at the shop I worked at about that. Over some Steel Reserve and Lucky Strike smokes, of course.
@WaterworldCapi1 $jets Bad industry, oil might go up again, consumer spending may roll over, and the new "capacity discipline" is more lucky accident than strategic. Somebody, probably $aal will start dumping capacity on routes again and margins back to zero
@lasse108 @ReturnsJourney $intr
Fantastic $NRP update from John. Particularly appreciate his capital allocation framework and view on why paying out 100% of cash flow makes the most sense. https://t.co/6LngKKV9hC
Leatt $LEAT Q2 '26 results: ▫️Revenues +1% *Consumer Direct +68% *Dealer Direct -2% *Distributor -6% ▫️EBIT -17.7% ▫️Net income -20% ▫️Cash of $19.5 million (+48%) ▫️Temporary supply chain timing challenges (now resolved) ▫️Consumer demand remains strong https://t.co/z8aStbpiKa
@tinderboxman No. I added another 20% of the account in $AMZN weekly options, on top of the 50% already in $AMZN equity which was 1x levered. Been applying this leverage strategy for 18 years.
$CENX is a non-AI bottleneck https://t.co/L0PvNNH4HK
@Anointed_Ape Inconsequential. $AMZN no small cap
Would’ve been a $20B+ positive swing if they’d just followed me into $AMZN at 1x leverage. And they call us Dumb Money. https://t.co/WZVVizF9zL
@eager28 @CAndreisen @quazijohir Correct. They’re tied to the same lockup as other pre-IPO investors. I’m not overthinking $SKM it’s simply my public equity proxy for Anthropic.

Steve Eisman argues the AI boom hinges on Anthropic and OpenAI’s importance to hyperscalers, while weighing software, CoreWeave and Cisco…

CoreWeave and Nebius cite AI compute shortages and higher-priced GPU renewals, but older-chip utilization and depreciation vary across…
DNOW's MRC merger targets $75 million of synergies and $350 million of 2027 EBITDA, with a $30 to $32 2029 case relying on multiple…

DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.
