
Odd Diligence on X
oklolol $oklo https://t.co/52h6TZs8vg
Tuesday, August 11
Everything we published on this day.
29 stories — the front page that day →
oklolol $oklo https://t.co/52h6TZs8vg
Mean reversion idea: $DIS super simple idea here… High quality business (parks, cruises, broadcast network, movies, ESPN, Disney+) Trading at a 25% discount to median earnings multiple while earnings recovery progressing nicely
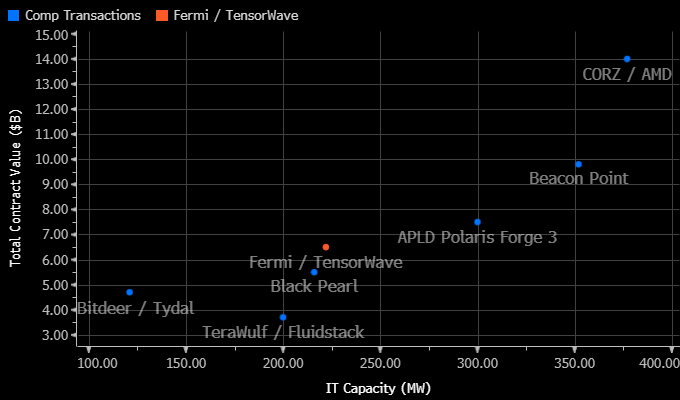
Groupon reported accelerating organic revenue and record July traffic, while Fermi signed a $6.5 billion, 222 MW TensorWave data-center…

Molina Healthcare was increased at $198 to a full position, with political-season benefits supporting the long-term thesis.
Nintendo’s sales fell 9.5% while operating profit rose 150%, aided by digital mix, a $300 million tariff refund and Switch 2 comparisons…
Lumentum’s CW lasers offer wider mode-hop-free operating ranges for co-packaged optics, supporting premium pricing and 80–90%…
Shift4 Payments trades at 6.9x EBITDA after a 50% five-year share decline, while leverage from acquisitions and slowing EPS growth weigh on…
Sea Limited reported Q2 2026 revenue of $7.8 billion, up 48%, as Shopee, Monee and Garena lifted adjusted EBITDA to $917 million.
I think $MELI's up for same reason $SE's up. Signs that Sea's reinvestment cycle is turning (or least not as aggressive as feared - see the 2H ebitda guide), which means less pressure on MELI. And maybe MELI margins have found a bottom / will inflect soon too. + Just maybe, both can co-exist & grow 50% y/y.
Me, I bought this crap (around $21.4). $SMCI https://t.co/yRsywgjrZw
@DeItaone from the low base rate, this would significantly expand $DJT revenue
Not in $OGI at the moment but this was a good report. Congrats to those who held. cc @danreaven https://t.co/Nvtr15omhI
$RILY gapping up this morning on favorable earnings report from $BW. BRC Holdings owns 27.6m shares of Babcock and Wilcox. https://t.co/SN5tDEz3T5
Can’t say there’s any slam dunk information arbitrage out of @InfoArbMonitor last batch of Delta Sheets, but there’s still a few interesting tid bits. $ASYS and $PAYS are not crazy cheap, but could be on future numbers. $NNBR probably has the best momentum, but they just went through some massive dilution. $ASYS might be my favorite out of the bunch. Thinking about buying it back at some point.
Just finished going over the $BWEN Q2 earnings script. There might be a glimmer of hope it to keep it interesting in the short term: •Unfortunately, 19% EBITDA industrial segment margins will “fall to more normal levels.” For the last three years, that’s ranged between 11 and 15%. However, revenue will be above historical levels. •Backlog is exceptionally strong, with visibility out to 2028. These guys have never had that kind of visibility. •It looks like a chance for profitability comes from me two scenarios. 1). Aggressively growing the industrial segment because it doesn’t look like margin expansion will occur. 2). The gearing segment EBITDA margins have been historically low, under 10%. So an expansion there, while also getting revenue growth might be interesting. •As far as acquisitions go, I’m not holding out for them finding a great deal. You have to think that valuations will be extended. I would actually prefer them to take their time, by being patient and growing organically - filling some of the available capacity they have right now. •In the end, it’s all about margins for these guys. They really have had a hard time keeping them stable.
$BWEN .. eh...Sales and backlog momo are strong, but still losses. Only watching to see if Co. can reverse a long history of losses, now that it has sold off its volatile wind power assets to $IESC to focus on its power generation equipment & supply chain segments. Interestingly, supply chain segment EBITDA margins were 19%, even though consolidated EBTIDA margins were 6.4%. Stock might actually rip on this KPI. Not quite sure. Do your own homework. Source: @InfoArbMonitor
Entravision $EVC has $870 million market cap here. $944 million enterprise value. Ad-Tech based on guide will do around $160mm EBITDA. Media worth $300mm based on comps. Call option on $500mm of spectrum. Say spectrum is worth zero. Back out of media and you are buying this for 4.0x and no value to spectrum. Market saying big customer goes away completely here. I think that’s wrong.
Here is my update on $EVC after Q2 earnings. Just sent out to all subs. Happy to hear any thoughts. https://t.co/TmdiUzv4my
@shortbus_ace @akeemcap @QuietProsperity $CAAP is 6x EV/EBITDA and no Mexico. But half of EBITDA is from Argentina, so that's its own can of worms (albeit the Argy fees are charged at a fixed USD rate not Peso)
@shortbus_ace @akeemcap @QuietProsperity Sheinbaum doesn't leave office until 2030 so that's a reasonable bet, though maybe you get clipped in 2029 once the pre-election hope cycle starts up. Underlying EBITDA will grow 12-15%/year like usual (faster at $ASR with the M&A) so stocks can still work in the interim.
Bancolombia $CIB tags $100 today. Congrats to the Colombia bulls, market is heating up now. https://t.co/IQTMPVvWXf
$BWEL has been the most aggressive in years on its share buybacks since the last reported financials (6/30/25). While not as significant as I would like, the increased pace of buyback is probably a good sign for FY26 results. https://t.co/tQmmswZS0P
@kingtutcap I know $VELO well any others to look at? Maybe something involved in missile production?
For FY 2027, the Company expects net sales in the range of $65.0 billion to $72.0 billion. Net sales in the range of $14.5 billion & $15.5 billion for the first quarter of FY 2027 ending September, 2026, and non-GAAP net income per diluted share of $1.01 to $1.10 $SMCI 👀 https://t.co/BMrEvmCbQj
UBS initiates $CENX conservatively: $60 at 4x EV/EBITDA > Oklahoma & shareholder return catalysts > best leverage to US MWP > Oklahoma and datacenter not priced in > 4x below normalized mid cycle https://t.co/MiKQD9rlFV
@eager28 No I’m invested indirectly via $SKM
@Ghostlike @TheOneLanceB You’re missing critical context on my $AMZN trade. If you care to dig in, start with my high-level breakdown on this week’s @TheICHpodcast.
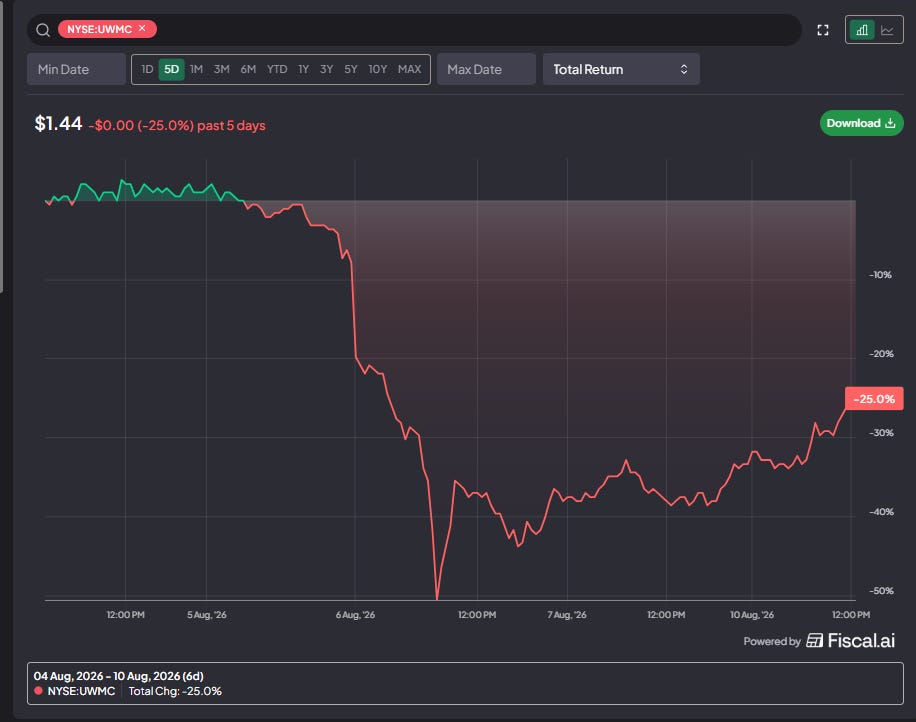
UWMC booked a roughly $600 million Q2 hedging loss tied to TWO months after the deal collapsed, contributing to an expensive capital raise.
Entravision’s ATS revenue rose 230% to $182.8 million in Q2, but shares fell from above $14 to about $8 after management forecast…
