
Dorchester Minerals: Near-Term Distributions Should Approach $1 Per Unit
Dorchester Minerals’ next two distributions are projected at $0.95 to $1.00 per unit, supported by its Williston Basin acquisition and oil…
 Elephant Analytics 3 clicks
Sector
Everything our editor has picked under this sector, best first.
159 stories
Dorchester Minerals’ next two distributions are projected at $0.95 to $1.00 per unit, supported by its Williston Basin acquisition and oil…
Elephant Analytics 3 clicks
Devon Energy’s $4.2 billion Eagle Ford sale concentrates its portfolio in the Permian, lifting capital efficiency and margins despite lower…
 Elliott Gue
Dorchester Minerals' 9.5% normalized yield and debt-free royalty model are offset by limited upside at $29.71, as extraordinary…
 Atlas Diary 3 clicks
NGL Energy Partners' capex more than quadrupled year over year as ABL borrowings and long-term debt rose, worsening its cash-generation…
 Long Player
$BORR Troim keeps buying. I'm long. https://t.co/tKu5H0eJjN
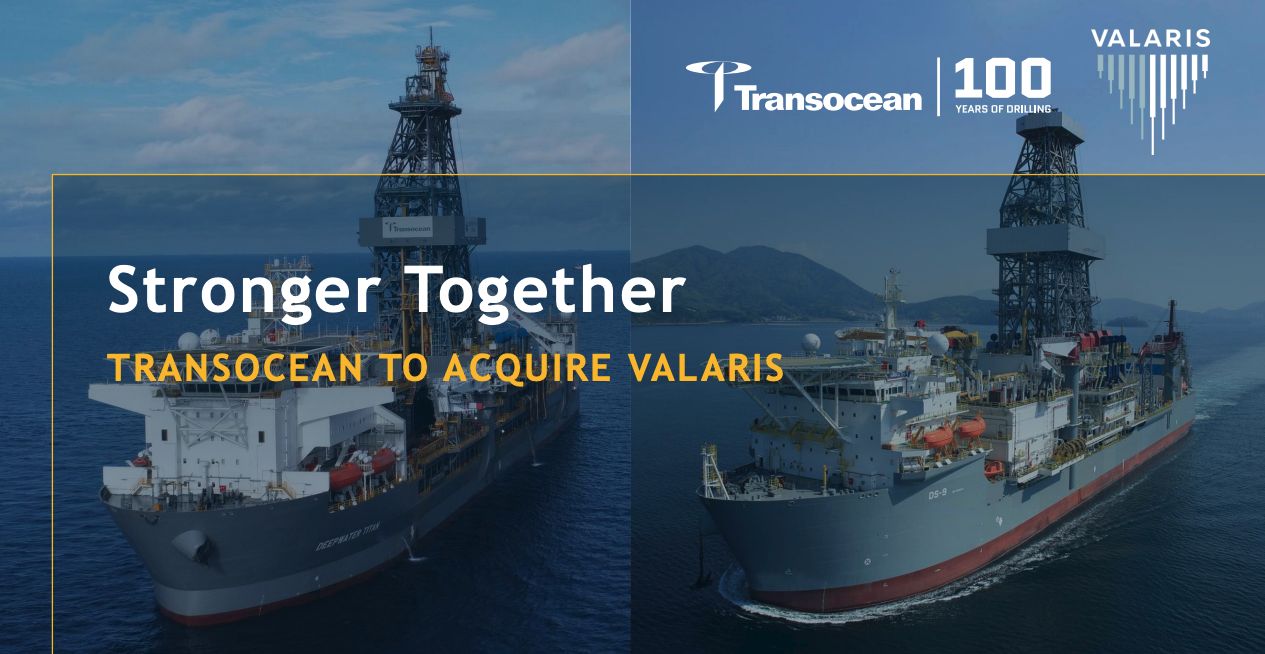
Transocean’s Valaris merger clears regulators, creating a 68-rig offshore driller controlling four in 10 global drillships.
Been tough this year when you refuse to mindlessly speculate on the AI Mania… Those trade schools ($LINC and $UTI) have really hurt. However, I have added real size the whole way down, and they’re now one of our largest exposures. This was offset by solid performance in refiners ($MPC and $VLO) which I have now harvested. The rest of the book was mostly a wash…
BP to set out new strategy after windfall year $BP https://t.co/rcdaTDuGAB
The CEO was also buying shares last month but we prefer buying by directors and that is why Tor Olav Troim's purchases were more interesting. From our Insider Weekends article about $BORR: https://t.co/RQlcc0qJqa
Another large insider purchase by a director of Borr Drilling $BORR filed today (yesterday was a holiday for the SEC and so no Form 4 filings). This is his largest single day insider purchase coming in at $11.84 million. We had been watching him buy consistently for several weeks and decided to dive into the company in an Insider Weekends article last Sunday. As we did our research, we realized that he was the founder of the company. A couple of screenshots from that article in the next tweet.
SED Energy's proposed Ventura merger projects a 22% to 40% dividend yield, but idle tender barges, debt and repayments materially reduce…
DHT Holdings earns more than $1 million daily from VLCC tankers, with Q3 EPS near $1.25 and a 20% annualized yield as spot rates outpace…
 Melissa Tucker 4 clicks
$CHRD: 6.5x FCF, Good CEO, buying back lots of stock, low-cost pure play EP. 8% FCF yield at $60 WTI. No meaningful leverage CHRD trades at ~$142, market cap ~$7.74B, enterprise value ~$8.63B. Dividend yield ~3.7% ($5.20 annual base). Buyback/total shareholder yield is higher: policy returns ≥75% of adjusted free cash flow (mostly buybacks after the base dividend) at current low leverage (<0.5x). On 2026 guidance of ~$1.3B Adj. FCF, this implies a potential total cash return yield in the low-to-mid teens. Valuation is low: ~9.5x TTM P/E, ~7.6x forward P/E, EV/EBITDA ~3.2-3.6x, P/FCF ~6.5x. Analyst consensus PT ~$166-174 (~20%+ upside); highs to $193. Marcellus non-op sale (to POSCO, expected Q4 2026 close) provides ~$550M gross proceeds, sharpening pure-play Williston focus, boosting cash/flexibility for returns or balance-sheet strength, and removing a non-core asset. Reasons for future growth: Flat-to-low absolute oil volumes (maintenance program ~161 MBopd oil) but rising per-share metrics via efficiency and buybacks. Longer laterals (majority of program, including 4-mile) cut costs/breakevens and improve recovery; base production enhancements and lower declines support volumes with less capital. Pure-play focus post-sale plus disciplined consolidator role in the Bakken. Efficiency gains already drove material FCF improvements. LTM Owner’s Earnings (Buffett-style): Roughly Net Income + DD&A + other non-cash charges − maintenance CapEx (and normalized for WC/one-time items). For this E&P, nearly all CapEx is maintenance to offset natural declines, so Owner’s Earnings approximates free cash flow. TTM (to ~Jun 30, 2026): Operating cash flow ~$2.59B, CapEx ~$1.40B → FCF ~$1.19B. DD&A ~$1.54B; Net Income ~$841M. Company-reported adjusted FCF (preferred operational proxy) was strong in 1H26 (~$738M combined Q1+Q2) and has been running at an elevated rate. This is a rigorous, cash-based measure after the capital required to sustain the business. Expected next-12-months Owner’s Earnings: ~$1.3B adjusted free cash flow (company 2026 guidance, including derivatives, at $75 WTI / $3 HH for 2H). Why higher than LTM: stronger realized oil prices vs. prior periods, operational efficiencies (longer laterals, cost controls, base enhancements), volumes at/above high-end of prior guidance, and capital discipline (CapEx held ~$1.4B midpoint). The $550M Marcellus proceeds is one-time cash (not recurring earnings) that further supports returns and balance-sheet optionality. At ≥75% payout, this supports substantial shareholder distributions while maintaining a strong BS. Business simply: Pure-play Williston Basin (Bakken) E&P—largest operator there. Drills oil-focused horizontal wells, produces/sells crude, NGLs, and gas. High-quality inventory; shift to longer laterals improves economics. Management: Danny Brown (CEO; prior Oasis/Anadarko). Track record of efficiency, synergies, disciplined capital allocation, and per-share value creation. Capital allocation: Base dividend + aggressive buybacks under the 75%+ Adj. FCF framework (leverage-dependent). Share count reduced meaningfully; cumulative returns large relative to market cap. Maintenance production focus. Risks: Oil price sensitivity/volatility (primary driver), basin decline/inventory longevity, execution on laterals or M&A, regulatory factors in ND/MT, energy transition headwinds. Margin of safety & upside: Low leverage, high cash generation even at moderate oil prices ($60-70 WTI still supports solid FCF/returns), conservative CapEx, and efficiency gains provide protection. Upside from multiple expansion toward peers/history, continued buyback accretion to per-share metrics, operational outperformance, oil strength, and pure-play clarity. Consensus implies ~20%+ near-term upside; higher in stronger commodity scenarios. Attractive FCF yield + value profile in E&P. Figures based on company results/guidance, market data, and analyst notes as of early October 2026. Oil prices and execution remain key variables.
Permian Resources uses discounted small-acreage acquisitions to supply up to 25% of drilling opportunities and build long-term growth.
Long Player  EPM · long
Evolution Petroleum (EPM) is presented as a long position.
Brazil’s October 25 runoff puts Bolsonaro’s likely victory at the center of a bullish regional-stock case; Golar LNG (GLNG) also reports…
@RealAssetsValue @hybridvigorish @thecontracap @barowsharo What just happened with $SNDA / $BKD?
Devon Energy Sells Eagle Ford Assets to Crescent Energy for $4.2 Billion $DVN https://t.co/oxm82rChuU
Golar LNG ordered a $2.45 billion fourth FLNG vessel, targeting 3.5MTPA of capacity and $400 million in annual EBITDA under a 20-year…
Still a lot of smart money involved in $SOC (and adding). Wondering if the upcoming catalysts, particularly Hondo’s restart, potential NDAA protections and a West Coast SPR decision, could finally get this thing moving? The prospective FCF generation is pretty remarkable if they can execute…
BP is investing $10 billion annually in oil and gas through 2027 as higher crude prices, LNG expansion and debt reduction support earnings,…
 The Asian Investor 6 clicks
Energy Transfer to Acquire Vaquero Midstream for $2.63 Billion $ET https://t.co/1pJ4LXgSc6
Golar LNG’s fourth FLNG vessel targets 3.5MTPA capacity and a 2029 delivery, supporting projected adjusted EBITDA above $1 billion in…
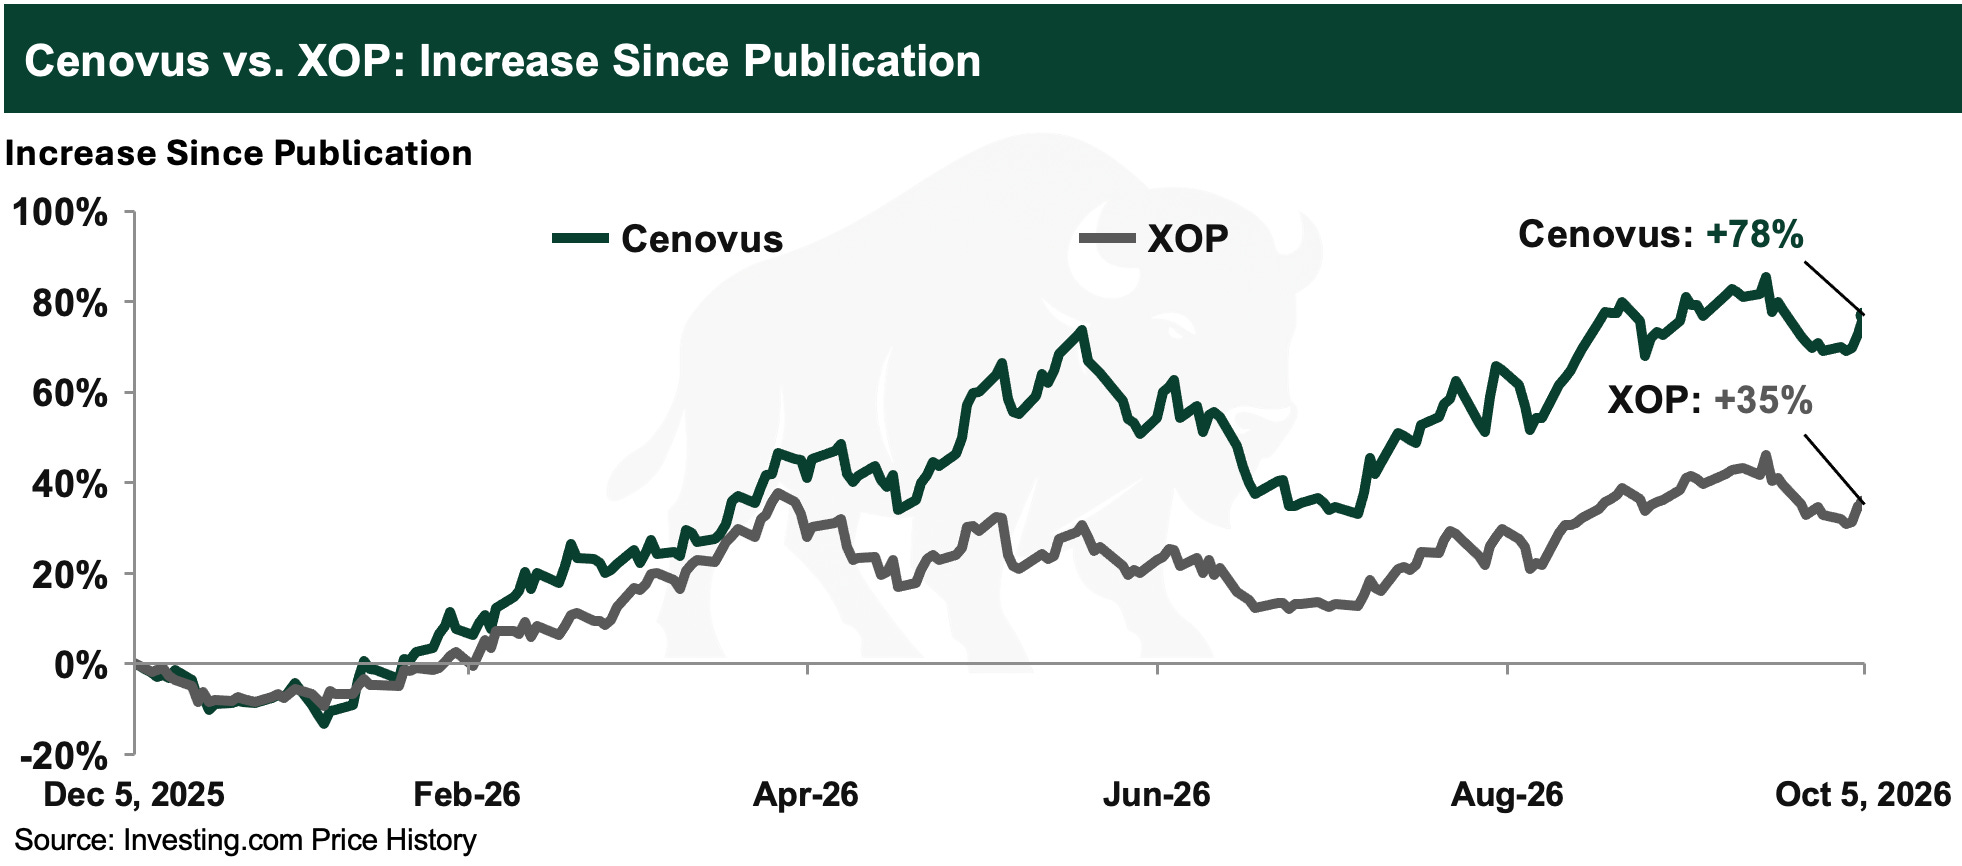
Cenovus Energy, up 78% in 10 months, is sold after agreeing to buy Athabasca Oil for $5.7 billion at a rich valuation.
