
 MSI · long
Motorola Solutions INC
Motorola Solutions’ core value proposition remains intact after business changes since 2022, supporting a growth-at-a-reasonable-price…
Tuesday, June 23
Everything we published on this day.
13 stories
MSI · long Motorola Solutions’ core value proposition remains intact after business changes since 2022, supporting a growth-at-a-reasonable-price…
 OPRX · long
OptimizeRx, OPRX, trades 30% below its February 2025 writeup despite becoming a stronger company.
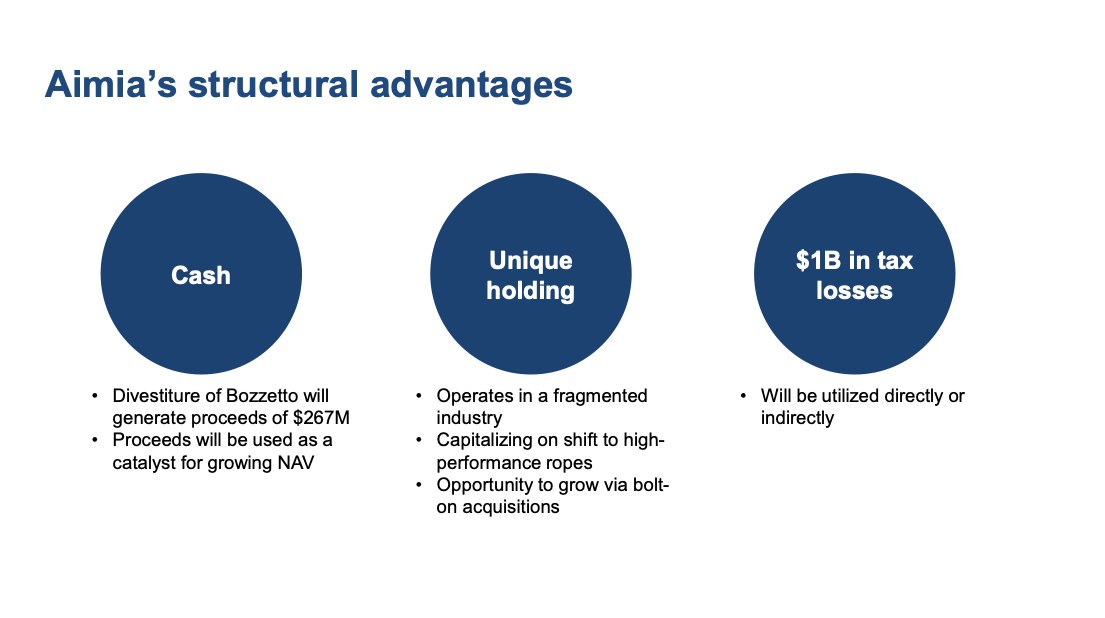
Aimia trades at 0.75 times pro forma book value, with C$163 million to C$192 million of cash after the Bozzetto sale and Rhys Summerton…
Micron’s $1.37 trillion valuation prices in durable HBM and AI-driven memory profits, despite Q3 guidance for $33.5 billion revenue and an…
Good question. As I mentioned, all of my checks suggest they're gaining wallet share with small businesses at the expense of $GOOG. There are other big issues around regulatory recourse, stalling user growth in an increasing number of markets, and of course capital allocation. The multiple reflects the magnitude of unknowns or lack of visibility. Changing that to some degree would be a start.
In the case of $GOOG, Adwords, which in my view is the greatest business model ever created is now being replaced by something quite different and considerably worse. In the case of $META, there's a long list. I don't share your view of the caliber of that business even while I recognize the considerable ad share gains they continue to get. The toxicity of the platform matters greatly if you're thinking of this business in any kind of longer term context.
I've been short $META for a while as I mentioned in previous posts. I'm fully aware that $META has been benefitting in continued shift of ad dollars away from $GOOG (I'm also short $GOOG) as we transition away from the SEO/SEM world to AEO/GEO. However, nothing can mess up a good fundamental story like poor capital allocation and Zuck and co. have demonstrated time and time again that they're willing to pull defeat from the jaws of victory. This latest effort to go and compete with Kalshi, polymarket, and even the traditional broker/dealers to get into betting markets is just another example. Betting markets doesn't represent the existential risk to the biz like AI does, why even consider getting into this now? Based on chatter about their upcoming AI model updates, it seems CAPEX at $META is poised to go way up, yet again. Will the street like that? I guess if their latest model is Mythos quality or better, maybe it will be tolerated. Maybe, but probably not. What is it about Zuck that he feels the need to be all things to all people? Does he not understand the strengths of his own business or is he worried about the duration of those strengths? Maybe it's just ultimate hubris. Either way, at some point soon he probably pulls the reigns back as the market continues to penalize $META for the absurdities of their capital incineration.
FWIW, I'm pretty sure Doug Lebda of $TREE experienced a (-95%)-(-99%) drawdown in 2000, 2008, and again post COVID-19. The company was purchased by $IAC and then spun out again after the dotcom bubble burst. Of course that implies that $TREE was a 10+ bagger on two separate occasions. RIP Mr. Lebda.
Little perplexed you get more negative redemption stories around private credit, and the market only sells off the the the pure play PE companies. First derivatives are up? $MFC $FG $MET $WAL all have sizable exposure to the same asset class.....
@waterboystocks DPZ looks interesting, but I have pizza covered with little Pizza Inn $RAVE. 100% franchised, zero debt, cash ~25% of market cap, potential for turnaround to transform into growth story next 1-2 years.
@Akston_Capital Putting aside what the shareholders, directors, activist ahareholders @HoldCoAM, his wife and anyone else, what does Chris Gorman, in his heart, want to accomplish at $KEY? Keep going as is? Acquire? Sell?
$META probably can serve more tactical ads if you know exactly what each user is willing to put money on (aka is paying attention to) in the moment! https://t.co/9DnpLAIS4i
Is contextlogic interesting/worth digging into? $LOGC. I really like the Salt acquisition but seems like they paid a rich multiple for it. Fear this will end up in the graveyard of mini-Berkshires over time
