
2026: Radio silence, software setbacks and more from me in 2026
RELX and Sage have fallen 46% and 35% as markets label them AI losers, creating potential value opportunities alongside risks of genuine…
Thursday, February 5
Everything we published on this day.
7 stories
RELX and Sage have fallen 46% and 35% as markets label them AI losers, creating potential value opportunities alongside risks of genuine…
$AAPL looking pretty smart staying out of the the AI capex wars 😉 This story is not over yet.
Just hammering this home. For simplicity's sake, let's use round numbers for 2025: 1) J&T Order Volume Grows: 75% y/y 2) Tiktok & Other Customers Grows: 40% y/y 3) J&T Grows Market Share from 27% in 2024 > 33% in 2025 (disclosed in the 1H25 Report) 4) Non-platform % of revenue goes from 0% > 10% in 2025. All the data-points line up. Takeaway: It can be true that J&T grew 75% y/y, AND Tiktok is slowing to 40% y/y orders growth (and 30% y/y GMV). - Market narrative of Tiktok competition increasing is likely wrong. - Means that Shopee's recent spend is not a defensive move or coming from a weakened position. - In fact, they're pressing harder, while competition is weak (That's just how they operate. They waited to grow Monee loans, until the digibanks started blowing up. That's why you see an inflection in loan growth 2 years ago. Compare that to when Indo digibank NPLs started blowing up, and you'll see the correlation). Included pictures of the math (thanks ChatGPT). $SE $1519.HK
From J&T's 4Q25 call. They called out 1) winning share from competitors and 2) non-platform parcels growing (i.e. not from Shopee or TTS). So perhaps J&T's strong volume growth isn't related to TTS vs. Shopee competition? $SE $1519.HK https://t.co/Jn0UArEo04 https://t.co/pbA0DXJsD6
@TrigramPartners That's possible. All international ecom stocks have traded down the last few months. CPNG, MELI, etc. But at $107, $SE is trading at 7x 2028 EV/EBITDA, with 30% y/y EBITDA growth. Seems a bit extreme?
$SE is down -45% over the past few months. The prevailing bear case seems to hinge on two points: 1) Rising fear of TikTok Shop competition, and 2) Shopee reinvesting more heavily into logistics, capping margins at ~0.7% of GMV this year vs. prior expectations of ~1.2%. The concern is that this spend is defensive - a necessary response to TikTok rather than a choice. But alt data is telling a different story. TikTok Shop’s Southeast Asia GMV growth has slowed materially over the past few quarters - from 70%+ in 2Q25 to ~30%+ by late 2025. That’s only modestly above Shopee’s own growth rate. More notably, TikTok’s relative share vs. Shopee in Indonesia (~50% of regional GMV) has effectively flat-lined over the past year. If this data is directionally right, Shopee’s ~50 bps of reinvestment looks discretionary and offensive -widening the moat - rather than a defensive reaction to competitive pressure. And critically, that implies the margin compression is temporary, not structural. Oh, and both Shopee & Tiktok are raising take-rates. Not usually the sign of a competitor trying to aggressively take share... Curious, what am I missing? Is the -45% drawdown really just “2026 margins down > negative 2026 earnings revisions > stock down,” even if margins are likely to re-expand next year? And Shopee emerges with a wider moat after? The competitive backdrop looks like it’s improving, not deteriorating...

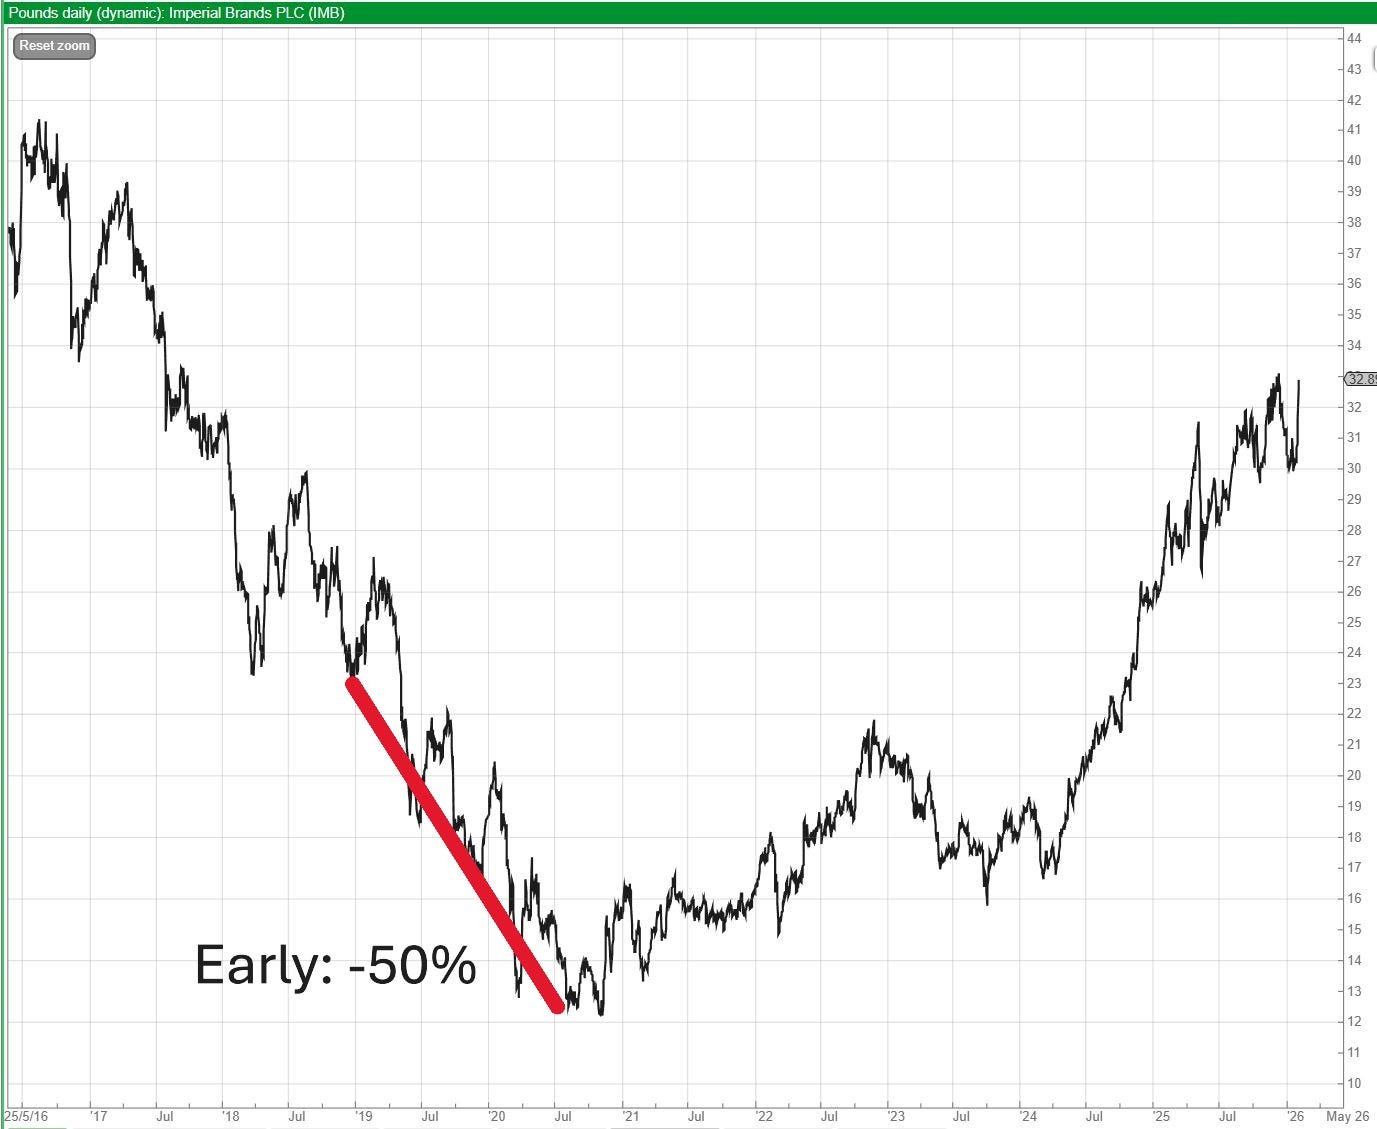
A former value-investor darling, down 50%, pairs a monopoly with a recurring-revenue razor-and-blade business; debt paydown, margin…
